


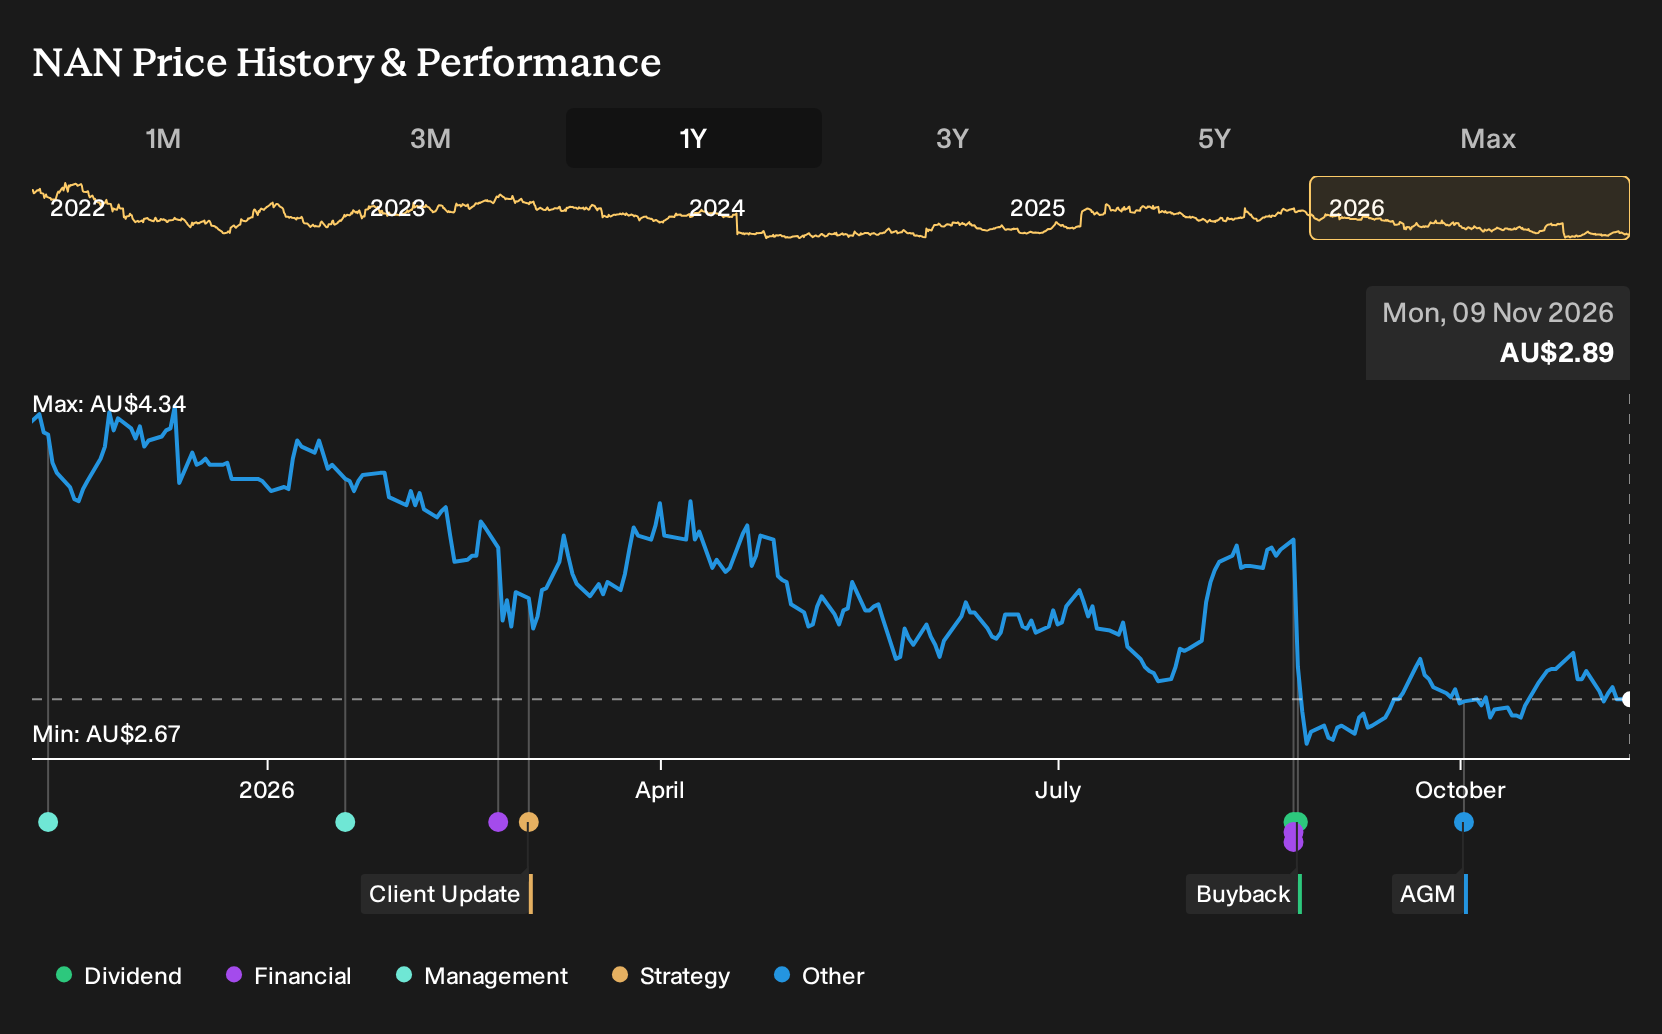
Holding Nanosonics over the past year would have meant a 31.8% loss, including dividends. If you had bought on 6 November 2025, you would have been buying into a bullish story that expected faster revenue expansion, margin uplift, and a richer 2028 P/E multiple, while the cautious view still assumed mid single digit sales growth and thinner profitability. So what exactly did those optimistic and pessimistic cases miss about how this business might actually trade through a year like that?
Nanosonics has already moved. Pinpoint other ways to investigate the theme among 7 healthcare AI stocks.
The Two Stories Investors Were Weighing On Nanosonics
The shares cost A$4.27 at the start of the period, and anyone buying Nanosonics then had to choose between two very different but plausible stories.
The bullish camp saw a Fair Value of A$6, a price they felt was justified if automated disinfection benefited from aging demographics, tighter regulation, and faster take up of trophon and CORIS. Vertically integrated manufacturing in Indianapolis was also expected to help margins.
The bearish view argued for a Fair Value of A$3.75, assuming hospital cost containment kept equipment sales flat and that new disinfection technologies and stronger hospital bargaining power steadily reduced pricing and profitability.
What The Results Changed For Nanosonics
The clearest development was Nanosonics reporting FY26 revenue of A$203.9m, with 6% constant currency growth and a 76.9% gross margin, alongside a 21% constant currency lift in EBIT to A$21.6m. That broadly backed the optimistic case on installed base expansion and high gross profitability, yet the reported H2 2026 numbers undercut the margin uplift story.
H2 2026 revenue slipped to A$101.7m and net income fell to A$8.2m, with net margin down from 10.4% to 8.1%. The period cut both ways. For your next stock, focus on whether a bullish thesis rests on margin expansion. Then track net margin and EBIT against those promises each reporting season.
What Today's Nanosonics Share Price Is Asking You To Believe
Nanosonics trades at A$2.89 today, well below where holders were a year ago. The analyst consensus narrative on Simply Wall St sees fair value above that level, based on the idea that trophon and CORIS together can justify a richer business profile.
For the share price fall to look like an opening instead of a warning, a buyer has to believe CORIS scales into a genuine second earnings engine while the trophon base keeps throwing off reliable cash.
"The current share price, together with the recent broker upgrade and ongoing buybacks, suggests the market is still discounting Nanosonics' cash generative trophon-only business and the potential for CORIS to become a second earnings platform."
One Narrative has put a figure on that disagreement. → See the Narrative with its higher Fair Value, assumptions and all
Looking Beyond Nanosonics' Devices
Nanosonics keeps you focused on infection control hardware and clear, equipment based solutions.
Step one layer out and another question appears for hospitals under pressure.
Who helps hospitals afford all this technology in the first place when budgets tighten?
Large health benefit providers shape budgets, benefit designs and care programs across systems.
One giant there is pushing deeper into value based care and heavy AI automation, a shift that could quietly reshape how demand and funding move through healthcare.
It is written up in full, assumptions and all. → Explore the Narrative that puts this company 22% above its price
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com