


- Genesis Minerals has recently accelerated development of its Tower Hill gold project in the Leonora district, supported by key permits, rail arrangements and mining agreements that will influence how quickly higher grade ore could reach its processing hubs.
- This earlier initiation of Tower Hill activity increases the focus on project funding, capital intensity and whether future operating margins can absorb the additional growth-related spending.
- The progression of Genesis Minerals' investment narrative will now be influenced by the faster Tower Hill schedule and the associated capital requirements.
Contrast Genesis Minerals' Tower Hill acceleration with other growth-focused juniors by scanning the hand-picked 18 elite penny stocks with strong financials list that also pairs project scale with balance sheet strength.
Genesis Minerals Investment Narrative Recap
To own Genesis Minerals, you need to back a fairly clear idea. The business is trying to turn a large Western Australian gold footprint into a coordinated production hub, with Tower Hill feeding into expanded mills at Leonora and Laverton. The recent acceleration at Tower Hill tightens timelines. That makes near term execution on mine development, processing readiness and ore scheduling even more important than before.
The biggest short term swing factor now sits around how smoothly this extra Tower Hill activity integrates with existing sites and contractor changes underground. Funding the A$220 million to A$240 million of growth capital, while keeping all in sustaining costs, tax outflows and cash generation in balance, appears to be the key operational risk that could pressure margins if projects overrun or gold prices soften.
The analyst consensus narrative on Simply Wall St highlights several moving parts. The Tower Hill growth capital decision is the announcement that matters most for this news. Pulling that A$220 million to A$240 million spend forward ties directly into the push to get higher grade ore into the Leonora processing circuit earlier. That same plan also increases exposure to project timing and cost control.
For shareholders, this Tower Hill acceleration intersects with other live catalysts. Mill expansion work, the shift to Byrnecut at Leonora and cost programs like Project TALO all aim to support margins and throughput. Risks span capital intensity, refractory ore solutions and the step up in cash tax from FY26. Genesis Minerals now has less room for missteps because so many of these levers are being pulled at once.
Genesis Minerals' current analyst narrative points to revenues of A$2.4b and earnings of A$892.6 million by 2029, which implies forecast revenue growth of 11.6% per year and an earnings increase of about A$290.8 million from A$601.8 million today.
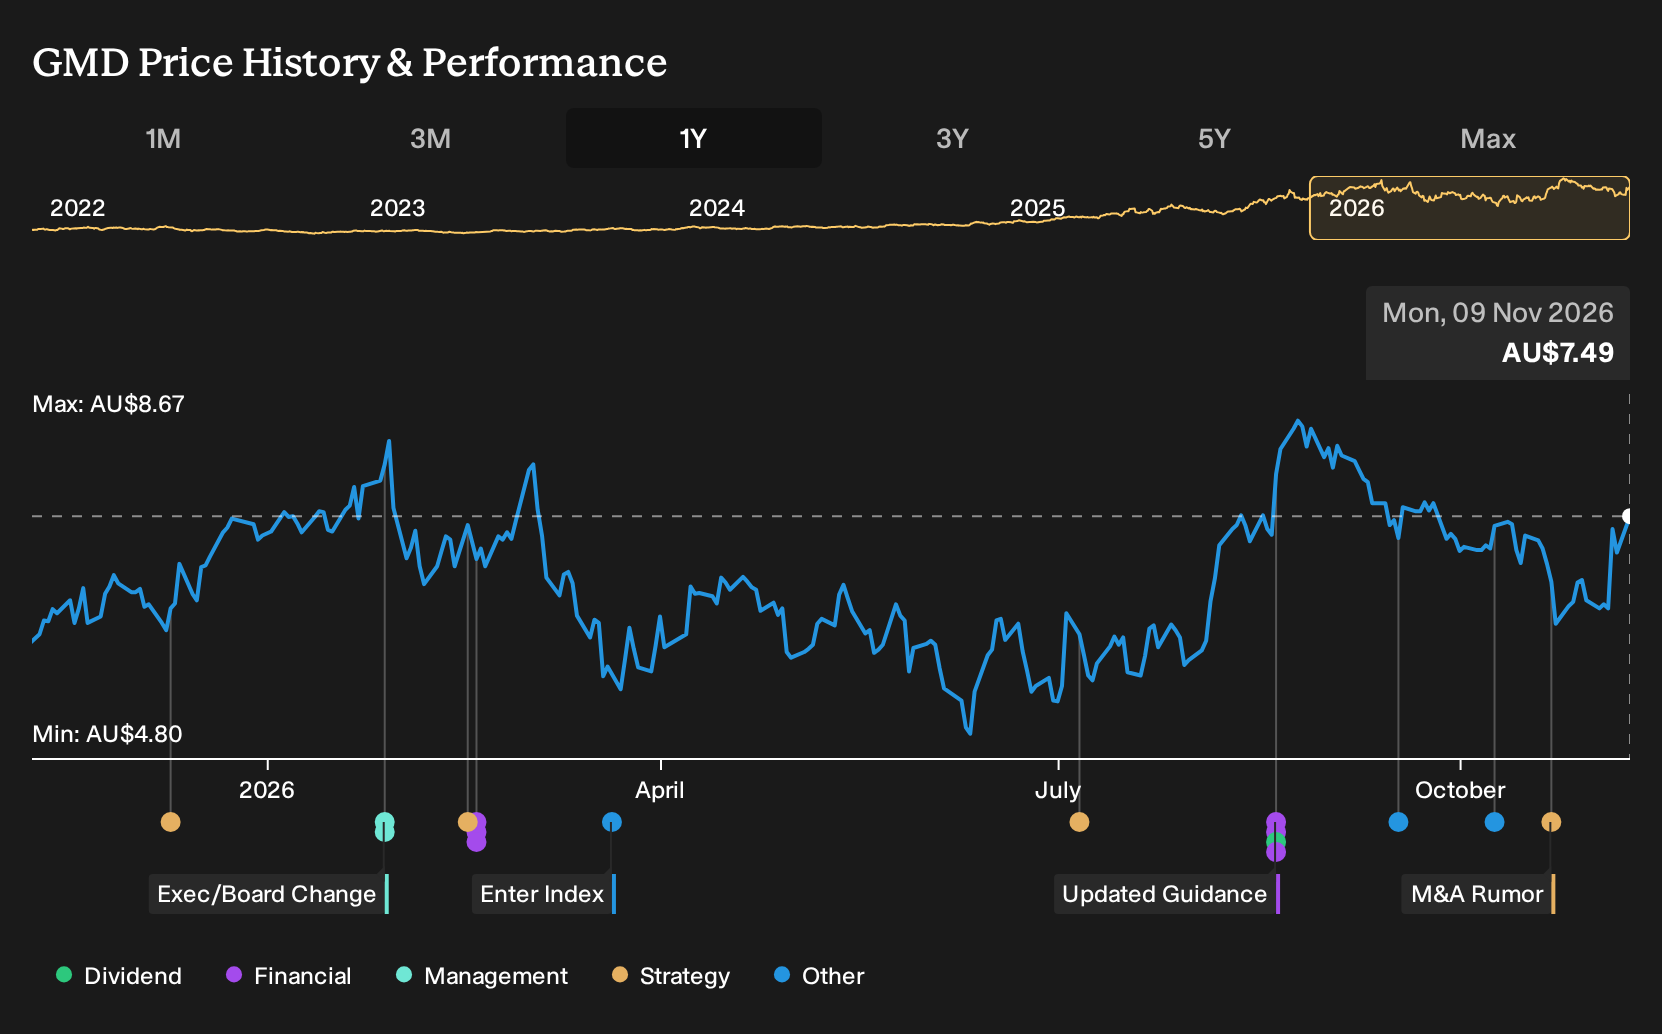
Uncover why Genesis Minerals' fair value indicates a 26% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
Some of the most optimistic analysts frame the proposed Vault merger and its A$2b of targeted post tax synergies as the real swing factor rather than Tower Hill timing. Before this news, that bullish group was already pencilling in A$3.0b of revenue and A$1.1b of earnings by 2029. You can compare those expectations with the consensus forecasts to see how your own view of Genesis Minerals lines up and how this latest development might reshape both stories.
Explore 4 other Genesis Minerals fair value estimates, including one that suggests as much as 289% upside from the current price!
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Genesis Minerals research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Genesis Minerals. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Genesis Minerals' overall financial health at a glance.
Looking For More Investment Ideas Beyond Genesis Minerals?
Once you have a view on Genesis Minerals, it can help to cross check that thinking against other opportunities using the Simply Wall St Screener.
- If you want potential growth with tighter budgets, scan for early stage operators that pair project upside with stronger finances via the 18 elite penny stocks with strong financials.
- For investors who prefer quality at a discount, review companies that combine healthy cash flows and modest valuations using the 3 high quality undervalued stocks.
- If resilience matters more than excitement in your portfolio, sort for steadier balance sheets and dependable fundamentals with the list of solid balance sheet and fundamentals (12 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com