


- Yancoal Australia announced that its board approved renewal of the coal sales framework agreement with Glencore from 1 January 2027 to 31 December 2029, with new annual caps set for coal transactions under this long running customer relationship.
- The renewed framework with Glencore helps clarify future coal offtake volumes and commercial terms for the Yancoal Australia group. This directly affects production planning, marketing flexibility, and how the business manages contract exposure versus spot sales.
- We will look at how Yancoal Australia's broader investment narrative is shaped by the renewed Glencore coal sales framework and its transaction caps.
What Is Yancoal Australia's Investment Narrative?
The big bet with Yancoal Australia is simple. You need to believe this is an operator that can keep running large, complex coal assets efficiently while selling into a global customer base that still wants its product. The renewed Glencore framework goes straight to that question. It gives clearer visibility on offtake and pricing structure with a key buyer, which feeds into mine scheduling, logistics and how much coal can be comfortably pre sold rather than pushed into the spot market.
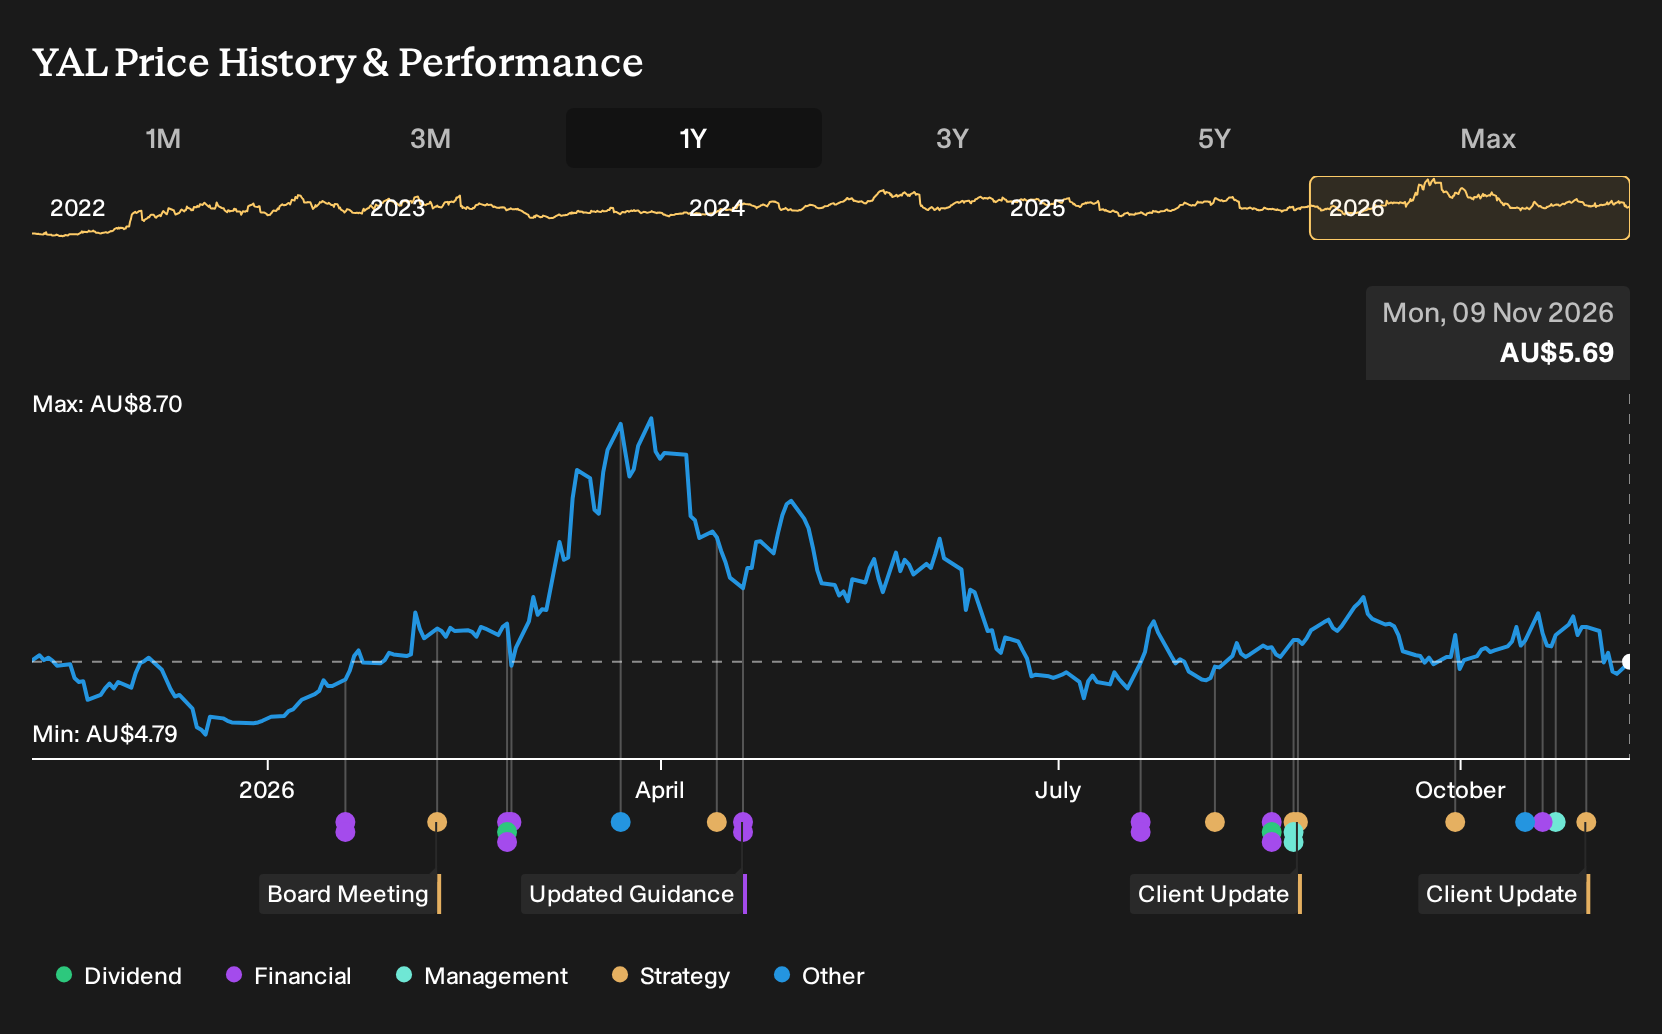
In the short term, that clarity helps frame near term earnings drivers, even as profit margins sit at 4.7%, well below last year’s 15%. Execution on costs, capital spend and volumes still does the heavy lifting. The share price has risen 0.3% over one day but is down over 7% across three months, which suggests the market has not treated this renewal as a game changer on its own.
That said, there is a more awkward angle to this customer concentration story that hinges on ...
There's only one way to know the right time to buy, sell or hold Yancoal Australia. Head to Simply Wall St's company report for the latest analysis of Yancoal Australia's Fair Value.
Decide For Yourself
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Yancoal Australia research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Yancoal Australia. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Yancoal Australia's overall financial health at a glance.
Looking For More Ideas Beyond Yancoal Australia?
If you like the clarity around Yancoal Australia's renewed Glencore agreement but want to widen your opportunity set, a quick scan of other companies with different drivers can sharpen your watchlist and help you compare risk, balance sheet strength and income potential side by side.
- For investors who care most about financial resilience and clean balance sheets, start with a curated list of solid balance sheet and fundamentals (12 results) that filters for businesses with stronger fundamentals already in place.
- If your focus is on finding quality at a reasonable price, cast a wider net using our hand picked 3 high quality undervalued stocks that screens for companies where fundamentals and current pricing may be out of sync.
- Income seekers who want cash returns front and center can zero in on reliable payers through a targeted 5 dividend fortresses designed around higher yielding, established distributions.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com