


Arlo Technologies (ARLO) moved into focus after its latest quarterly results, with higher third quarter revenue, strong subscription and services expansion, fresh fourth quarter guidance, and a newly approved share repurchase program.
Recent trading has been rough for Arlo Technologies, with the share price down 16.9% on the day and 16.2% over 90 days as investors digest softer quarterly net income alongside new buyback activity and guidance. However, the 3 year total shareholder return of 55.6% and 5 year total shareholder return of 62.6% point to longer term holders still being ahead despite the current loss of momentum.
Scan beyond Arlo Technologies and see how other recurring revenue players with strong fundamentals are setting up right now in our hand picked 19 high quality undiscovered gems list.
After a 1 day drop of 16.9% and fresh buyback news, Arlo Technologies now sits at a crossroads. Is this pullback enough to justify stepping in today, or does patience make more sense when you look at the valuation next?
Most Popular Narrative: 40% Undervalued
The analyst consensus Narrative on Simply Wall St flags a fair value for Arlo Technologies at $20.67 compared with the last close at $12.34. This frames the recent pullback against a materially higher long term valuation anchor. That view rests on measured revenue and earnings forecasts alongside assumptions about how far the subscription model can scale.
Continual migration toward a services first model, with subscriptions and services already around 60% of revenue, ARR of about US$357 to 365 million and non GAAP services gross margin above 84%, points to a mix that is structurally geared toward recurring revenue and higher blended margins that can support earnings power over time.
See why 12 investors see Arlo Technologies as 40% undervalued.
Result: Fair Value of $20.67 (UNDERVALUED)
Still, the story can break if hardware price competition keeps product margins under pressure, or if legal and governance issues continue to drag on investor confidence.
Find out about the key risks to this Arlo Technologies narrative.
Another View on Arlo Technologies: Earnings Multiple Looks Stretched
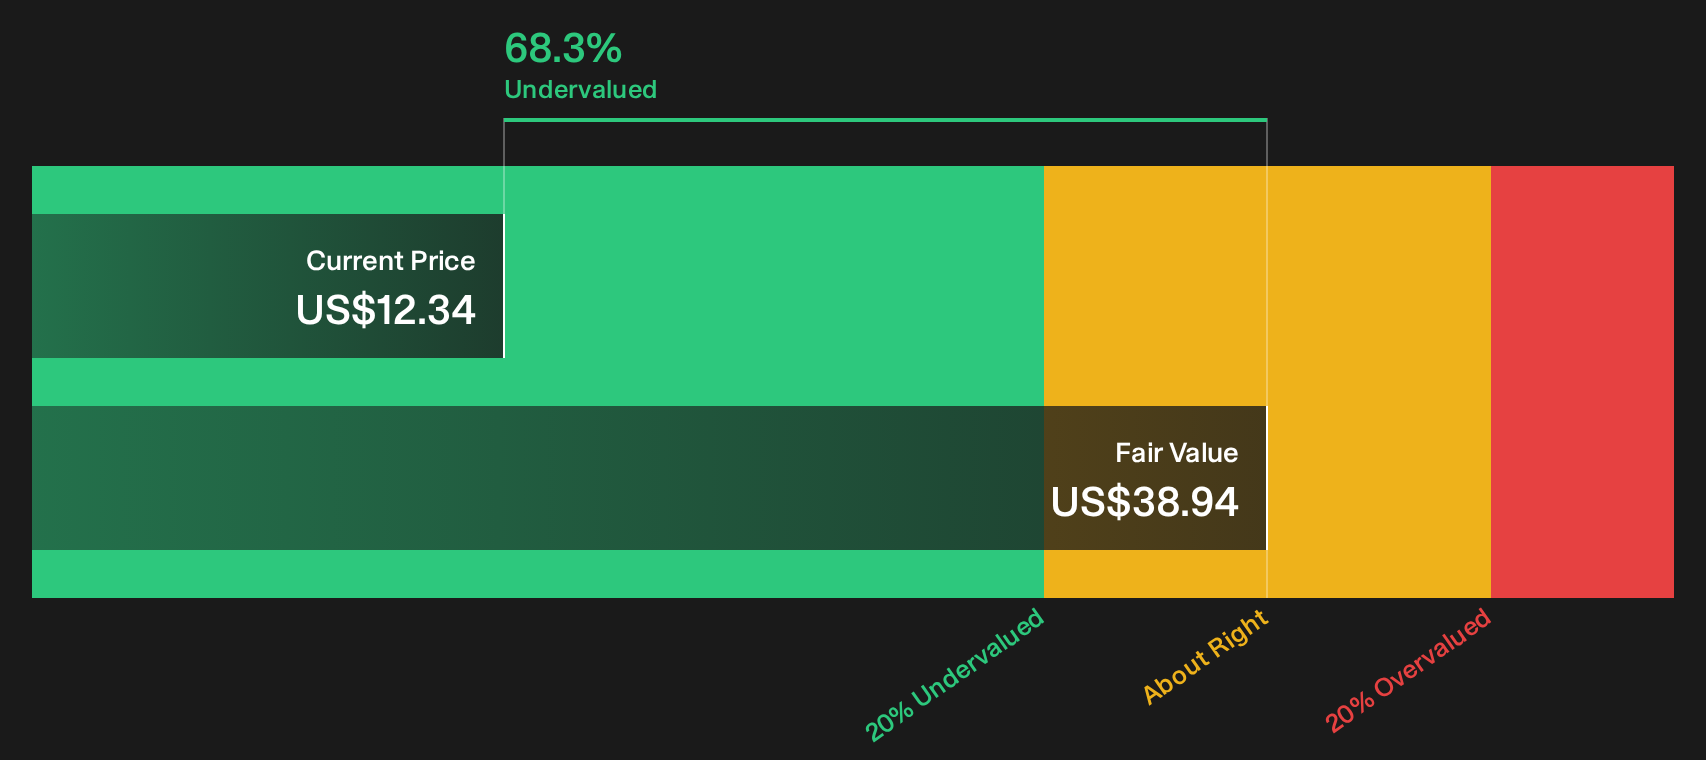
The SWS DCF model points to a future cash flow value of $38.94 per share, which signals upside against the $12.34 price. Yet on a plain P/E comparison, Arlo Technologies trades at 54.1x versus 25x for the US Electronic industry and 22.3x for peers, while the fair ratio is 23.1x. That gap suggests meaningful valuation risk if sentiment cools.
Before relying on either signal too heavily, it is worth seeing how the numbers behind our DCF approach stack up against your own expectations for growth and margins. Look into how the SWS DCF model arrives at its fair value.
Next Steps
Sentiment around Arlo Technologies is split, with clear reasons for caution and optimism sitting side by side. Move quickly to review the underlying data and form your own take using our breakdown of 4 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Arlo Technologies?
If Arlo Technologies has your attention today, do not stop here. Broader opportunities often sit just outside your current watchlist, waiting for fresh research.
- Target potential mispricings by scanning companies that combine quality fundamentals with appealing entry prices through the 40 high quality undervalued stocks.
- Strengthen your income focus by reviewing businesses that offer higher yields in the 7 dividend fortresses and see which ones align with your risk tolerance.
- Prioritize resilience by filtering for companies with sturdy finances using the list of solid balance sheet and fundamentals (25 results) so you do not overlook sturdier alternatives.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com