


- BNP Paribas reported third quarter net interest income of €13,757 million and net income of €3,456 million, alongside a €1.3b share buyback programme with repurchased shares to be cancelled.
- The combination of higher net interest income over the quarter and nine month periods and the planned reduction in share count highlights BNP Paribas's current earnings power and capital return capacity for investors.
- We will now look at how BNP Paribas's €1.3b share buyback plan could reshape the broader investment narrative around the group.
BNP Paribas Investment Narrative Recap
To own BNP Paribas, you need to believe the bank can keep converting its large Eurozone footprint, efficiency program and capital strength into resilient earnings, despite regulated home markets and funding mix risks. The analyst consensus Narrative on Simply Wall St emphasizes execution of the cost and AI program and disciplined capital use as the main drivers.
Right now, the key short term swing factor is how cleanly BNP Paribas delivers on efficiency and credit quality while used car and Arval related pressures are in focus. The new leadership appointments in Leasing Solutions look incremental for now and do not materially change that near term risk reward balance.
The third quarter update, with net interest income of €13,757 million and net income of €3,456 million, is the operational anchor for this latest leadership reshuffle. Those figures, alongside the nine month numbers and current CET1 position, give context for investors weighing whether the execution risk around restructuring and digitisation is acceptable.
Against that backdrop, the €1.3b share buyback plan, with repurchased shares to be cancelled, is the announcement that most directly connects to the catalysts in the analyst consensus Narrative on Simply Wall St. It ties into the idea of surplus capital supporting per share metrics, while still leaving investors exposed to familiar risks such as Eurozone margin pressure, Arval sensitivity to used car prices and ESG related litigation.
What The Forecasts Assume For BNP Paribas
Analysts sketch out a BNP Paribas trajectory that leans heavily on gradual revenue expansion and a step up in profitability rather than a dramatic shift in the business model. Consensus assumptions point to revenue growing by 6.0% a year over the next three years, with profit margins moving from 24.9% today to 26.9% over that period. On current estimates, earnings are €12.8b today and are projected to reach €16.4b by about 2029, with some forecasts as high as €18.5b. That central case implies an earnings increase of roughly €3.6b over the period, supported in part by an expected 1.74% yearly decline in the share count over the next three years as buybacks like the current €1.3b programme continue to reduce the number of shares outstanding.
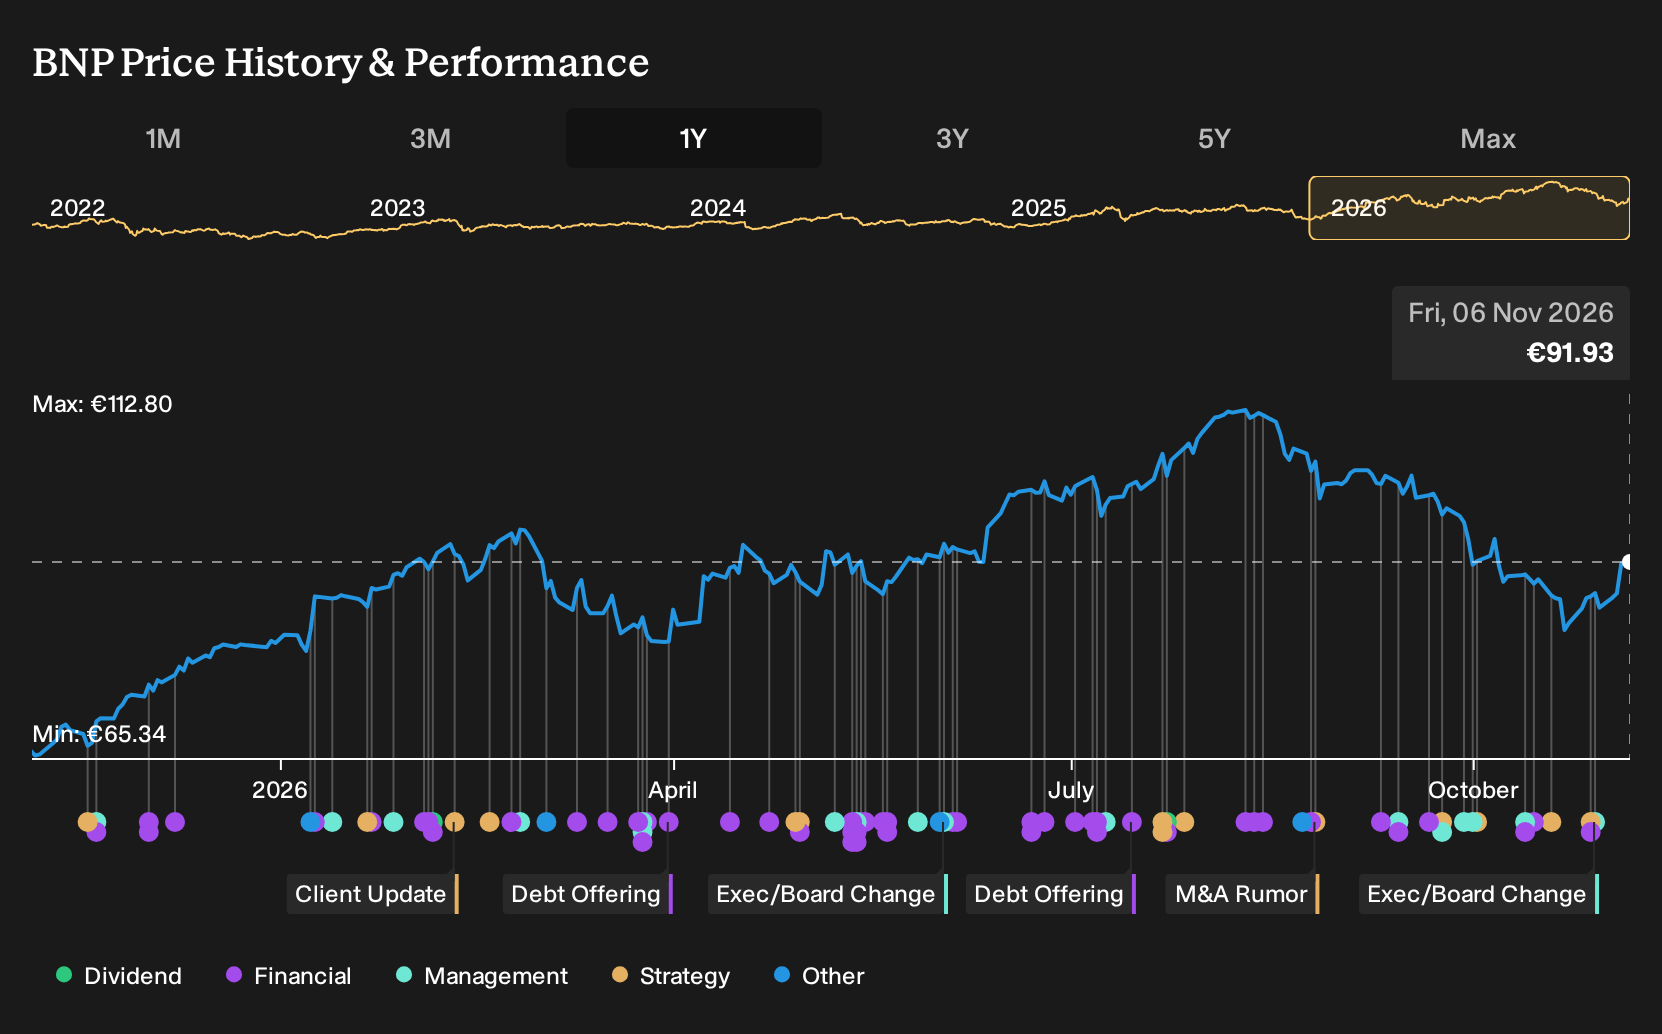
Valuation work built on those inputs points to 2029 revenues of €61.0b and earnings of €16.4b. In that scenario, the stock would trade on a P/E of 10.7x those 2029 earnings, compared with 7.7x today and 7.8x for the GB Banks industry based on the report. The consensus price target of €119.07 implies a 24.3% gap to the current share price of €90.09, with the most optimistic analysts at €136.0 and the most cautious at €96.5. For any investor weighing BNP Paribas today, the key question is how comfortable you are with those revenue, margin and multiple assumptions, and whether your own expectations about regulation, Eurozone profitability and credit costs sit above or below that analyst baseline.
BNP Paribas' narrative projects €61.0b revenue and €16.4b earnings by 2029. This rests on 6.0% yearly revenue growth and an earnings increase of about €3.6b from €12.8b today.
Uncover why BNP Paribas' fair value indicates a 30% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
Two fair value estimates from the Simply Wall St Community cluster between about €107 and €119, close to the analyst target band already discussed. Those private investors are not factoring in the latest €1.3b BNP Paribas buyback or the Leasing Solutions leadership changes, so you are seeing pre catalyst opinions. Use that gap as a prompt to explore more viewpoints.
Explore another BNP Paribas fair value estimate, including one that suggests it could be worth just €107.12.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your own analysis and judgment.
- A great starting point for your BNP Paribas research is our analysis highlighting 4 key rewards and 4 important warning signs that could impact your investment decision.
- See our latest analysis for BNP Paribas. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate BNP Paribas' overall financial health at a glance.
Looking For More Ideas Beyond BNP Paribas?
If BNP Paribas is only one piece of your watchlist, it can help to line it up against other listed businesses with different risk and reward profiles. The Simply Wall St Screener gives you a quick way to sort through wider markets using fundamentals rather than headlines.
- For investors who care most about resilient balance sheets and steadier financial profiles, start with a 207 resilient stocks with low risk scores that surfaces companies with lower risk scores.
- If value is your priority and you want to see where quality and price intersect, filter for businesses trading on attractive metrics using a 222 high quality undervalued stocks that focuses on fundamentals.
- For those hunting for strong cash returns, build a shortlist of income ideas through a 226 dividend fortresses that highlights higher yielding dividend payers.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com