


Q3 sales update refocuses attention on Vetoquinol
Vetoquinol (ENXTPA:VETO) has put fresh numbers on the table, reporting third quarter 2026 sales of €139.7 million and nine month sales of €399 million, both above the prior year periods.
Recent sales news lands against a share price that has climbed 23.12% over the past 90 days and 13.92% over the past month. Vetoquinol’s 1 year total shareholder return of 23.77% contrasts with a weaker 5 year total shareholder return that is down 36.72%, hinting that momentum has picked up only relatively recently.
Capture this renewed interest in Vetoquinol by lining it up against 214 high quality undervalued stocks that also pair resilient sales with solid fundamentals.Recent gains now sit at the crossroads of sturdier sales at Vetoquinol and a change in mood around the stock. Which of those is really driving value at today’s price?
Price-to-earnings of 16.4x: Is it justified?
On recent numbers, Vetoquinol trades on a P/E of 16.4x, which screens cheaper than peers yet still above the level some models suggest as fair for this stock.
The P/E ratio compares the share price to earnings per share and, for a veterinary pharmaceutical group like Vetoquinol, it gives a quick sense of how much investors are paying for every euro of profit. With earnings reported as having grown around 4% per year over the past 5 years and current net profit margins at 11.9%, the current multiple reflects how the market prices those established, but not rapid, profit trends.
Relative to the wider European Pharmaceuticals industry average P/E of 21.8x, the 16.4x multiple looks materially lower, which indicates investors are paying less for each euro of earnings than they are for many peers. At the same time, a fair P/E based on Simply Wall St’s regression work is 15.1x, so the current price is above a level the market could potentially migrate towards if sentiment cools.
Explore the SWS fair ratio for Vetoquinol.
Result: Price-to-earnings of 16.4x (ABOUT RIGHT)
Still, the Vetoquinol story can quickly look different if earnings growth slows or if investors decide the recent re-rating has already priced in resilient sales.
Find out about the key risks to this Vetoquinol narrative.
Another view on Vetoquinol’s value
The P/E work paints Vetoquinol as roughly fairly priced, yet the SWS DCF model points in a different direction. On that view, the shares trade at about a 37.7% discount to an estimated future cash flow value of roughly €141.9 per share. Which story do you lean toward?
Look into how the SWS DCF model arrives at its fair value.
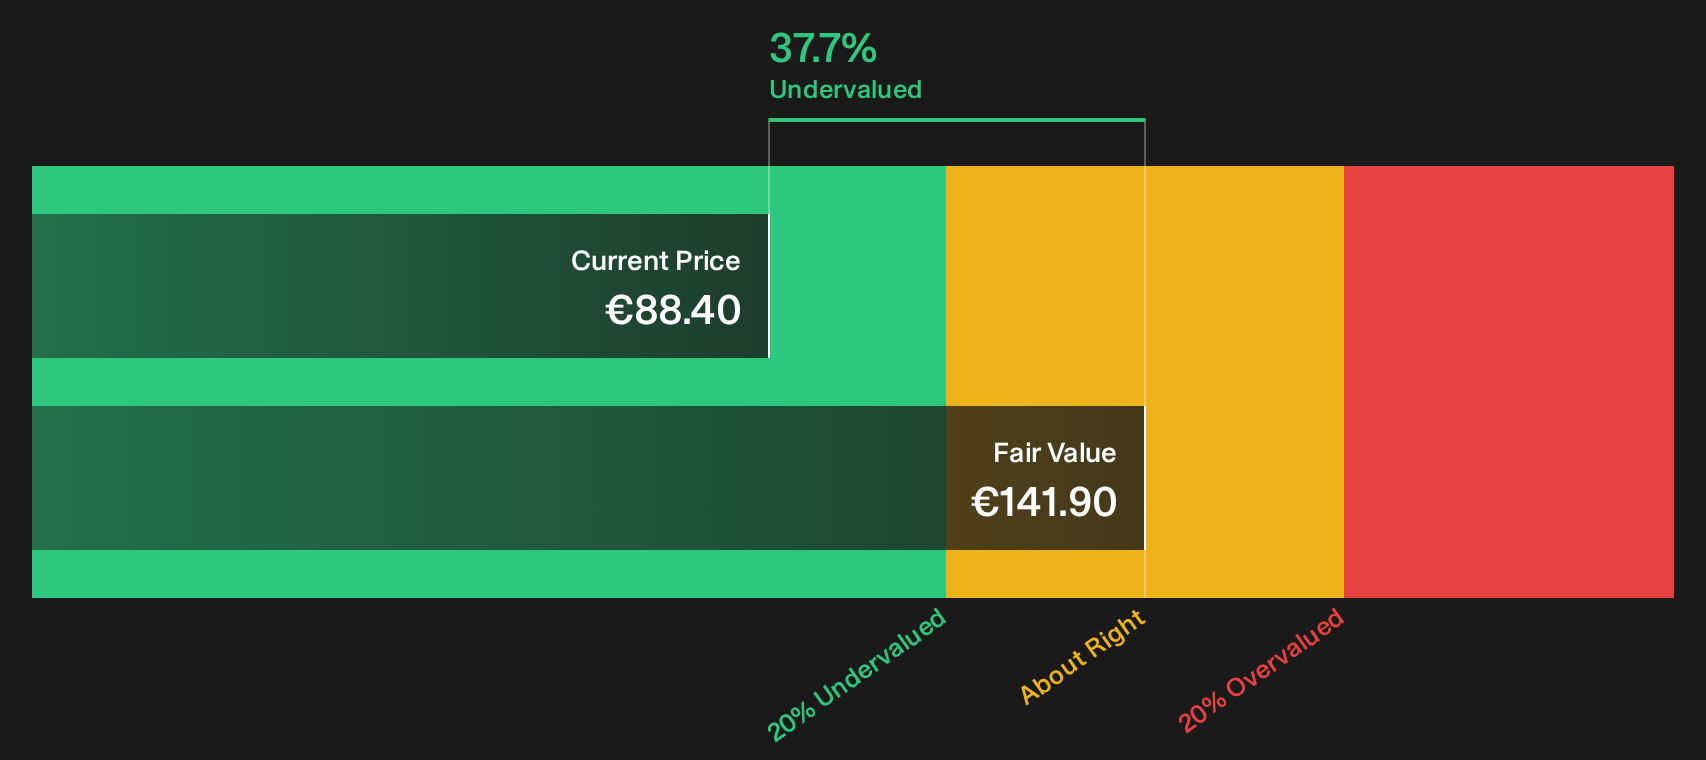
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Vetoquinol for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 214 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Sentiment around Vetoquinol is split, and that is exactly why it pays to pull up the figures yourself, look at both the re rating and the fundamentals, and decide whether the current setup really fits your risk profile. To see the mix of concerns and upside flags that investors are debating, take a closer look at the 3 key rewards and 1 important warning sign
Looking for more investment ideas beyond Vetoquinol?
If Vetoquinol has your attention right now, use this momentum to broaden your watchlist and line up a few more well researched contenders.
- Spot potential turnarounds early by scanning 121 elite penny stocks with strong financials, which already back their low prices with stronger financials than many expect.
- Strengthen your core holdings by reviewing the list of solid balance sheet and fundamentals (194 results), where resilient fundamentals help support staying power through different market moods.
- Get ahead of the crowd by checking the 572 high quality undiscovered gems before more investors start paying attention to their underlying numbers.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com