


- Allegiant Travel reported third quarter 2026 results with revenue of US$961.56 million and a net loss of US$15.18 million, alongside higher passenger traffic and load factors compared with the prior year.
- For the first nine months of 2026, Allegiant Travel moved from a net loss to net income of US$22.44 million while carrying more passengers on a larger network, highlighting how execution on operations and integration is feeding through into reported earnings.
- The focus now turns to how Allegiant Travel's improving profitability, including its move back to year-to-date net income, fits into the existing investment narrative.
Compare Allegiant Travel's earnings rebound and passenger momentum with a curated group of airlines and travel operators by screening for 40 high quality undervalued stocks that share similar operating and balance sheet profiles.
Allegiant Travel Investment Narrative Recap
To stay on board as a shareholder in Allegiant Travel, you need to be comfortable with an airline that leans on tighter schedules, a leisure focused network and a big fleet and integration project. The analyst consensus Narrative on Simply Wall St hinges on Allegiant Travel turning that model, plus the Sun Country combination, into steadier margins. The latest quarter shows higher revenue and passenger volumes alongside a smaller quarterly loss, which supports that recovery story but does not remove execution risk.
The key near term catalyst is clear operational follow through. Investors will likely watch whether higher traffic and improved load factors translate into cleaner profitability as one off items fade. The biggest current risk sits around execution on high capital spending and rising labour costs. If integration synergies and cash generation do not keep pace with the planned aircraft and systems spend, Allegiant Travel could feel more pressure from interest costs and leverage.
The recent earnings release is the announcement that really matters here. Allegiant Travel reported third quarter revenue of US$961.56 million and a net loss of US$15.18 million, with nine month revenue of US$2.64b and net income of US$22.44 million. Those figures frame how well the business is handling higher spending and integration work today.
Passenger data for the third quarter and year to date show more travelers carried on a larger network, along with higher load factors. That combination goes straight to the core catalysts in the analyst consensus Narrative on Simply Wall St, which leans on Allegiant Travel’s peak focused flying model, the shift toward more 737 MAX flying and the Sun Country synergy plan to support future margins if execution remains on track.
Allegiant Travel's current earnings are a reported loss of US$11.1 million, with analyst consensus pointing to earnings of US$674.2 million on forecast revenue of US$5.6b by 2029. That path assumes revenue growth of 24.8% per year and an earnings swing of roughly US$685 million from today’s loss to the 2029 profit target.
Uncover why Allegiant Travel's fair value indicates a 28% potential upside to its current price that could narrow quickly.
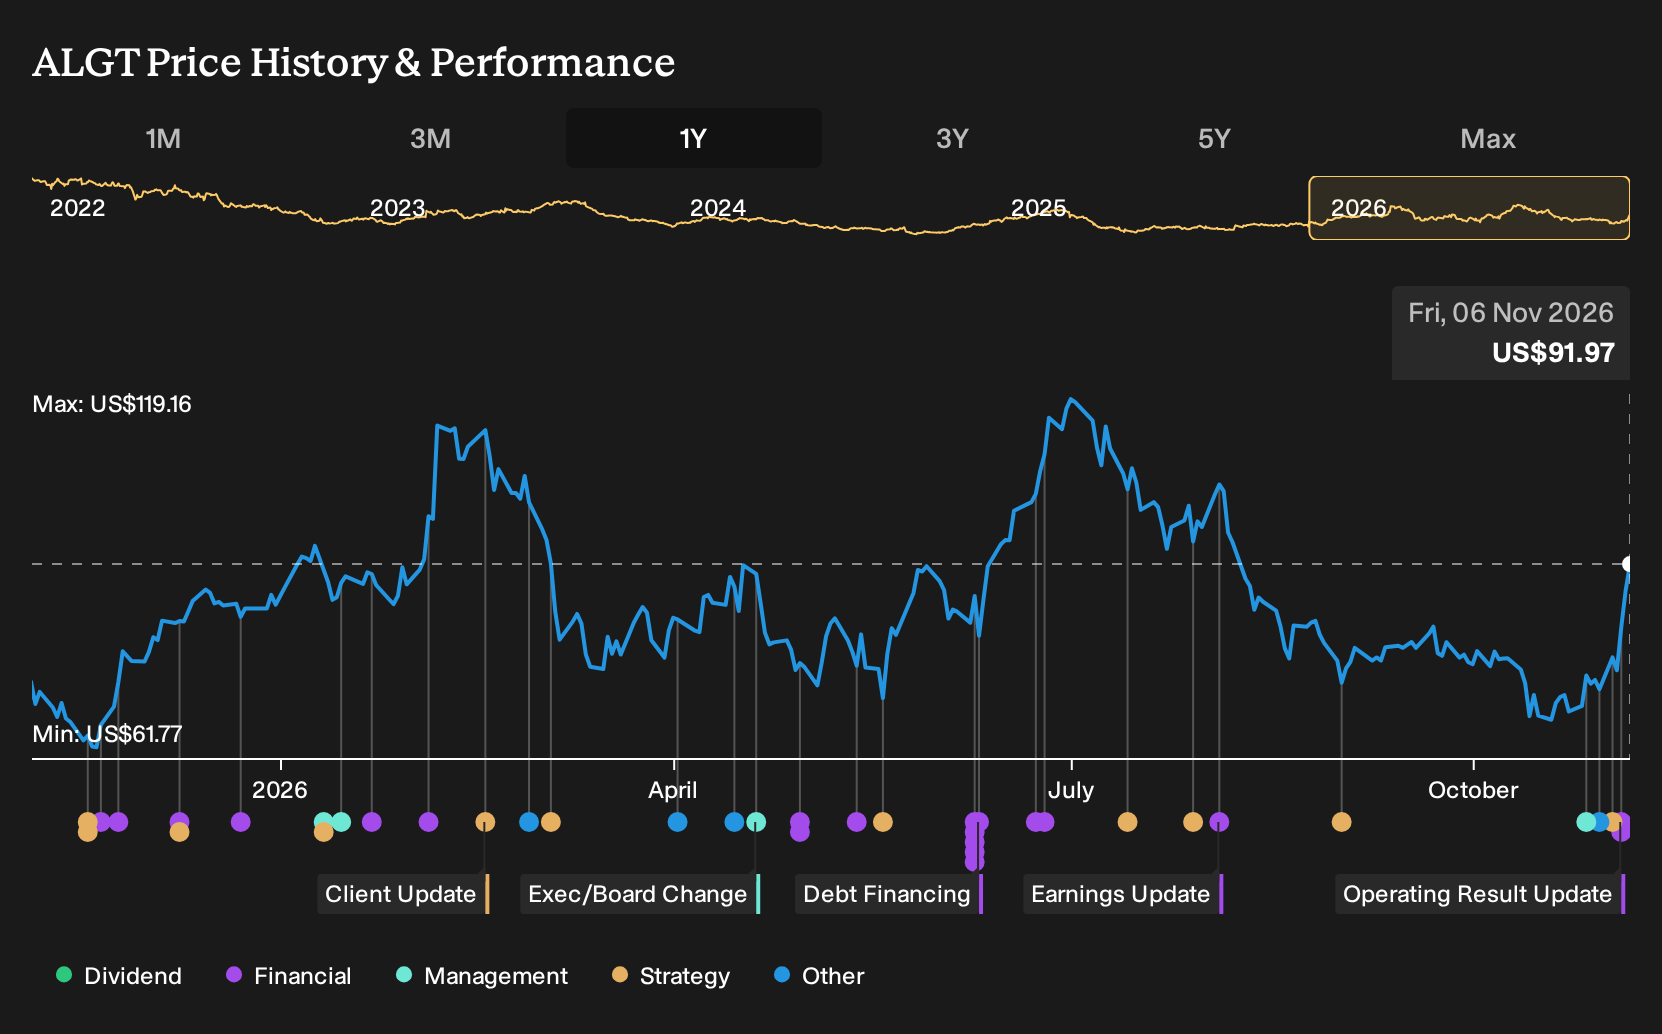
Exploring Other Perspectives
One alternative view puts fuel risk front and center. The most cautious Allegiant Travel analysts were already assuming about 23.0% annual revenue growth to roughly US$5.4b by 2029, with earnings near US$694.8 million, yet still applied a lower 5.6x P/E. That more pessimistic lens might shift again once these latest results are fully digested.
Explore 2 other Allegiant Travel fair value estimates, including one that suggests it could be worth just $117.29!
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Allegiant Travel research is our analysis highlighting 3 key rewards and 4 important warning signs that could impact your investment decision.
- See our latest analysis for Allegiant Travel. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Allegiant Travel's overall financial health at a glance.
Looking For More Investment Ideas Beyond Allegiant Travel?
If this Allegiant Travel update has sharpened your thinking, the next step is to line it up against other opportunities on your watchlist. A tailored screener helps you filter the broader market so you are not just reacting to headlines but instead are comparing Allegiant Travel with businesses that match your preferred mix of quality, valuation and resilience.
- If you want potential income plus resilience, start with companies that combine higher yields with stronger fundamentals using 7 dividend fortresses.
- If capital preservation and steadier profiles matter more to you right now, focus on businesses with sturdier financial risk scores through 31 resilient stocks with low risk scores.
- If you are hunting for mispriced quality, filter for stronger balance sheets and cash generation at valuations that still look restrained by running a search with 40 high quality undervalued stocks.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com