


CVR Energy has seen its share price move sharply in both directions in recent years, which puts fresh attention on a simple question for anyone looking at the stock today. Do the company’s earnings really support where the market is pricing CVR Energy right now, especially after the latest deal news and capital raise?
- Over the past 5 years, CVR Energy has returned 187.1%, which makes the current earnings multiple especially important for judging how much of that story is already priced in.
- The planned US$4.2b acquisition of two Marathon Petroleum refineries may support higher future earnings but also means meaningfully larger capital needs and balance sheet commitments for CVR Energy.
- There is a second opinion on CVR Energy worth weighing. See what analysts think CVR Energy's shares could be worth.
The issue now is whether CVR Energy's present share price is justified by its earnings when set against the Fair Ratio benchmark.
If you are weighing CVR Energy after this deal news and sharp price swings, it can help to compare it with other companies in similar situations using 40 high quality undervalued stocks.
Is CVR Energy Fairly Priced on Earnings?
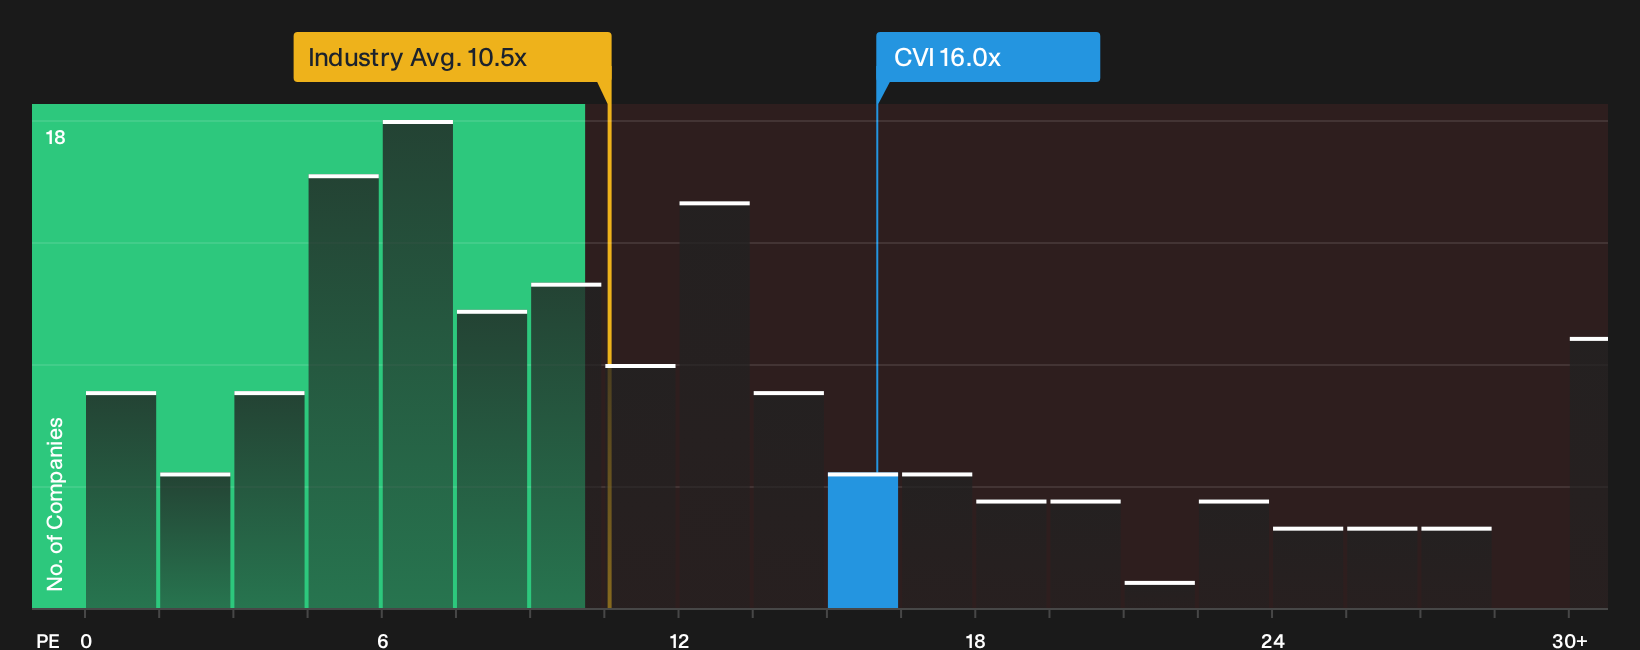
The P/E multiple is a useful lens for CVR Energy because earnings remain the main driver of how investors frame the refinery deal and capital raise. CVR Energy trades on a P/E of 16.0x, which is higher than the Oil and Gas industry average of 10.5x and also above the peer group on 5.2x. Based on the Fair Ratio benchmark, which estimates the earnings multiple you might expect given CVR Energy’s margins, growth profile, size and risk, the current valuation sits modestly above that tailored reference point.
Because the planned US$4.2b refinery acquisition is expected by management to more than double earnings per share, the current premium P/E suggests the market is already assigning meaningful weight to those projections despite the deal still being subject to approvals and funding steps. This means the share price leaves less room for disappointment on execution, integration or refining conditions than a stock trading closer to the sector norm. Explore the numbers behind CVR Energy's P/E valuation.
The CVR Energy Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for CVR Energy pick up where this valuation puzzle leaves off. They spell out what would need to happen to growth, margins and earnings for the stock to be worth materially more or less than today’s price on the Community page. Rather than focusing on a single P/E or model line, each narrative lays out the assumptions sitting behind its view of fair value so you can track those against actual results over time.
Views on CVR Energy split between analysts who see earnings power largely priced in and those who think the stock still has more to give.
Bull case: 21% undervalued
The analyst consensus Narrative on Simply Wall St focuses on how operating quality could underpin more value than the market is allowing for.
"Analysts expect CVR Energy to keep leaning on high utilization in refining and fertilizer, as well as on continued crude slate and logistics optimization, to support earnings quality despite heavy RFS costs…"
Discover why this Narrative puts CVR Energy at 21% undervalued.
Bear case: roughly fairly valued
The bearish analyst Narrative on Simply Wall St stresses how hedging, RFS obligations and capital spending may already cap the upside in CVR Energy.
"Although CVR Energy has repurposed the Wynnewood rail loading facility to reach higher demand regions, the heavy use of NYMEX crack spread swaps with a total notional value of about US$447 million through 2027 creates a situation where future refining revenue is partly capped while realized derivative losses, such as the US$81 million hit in Q2 2026 and the earlier unrealized loss of US$158 million, can still drag on reported earnings and cash flow…"
Explore why this Narrative puts CVR Energy at roughly fairly valued.
Before Moving On CVR Energy, One More Piece Of The Puzzle
Earnings multiples and refinery deals only tell part of the story, because the people steering CVR Energy and how their rewards line up with your interests can matter just as much. See who runs CVR Energy and how they are paid.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com