


ANZ Group Holdings (ASX:ANZ) has just released full year results to 30 September 2026, reporting net income of A$7,270 million and higher earnings per share, alongside a proposed 83 cent partially franked final dividend.
At a share price of A$39.05, ANZ Group Holdings has eased over the past week, with a 7 day share price return of 3.72% and a 1 day move lower of 3.20%. However, the 90 day share price return of 6.66% and 1 year total shareholder return of 7.49% point to momentum that has been building over a longer horizon as investors weigh stronger earnings, the proposed final dividend and recent leadership changes in the treasury function.
Scan how ANZ Group Holdings compares with other bank stocks delivering income and stability by reviewing a curated set of 4 dividend fortresses in one place.
After a strong multi year run and a softer move in the past week, the question for ANZ Group Holdings now is simple. Is most of the upside already behind the stock, or still in front of it as the valuation resets around these latest results?
Most Popular Narrative: 21.3% Overvalued
Against the last close of A$39.05, the most followed narrative on ANZ Group Holdings pegs fair value at about A$32.18, which frames the current price as materially higher than that assessment and sets up a clear valuation tension for investors to weigh.
According to Jamesiskindacool, an investor in the Simply Wall St Community who wrote the narrative, the focus is squarely on what the current earnings and capital position alone might justify for ANZ Group Holdings without layering in extra optimism.
At A$32.162 per share, ANZ (ASX: ANZ) appears reasonably valued based on its current operating performance. Cash earnings per share were 126.1 cents for the six months to 31 March 2026; annualising this figure implies approximately 252 cents per share and a price-to-earnings multiple of around 12.8 times. The most recent 83 cent interim dividend, together with the preceding 83 cent final dividend, represents a trailing cash yield of approximately 5.2% at the assessed price, before considering the partial franking credits.
See why 10 investors see ANZ Group Holdings as 21% overvalued.
Result: Fair Value of A$32.18 (OVERVALUED)
Still, ANZ Group Holdings could see this overvaluation view challenged if loan performance tightens or if the Suncorp Bank integration delivers stronger than expected benefits.
Find out about the key risks to this ANZ Group Holdings narrative.
Another View On ANZ Group Holdings Valuation
While the community narrative sees ANZ Group Holdings as overvalued at A$39.05 versus a fair value of A$32.18, the SWS DCF model points in the opposite direction. On this measure, the shares sit about 5.8% below an estimated future cash flow value of A$41.45, which presents the current level as mildly undervalued instead. This raises a key question: which lens do you place more emphasis on, today’s earnings power or the long run cash flow profile?
For a closer look at how this cash flow based view is built and what assumptions drive it, take a moment to Look into how the SWS DCF model arrives at its fair value.
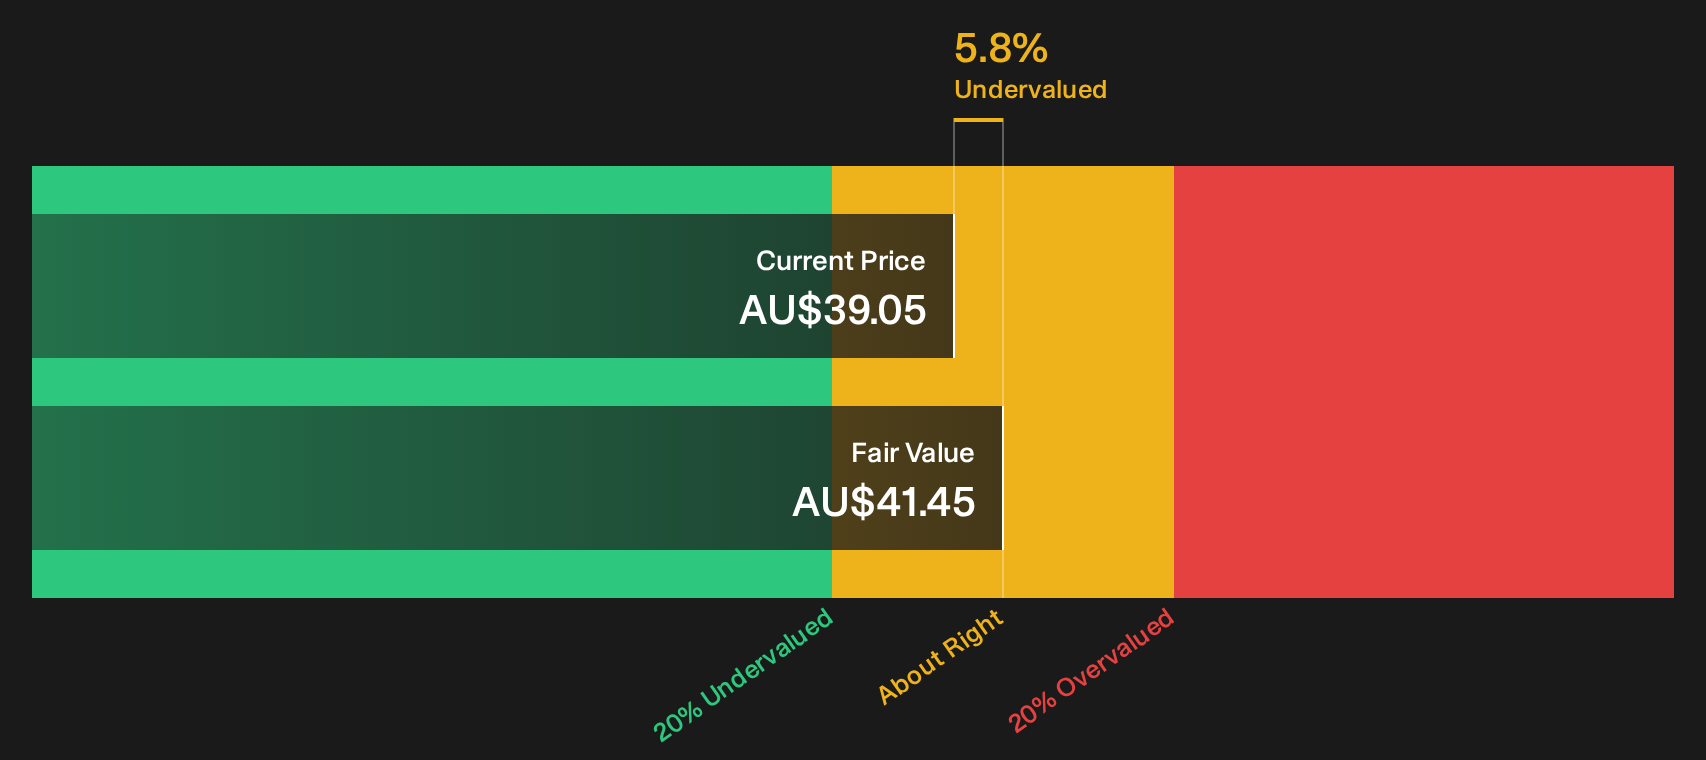
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out ANZ Group Holdings for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 2 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Sentiment on ANZ Group Holdings is clearly mixed, so consider reviewing 3 key rewards and 2 important warning signs to weigh the full picture.
Looking for more investment ideas beyond ANZ Group Holdings?
If ANZ Group Holdings is on the watchlist, now is the moment to broaden the field with a few focused idea lists that could sharpen your next moves.
- Target resilient payers by scanning income focused candidates built around 4 dividend fortresses that combine higher yields with an emphasis on durability.
- Hunt for mispriced quality by working through a curated set of 2 high quality undervalued stocks that pair stronger balance sheets with appealing P/E and cash flow profiles.
- Spot tomorrow's potential leaders early by filtering through 14 high quality undiscovered gems before the crowd starts paying closer attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com