


California Water Service Group earnings and dividend draw fresh investor focus
California Water Service Group (CWT) has just reported third quarter and nine month 2026 results, paired with another quarterly dividend declaration, putting both profitability and income appeal in the spotlight for shareholders.
Recent price action has been supportive, with a 30 day share price return of 11.1% and an 18.8% gain year to date. The 1 year total shareholder return of 14% contrasts with a 5 year total shareholder return that is still down 10.5%. This suggests momentum has picked up only more recently, as California Water Service Group’s latest earnings and long running dividend record refocus attention on the stock’s risk and income profile.
Compare California Water Service Group’s renewed momentum and long dividend history with a curated 7 dividend fortresses that share similar income resilience and recent share price strength.
After California Water Service Group’s recent climb and fresh dividend confirmation, the real tension is simple: Is it worth accepting today’s price, or does patience for a cleaner entry make more sense once valuation is on the table?
Most Popular Narrative: 5% Undervalued
On the analyst consensus Narrative on Simply Wall St, California Water Service Group’s fair value of $53.75 sits modestly above the latest $51.04 close. This puts the current move into context and sets up the core thesis behind that view.
The current valuation suggests the share price does not fully reflect the company’s reported 10 year growth in capital and rate base, the visibility on approved California investment and rate mechanisms through 2028, or the additional earnings potential from PFAS cost recovery and new wastewater and recycled water operations.
See why 5 investors see California Water Service Group as 5% undervalued.
Result: Fair Value of $53.75 (UNDERVALUED)
Still, California Water Service Group’s story can break if regulators push back on recovering heavy capital and PFAS costs, or if new state expansions earn weaker returns than expected.
Find out about the key risks to this California Water Service Group narrative.
Another View: California Water Service Group on earnings multiples
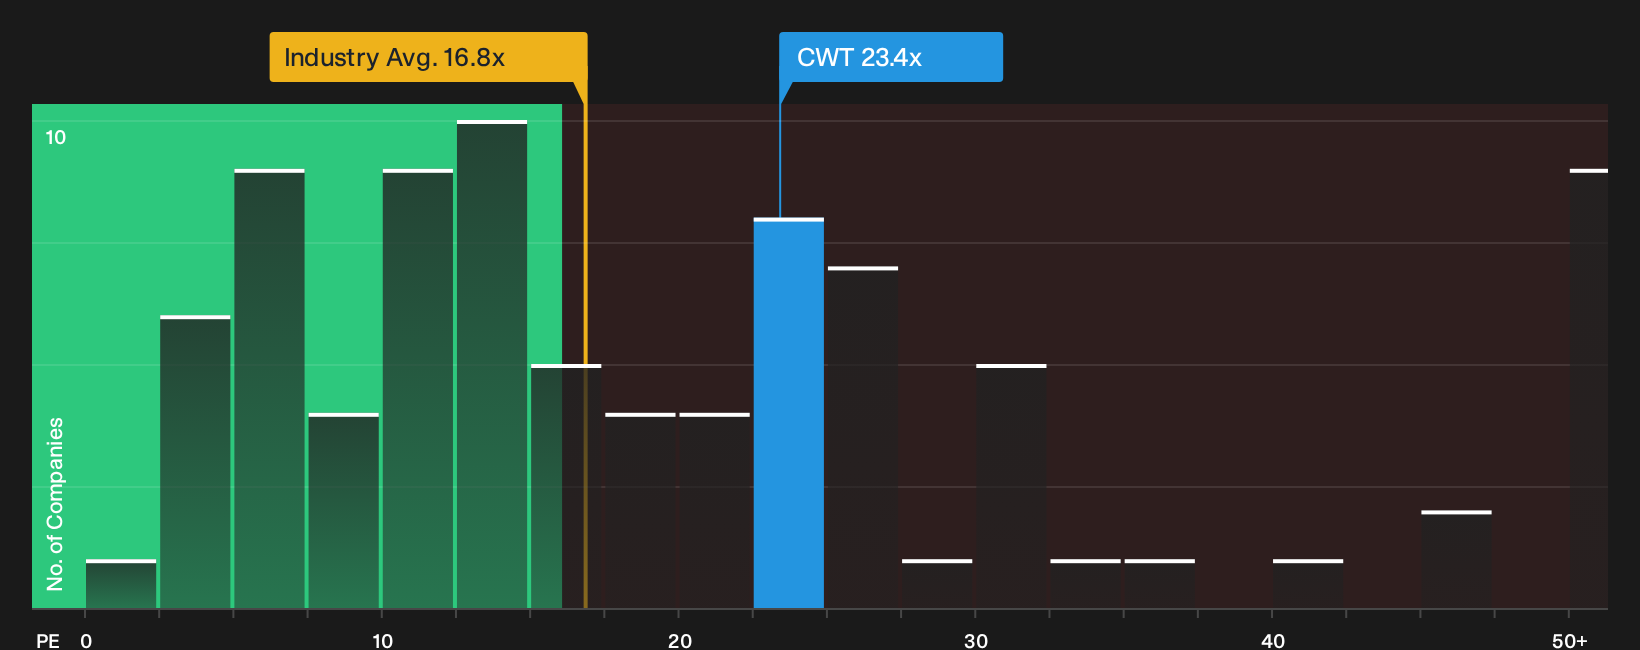
On a simple earnings multiple, California Water Service Group looks less generous than the analyst fair value implies. The stock trades on a P/E of 23.4x, above the Global Water Utilities average of 16.8x and above its own fair ratio of 19.1x, which points to limited margin for error if growth or regulation disappoint.
That richer P/E versus both the sector and the fair ratio means investors are already paying a premium for California Water Service Group’s profile. The question is whether you are comfortable paying up for that quality, or whether you would rather wait for the market to move closer to the fair ratio before building exposure.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on California Water Service Group’s value and risk profile can be confusing. Act promptly, examine the numbers independently, and pressure test both the upside and the downside using the 2 key rewards and 3 important warning signs.
Looking for more California Water Service Group style investment ideas?
If California Water Service Group has sharpened your focus on quality and price today, do not stop here. Broaden your watchlist now so you are not reacting late when the next opportunity appears.
- Target value first and scan a curated set of companies that combine quality fundamentals with attractive entry points using the 40 high quality undervalued stocks.
- Strengthen your defense and focus on businesses with resilient balance sheets and solid financial footing through the list of solid balance sheet and fundamentals (25 results).
- Spot fresh potential early and review a hand picked group of strong fundamentals that the market has not widely focused on yet via the 19 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com