


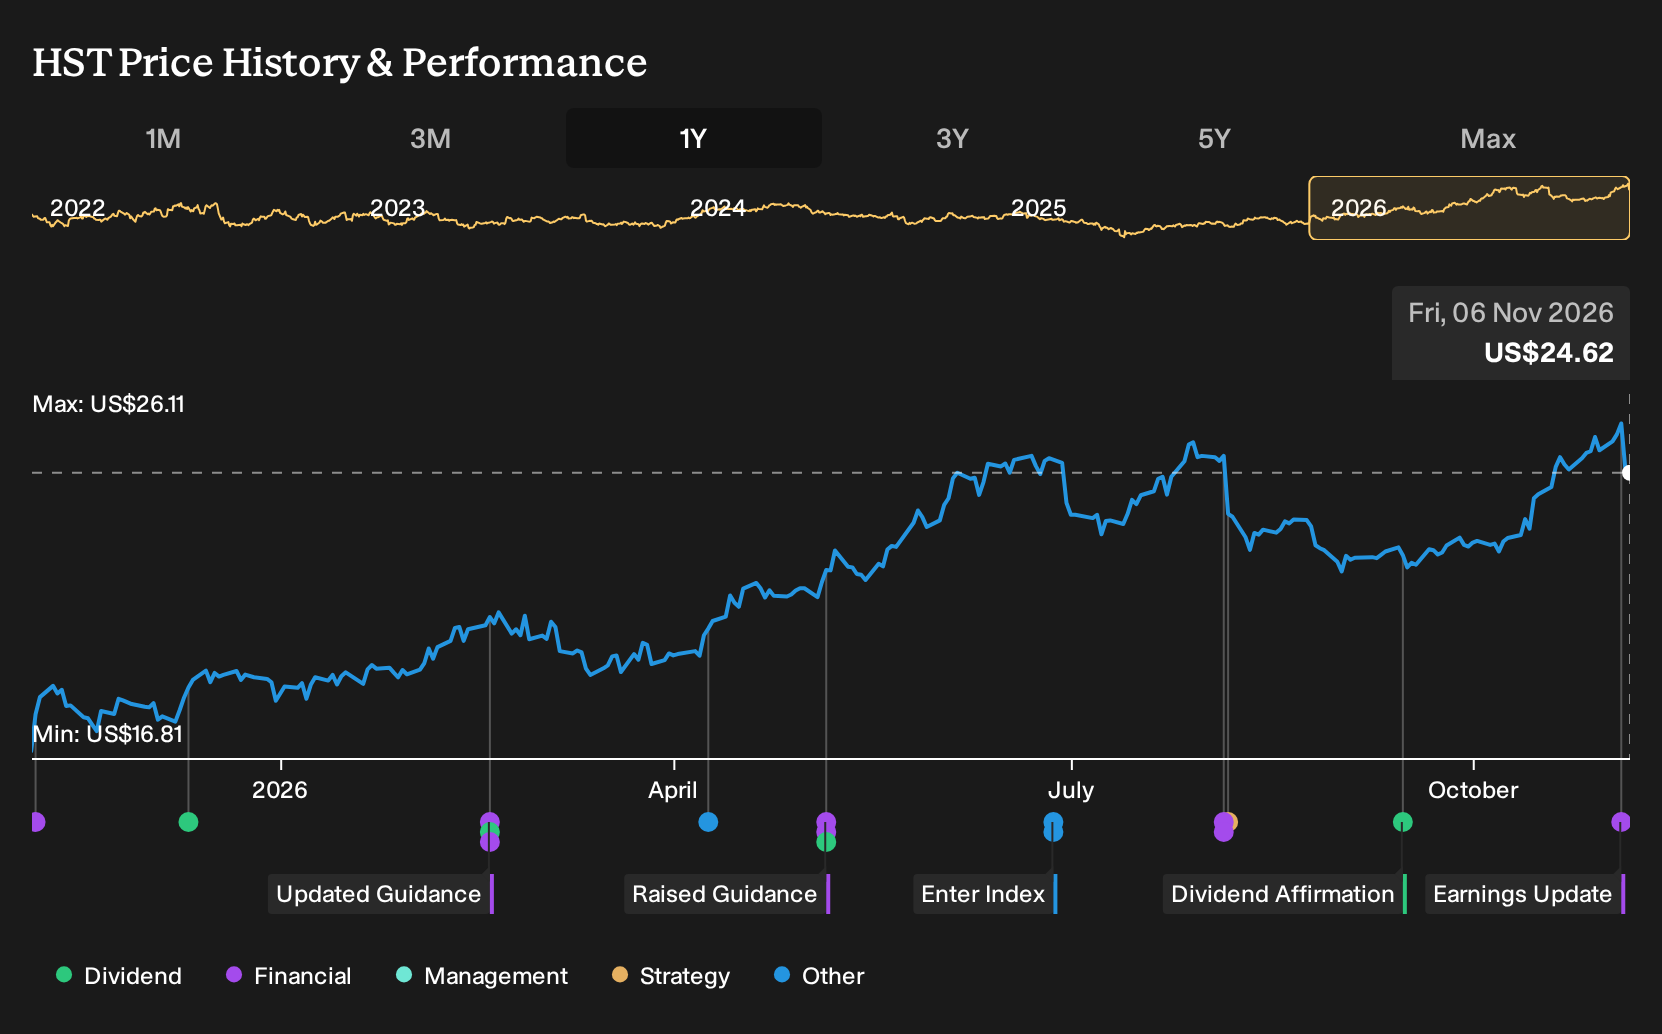
If you had bought Host Hotels & Resorts on 6 November 2025 and simply held on, the result would probably have felt very different from the noisy debate that surrounded it at the time. For Host Hotels & Resorts shareholders, the return over the past year was 46.2%, including dividends. With bulls pointing to experiential travel and premium upgrades, and bears fixated on wage inflation and climate exposure, which of those trade offs would you have leaned into back then?
Host Hotels & Resorts has already moved. See which of 40 high quality undervalued stocks still trade below our estimates.
The Argument You Would Have Been Weighing On Host Hotels & Resorts
The shares cost US$17.31 at the start of the period, and Host Hotels & Resorts sat between two very different stories about where value might sit next.
On the optimistic side, analysts saw a Fair Value of US$18.56. This was effectively the price implied if their model played out, built on 2.0% annual revenue growth and an 11.2% profit margin assumption three years out.
The cautious view pointed to a Fair Value of US$15.77. This reflected concerns that a 6% rise in wages and external shocks from hurricanes could squeeze earnings and keep the stock under pressure.
What The Host Hotels & Resorts Results Put To The Test
Host Hotels & Resorts spent the period backing the upbeat case with hard news. Q1 and Q2 2026 results both beat internal expectations, came with raised full year RevPAR guidance, and were supported by special dividends funded from asset sales. Against that, Q3 2026 told a tougher story as revenue edged up to US$1.347b while net income slipped to US$70m and net margin dropped to 5.2%. Overall, the evidence cut both ways.
The real hinge here was profitability resilience. When you test a thesis like this elsewhere, track whether revenue, absolute earnings, and net margin all move in line with the original story instead of assuming top line alone answers the question.
What Host Hotels & Resorts' Run Now Asks Of You
Today Host Hotels & Resorts trades at US$24.62, with the bearish analyst Narrative on Simply Wall St holding a Fair Value that sits below that quote and framing the gap as richer expectations rather than a broken business.
The Narrative hangs on resort demand and ancillary spending carrying EBITDA and RevPAR against steady wage and capex pressure. Anyone paying today's price is effectively assuming that high end leisure revenue holds up, so how do ongoing cost inflation and weather related capex risk that assumption according to this view?
"The main factor that needs to support performance is that high end leisure demand and ancillary revenue growth at renovated resort and luxury properties continue to support RevPAR and EBITDA against ongoing capex and wage cost headwinds. This can pressure free cash flow and keep net margins under strain if uplift from these properties does not arrive quickly enough."
Not everyone reads the same price the same way. → See the lower figure this Narrative lands on, and how it gets there
Go Straight To The Source
You may be late to this rally, but that does not have to mean arriving late to every opportunity. Start with companies whose prices leave room for a different view of their future. Here are three trading below our estimates.
- Company 1 - 41% below our estimate - turns shorter brownfield tieback timelines into higher margin subsea equipment and services orders.
- Company 2 - 40% below our estimate - captures AI related airfreight and complex customs work into its forwarding and brokerage network.
- Company 3 - 18% below our estimate - supplies high bandwidth memory and storage that relieve capacity bottlenecks in AI data centers.
Those are three of them. See all 25 companies with the balance sheet to back it up →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com