


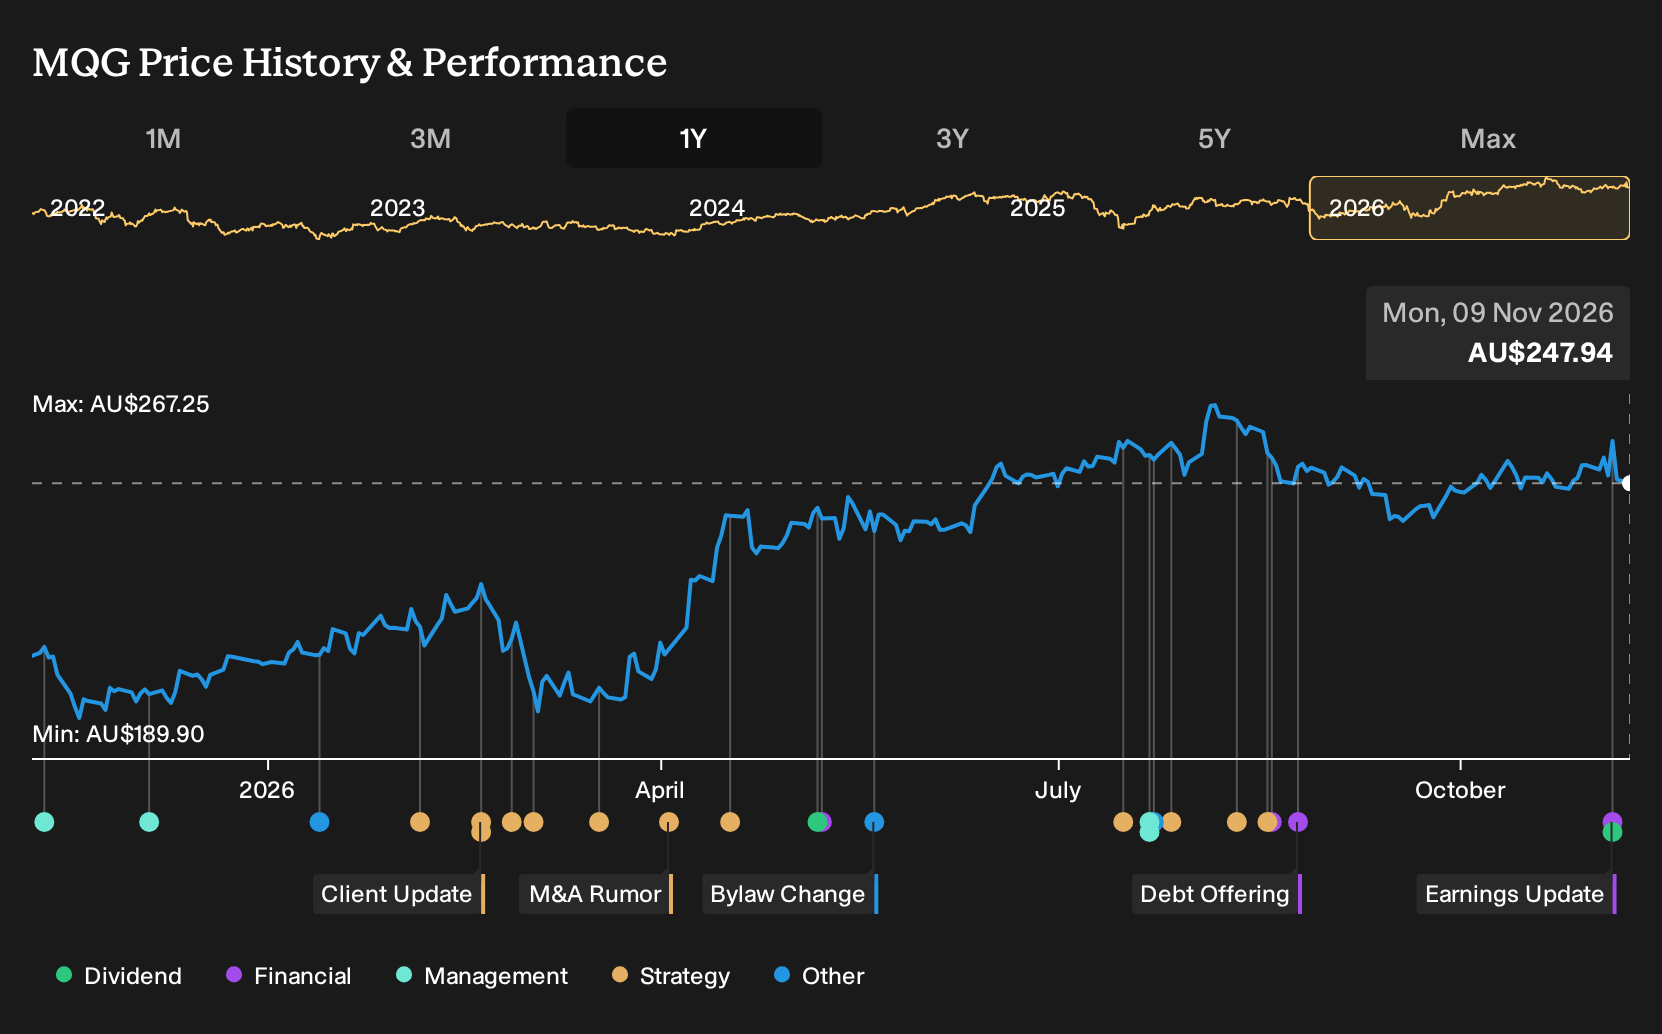
- Macquarie Group reported half year net income of A$2,478 million and basic earnings per share of A$6.519 for the period to 30 September 2026, alongside an ordinary distribution of A$3.25 per security payable on 17 December 2026.
- The combination of higher net interest income and earnings with a larger ordinary distribution illustrates how Macquarie Group is balancing capital returns with the demands of its diversified global operations.
- Attention now turns to how this half year profit and higher ordinary distribution might influence the existing investment narrative for Macquarie Group.
Scan how Macquarie Group's latest half year earnings and higher ordinary distribution compare with other income focused opportunities by reviewing our hand picked 4 dividend fortresses.
Macquarie Group Investment Narrative Recap
To hold Macquarie Group, an investor needs to be comfortable with a global financial platform that blends relatively steady banking and asset management income with more variable trading, commodities and capital markets activity. According to Jamesiskindacool, an investor in the Simply Wall St Community, that mix underpins the current valuation. The latest half year result, with higher net interest income and earnings, supports that framework but does not overhaul it.
The key short term catalyst is whether recent earnings momentum can be sustained as conditions shift across commodities, capital markets and credit. The biggest current risk remains balance sheet quality and funding, given the low 59% allowance for bad loans and the higher reliance on external borrowing. The half year result adds useful detail on performance, but it does not remove those underlying sensitivities.
The ordinary distribution of A$3.25 per security for the six months to 30 September 2026 is the most relevant announcement here. Macquarie Group is continuing to return cash while reporting net income of A$2,478 million and basic EPS of A$6.519 for the period. That pairing keeps income and capital return firmly in focus for shareholders who monitor payout consistency.
For catalysts, this distribution level interacts directly with the existing payout framework that Jamesiskindacool described, where prior dividends sat within a 50% to 70% earnings range. Income focused holders will likely watch how sustainable this payment proves if earnings growth slows from recent rates. At the same time, risk focused investors may pay closer attention to loan loss coverage, funding mix and any signs that more volatile businesses like Commodities and Global Markets are affecting the capacity to keep distributions at similar levels.
On Jamesiskindacool’s numbers, the A$219.39 fair value reflects a view that Macquarie Group can sustain 6.0% annual revenue growth and reach a future profit margin of 23.9%. Together, these assumptions support the current P/E level without relying on additional upside from new business initiatives.
Uncover how Macquarie Group's fair value indicates a 12% potential downside to its current price, a premium that may not hold.
Exploring Other Perspectives
Five fair value estimates from the Simply Wall St Community cluster between about A$189 and A$263, so some retail investors see Macquarie Group as close to fully priced while others pencil in much richer upside. These opinions pre date the latest earnings and higher ordinary distribution. You can compare them with fresh results before forming a view.
Explore 4 other Macquarie Group fair value estimates, including one that suggests as much as 24% downside from the current price!
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Macquarie Group research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Macquarie Group. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Macquarie Group's overall financial health at a glance.
Looking For More Investment Ideas Beyond Macquarie Group?
If Macquarie Group has sharpened your focus on income, value and balance sheet strength, it can be useful to line it up against other listed businesses that share some of those traits but operate in very different corners of the market.
- For investors who want potential mispricing on their side, compare Macquarie Group with a curated pool of companies trading below estimated worth using our 2 high quality undervalued stocks.
- If capital preservation sits high on your list, scan a 6 resilient stocks with low risk scores to see which businesses pair steadier risk profiles with more resilient fundamentals.
- When you want quality that is less crowded, broaden your watchlist with a hand picked set of 14 high quality undiscovered gems that many investors may not yet be tracking closely.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com