


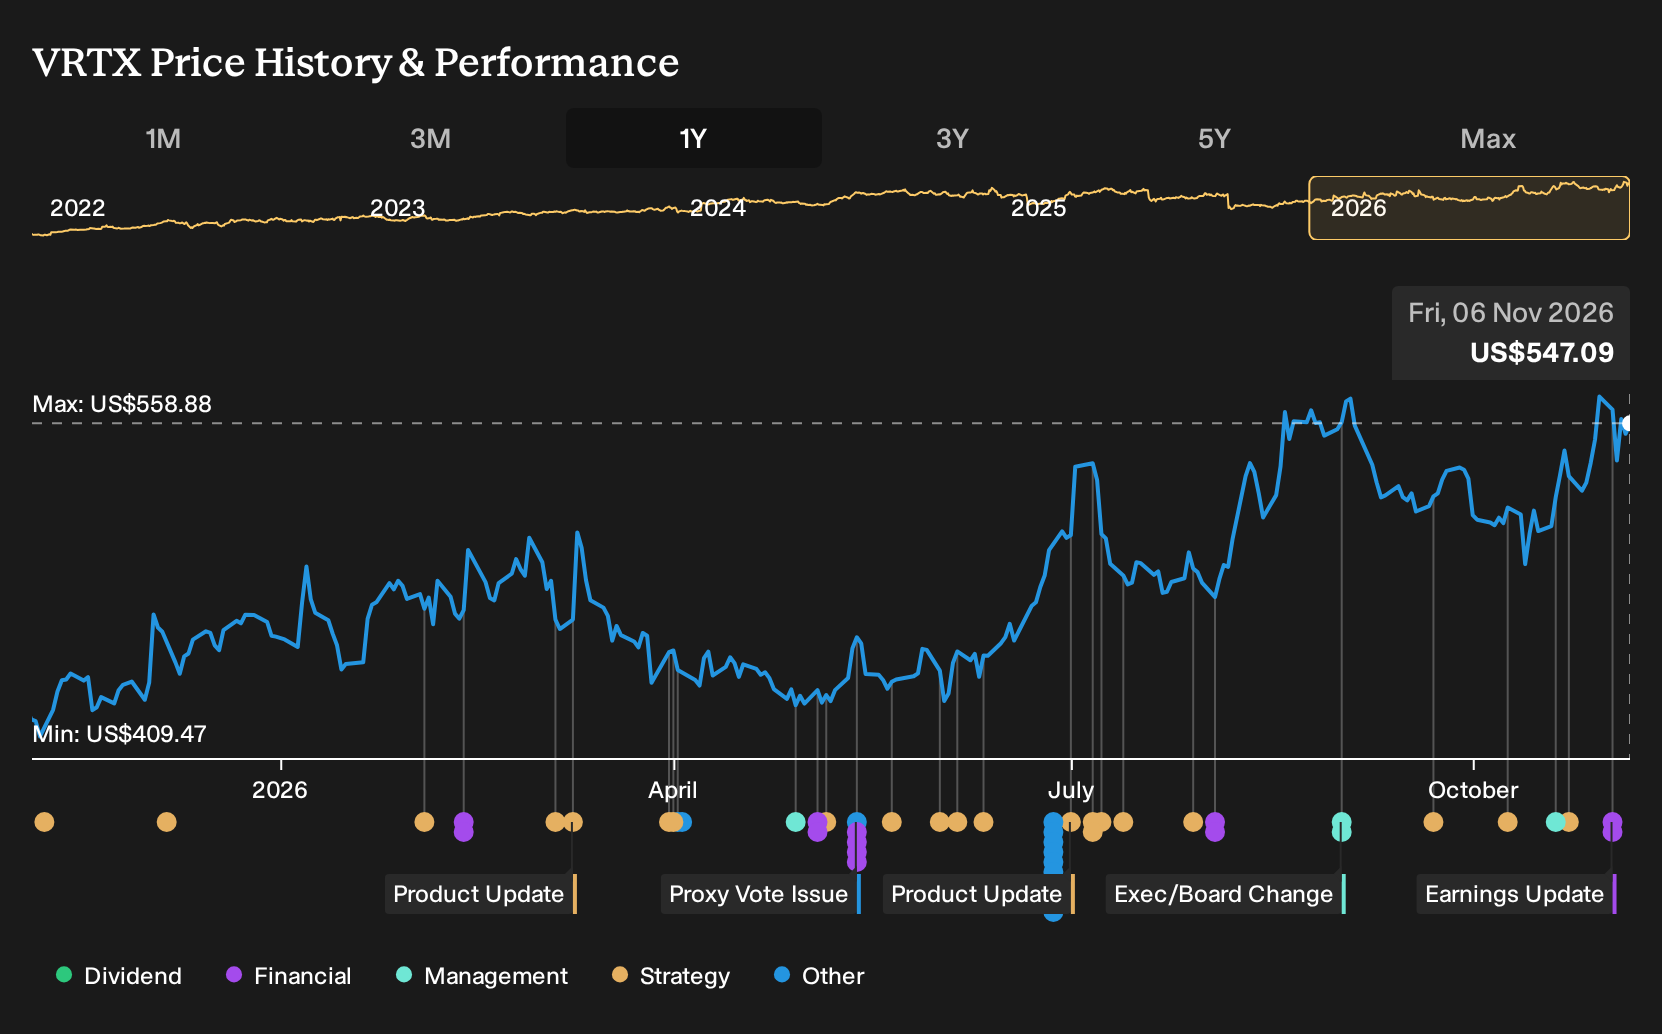
- Vertex Pharmaceuticals reported third quarter 2026 revenue of US$3,440.8m and net income of US$653.6m, and nudged full year revenue guidance to a range of US$13.15b to US$13.25b, including contributions from CASGEVY, JOURNAVX and PALSONIFY.
- The earnings report showed higher sales but lower quarterly net income year on year, which puts the spotlight on how Vertex Pharmaceuticals is balancing investment in new franchises against profitability from its cystic fibrosis base.
- We will now look at how Vertex Pharmaceuticals' raised 2026 revenue guidance could reshape the existing investment narrative around its diversification.
Scan beyond Vertex Pharmaceuticals and see how other healthcare leaders with strong product pipelines stack up in our hand picked 35 healthcare AI stocks for potential next wave beneficiaries.
Vertex Pharmaceuticals Investment Narrative Recap
To be comfortable as a Vertex Pharmaceuticals shareholder, you need to believe the cystic fibrosis powerhouse can steadily turn today’s R&D and deal spending into tomorrow’s diversified franchises. The latest quarter fits that picture. Revenue for the period and the nine months to September 30, 2026 rose year on year, while net income for the quarter tightened as newer launches absorbed spending.
The short term swing factor remains how quickly non CF therapies like CASGEVY, JOURNAVX and PALSONIFY scale against that heavier cost base. The biggest risk is still concentration in high margin CF drugs, where any pricing or volume pressure would bite faster now that reported quarterly profit is more sensitive to launch and integration costs.
The raised 2026 revenue guidance looks most relevant here. Vertex Pharmaceuticals now expects US$13.15b to US$13.25b in full year revenue, with at least US$500m combined from CASGEVY and JOURNAVX and US$40m to US$50m from PALSONIFY, plus a foreign exchange tailwind. That reinforces the analyst consensus Narrative on Simply Wall St that non CF pillars are becoming more meaningful to the income statement.
Execution risk has not gone away. The Crinetics deal still brings integration work, higher funding needs and pressure to deliver on PALSONIFY and atumelnant scale up, while any squeeze on CF pricing or tender renewals could offset the newer contributions. For you as an investor, the key watchpoints are uptake trends in these fresh launches and whether operating margins stabilise as 2026 plays out.
Vertex Pharmaceuticals' current earnings are $4.0b, with analysts projecting earnings of $6.5b by 2029 and forecasting revenues of $18.0b in the same year. This setup assumes 11.5% yearly revenue growth and an earnings increase of about 63% from today to reach that $6.5b forecast.
Uncover why Vertex Pharmaceuticals' fair value indicates an 8% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
One alternate view leans hard into Vertex Pharmaceuticals’ kidney and endocrinology pipeline as the real swing factor. The most optimistic analysts were modeling about US$19.6b of revenue and US$8.6b of earnings by 2029, versus the consensus US$18.0b and US$6.5b, even before this guidance hike. That gap shows how far opinions can stretch. Use this quarter’s results to test which story you find more convincing.
Explore 3 other Vertex Pharmaceuticals fair value estimates, including one that suggests there could be as much as 64% upside from the current price!
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider conducting your own research.
- A great starting point for your Vertex Pharmaceuticals research is our analysis highlighting 3 key rewards that could impact your investment decision.
- See our latest analysis for Vertex Pharmaceuticals. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Vertex Pharmaceuticals' overall financial health at a glance.
Looking For More Ideas Beyond Vertex Pharmaceuticals?
If this quarter has sharpened your view on Vertex Pharmaceuticals but you still want a broader watchlist, use the Simply Wall St Screener to surface other companies that fit your style rather than just your news feed.
- If you are hunting for quality at a discount, start with companies flagged as having a margin of safety by checking the 40 high quality undervalued stocks in the screener.
- If capital preservation and steadier profiles matter more to you than headline excitement, narrow your search to the 31 resilient stocks with low risk scores and see which businesses line up with that mindset.
- If robust finances are non negotiable for you, filter for stocks with strong balance sheets and consistent fundamentals using the list of solid balance sheet and fundamentals (25 results) within the tool.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com