


Avolon’s record purchase of 140 Boeing 737-10 jets put Boeing (BA) back in focus for investors, as the order underscores lessor demand for larger single-aisle aircraft and for the broader 737 MAX family.
For investors, the Avolon deal lands against a mixed backdrop. Boeing’s 1 day share price return of 0.52% offers only a brief pause in a trend that has seen the stock fall 8.91% over 30 days and 25.66% over 90 days, while the 1 year total shareholder return is down 10.99% and the 5 year total shareholder return has declined 25.61%. This suggests that recent contract wins, order book strength and a reduced quarterly loss are being weighed against production setbacks, workforce cuts and ongoing operational and labor challenges, so recent momentum still looks weak despite improving headlines.
Scan how Boeing’s order momentum compares with peers by reviewing a hand-picked set of aerospace and industrial stocks in the 40 high quality undervalued stocks.
Boeing’s backlog keeps growing while the share price has slid over recent months. Does it make more sense to lean into that gap now or wait for a cleaner entry after the dust settles around execution and labor issues?
Most Popular Narrative: 8% Overvalued
Boeing closed at $173.40, while the most followed narrative on Simply Wall St sets fair value at $160.01 using a 10% discount rate, so the stock screens as slightly expensive on that lens according to rcb9, an investor in the Simply Wall St Community who built a detailed cash flow view.
The operating recovery is real but incomplete. Commercial Airplanes narrowed its operating margin from negative 5.1% to negative 2.7% on 171 deliveries against 150. The 737 is transitioning to 47 per month from 38 a year ago, with a fourth Everett line activated in July, and management targets 52 next year. The FAA certified the MAX 7 today after nearly a decade, with roughly 30 airframes in storage ready for retrofit.
See why 11 investors see Boeing as 8% overvalued.
The narrative uses 8% annual revenue growth, an 8% net margin and a 23x P/E in 2031, then discounts those earnings back at 10%. That mix leans on Boeing’s commercial backlog, an eventual end to large program charges and a gradual reduction in interest costs as the $45.9b debt load is repaid.
At today’s share count and that set of assumptions, rcb9 lands on fair value of $160.01 and labels the current quote as already baking in most of the recovery. The same framework flags clear break points for readers to watch, including any large new program write offs or a failure to bring Commercial Airplanes into sustained profitability.
Result: Fair Value of $160.01 (OVERVALUED)
Still, Boeing’s story can be knocked off course if fresh multi billion dollar program charges emerge or if Commercial Airplanes remains loss making for longer than expected.
Find out about the key risks to this Boeing narrative.
Another View: Boeing Through The Market’s Lens
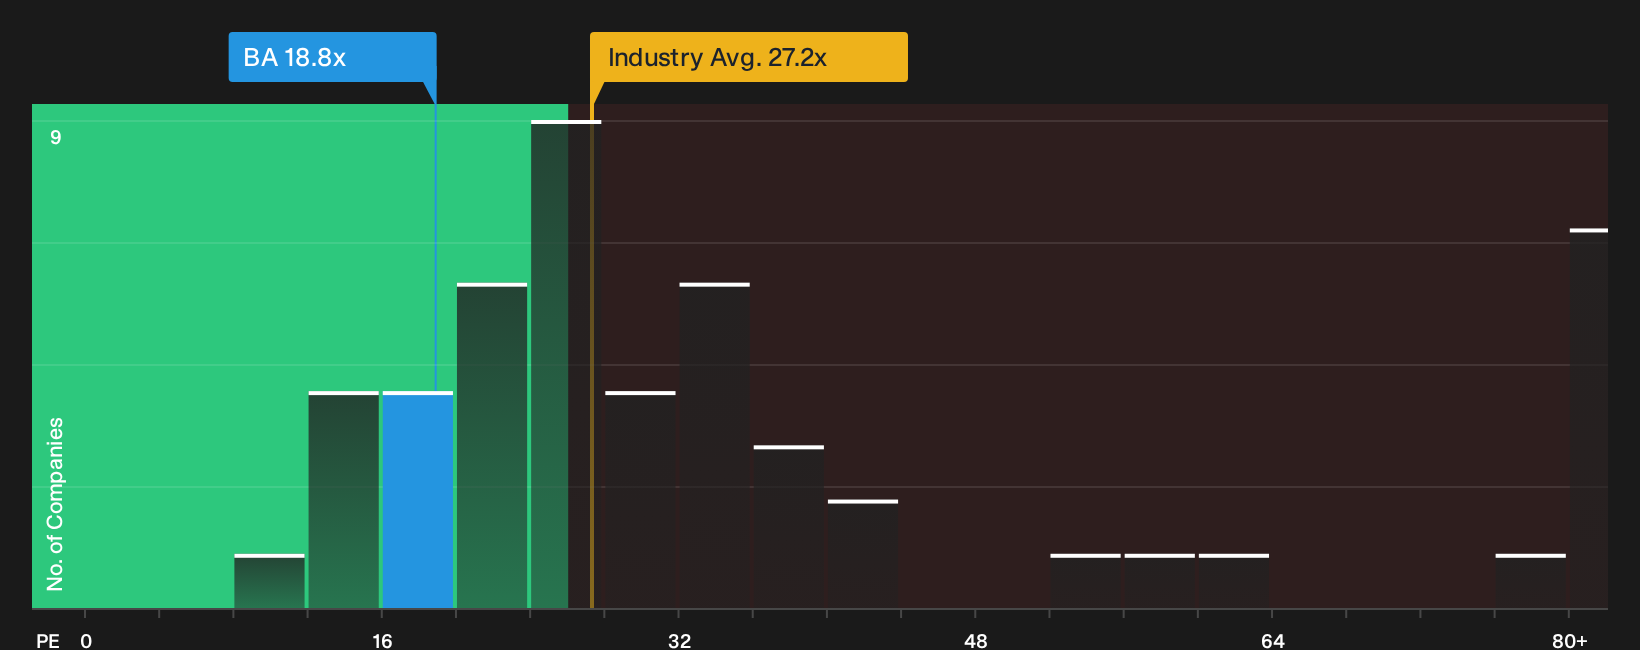
The community narrative argues Boeing is about 8% overvalued at $173.40 based on a cash flow forecast. The market’s own yardstick tells a very different story. Boeing trades on a P/E of 18.8x versus 27.7x for peers, an industry average of 27.2x and a fair ratio estimate of 40.7x.
That gap points to investors pricing in more execution risk than the sector and even more caution than the fair ratio suggests the market could move toward. The question for you is whether that discount reflects real balance sheet and program risk, or an opening created by recent underperformance.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If this mix of caution and optimism around Boeing leaves you uncertain, consider reviewing the numbers promptly and comparing them with your own expectations. Start by weighing the 5 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Boeing?
Once you have a view on Boeing, broaden your watchlist quickly so you are not relying on a single recovery story to carry your portfolio.
- Hunt for potential turnaround stories with sharper risk and reward trade offs by scanning the 10 elite penny stocks with strong financials.
- Zero in on quality businesses that trade below their implied worth using the 19 high quality undiscovered gems.
- Prioritise resilience and focus on managing volatility by using the 31 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com