


- Spirax Group has recently reported strong traction in its decarbonization and energy optimization offerings, with electrification projects and thermal energy assessments helping to support a recurring revenue model and underpin dividend payments.
- The early opening of what management describes as a multibillion pound addressable market for steam and thermal efficiency solutions gives Spirax Group a larger runway to sell higher margin, service heavy packages rather than just equipment.
- We now examine how Spirax Group's investment narrative is shaped by rising decarbonization demand and momentum in thermal energy assessments.
Scan beyond Spirax Group and compare its decarbonization momentum with a hand picked 42 power grid technology and infrastructure stocks that benefits from the same global push to use energy more efficiently.
Spirax Group Investment Narrative Recap
To own Spirax Group, you need to buy into a fairly simple idea. Industrial customers are looking to cut carbon and energy use, and Spirax Group wants to sell complete thermal efficiency solutions into that shift, not just hardware. The recent decarbonization orders and energy optimization traction support that thesis rather than change it. The key short term catalyst remains execution in Steam Thermal Solutions, especially turning assessments into ongoing service contracts.
The biggest near term risk has not moved either. Cash conversion dropped to 54% in the first half of 2026 and net debt of £618m with leverage at 1.6x EBITDA leaves less room for error. If working capital stays elevated or industrial production in core markets remains sluggish, pressure on financial flexibility and dividend cover could build even with healthy demand for decarbonization projects.
The analyst consensus narrative on Simply Wall St highlights a £7b annual addressable market for decarbonization and energy optimization that is only starting to open. Recent Powering Zero orders and cross thermal energy assessments sit in the middle of that opportunity. They provide tangible activity behind the idea of multi year revenue from electrification projects and service rich packages, rather than a purely theoretical green growth story.
These same orders also link directly to the other listed catalysts. Connected steam traps, the pivot toward MRO and solutions in Asia and the ongoing restructuring savings all rely on Spirax Group converting interest in energy efficiency into long lived relationships. Execution risk is real, especially with weaker industrial conditions in places such as Germany and the USA, but early wins in thermal energy assessments illustrate how the group is aiming to build higher margin, recurring cash flows to support operations and dividends.
What The Current Spirax Group Forecasts Assume
Spirax Group's current analyst narrative links the decarbonization story directly to a concrete 2029 earnings and revenue profile, rather than leaving it as a loose theme. Consensus forecasts point to revenues of £2.0b and earnings of £285.2m by 2029, based on an assumed 5.3% annual increase in sales and a move from 11.4% profit margins today to 14.0% over roughly three years.
On those numbers, earnings would rise by £87.0m from £198.2m today to the £285.2m level analysts are using in their models. The same framework also assumes only a small shift in valuation multiples, with a P/E of 27.5x on the 2029 earnings figure compared with 27.6x today, and a slight uplift in the share count of 0.07% per year.
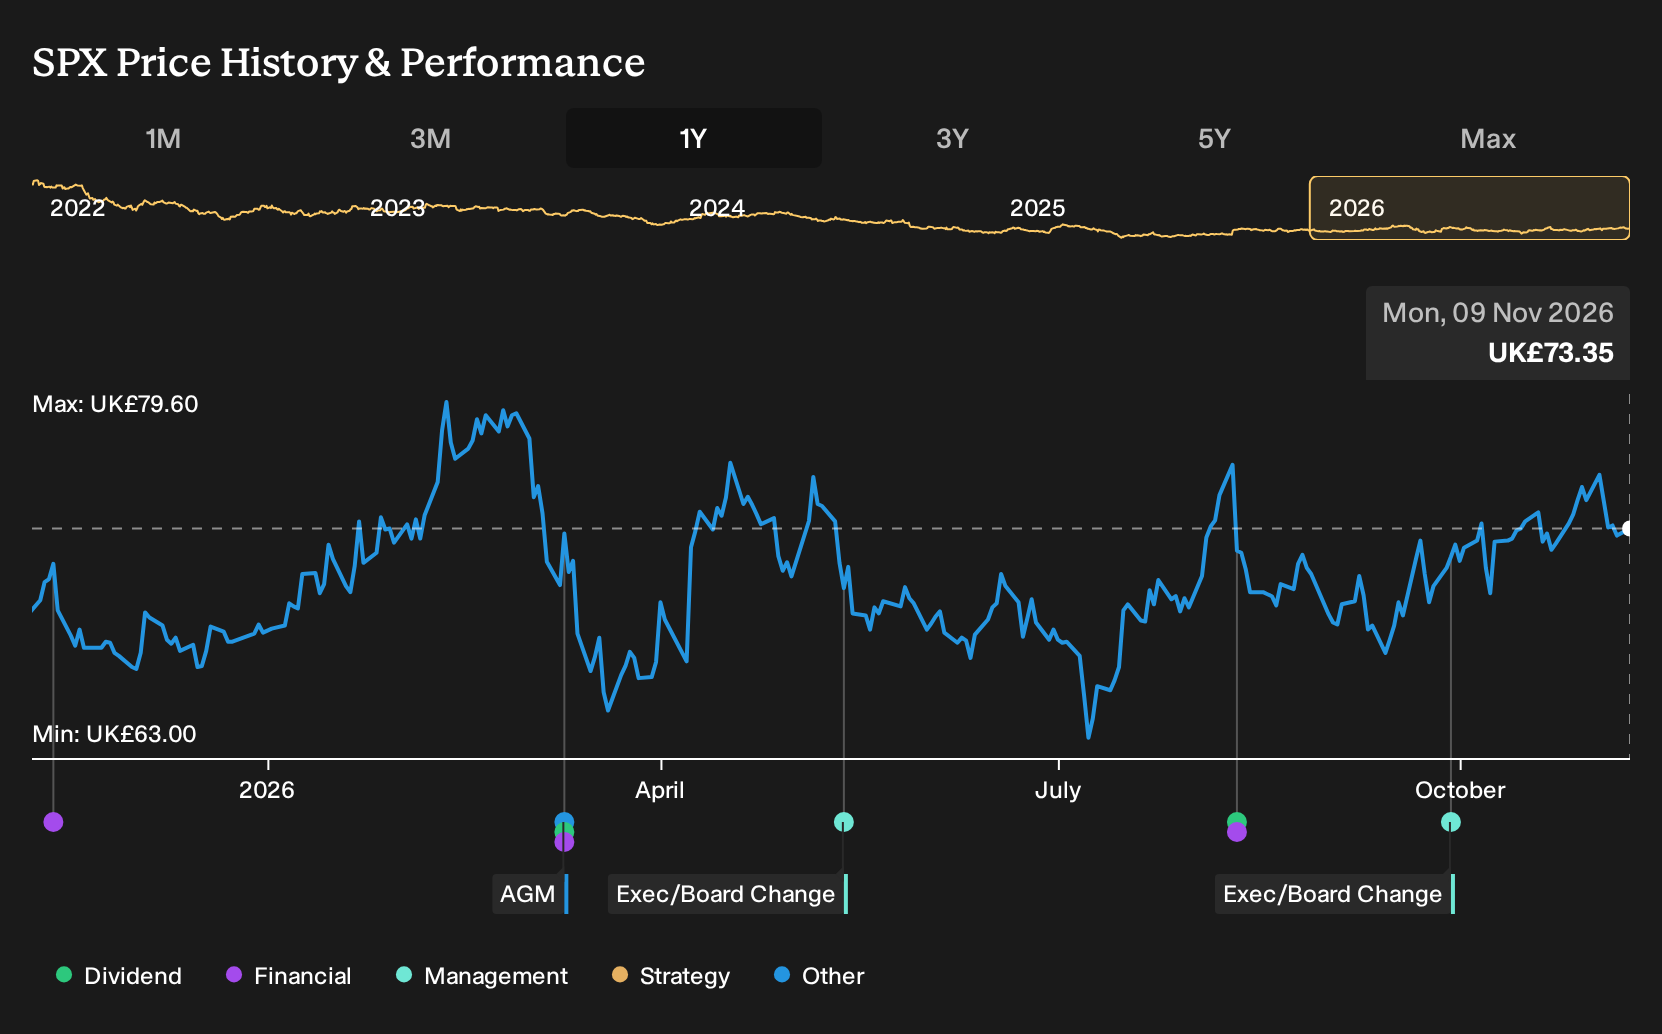
Those building blocks then feed into the consensus price target of £81.11 per share, which sits 8.7% above the current £74.05 share price. Forecasts in the Simply Wall St report assume investors would accept that P/E of 27.5x on the 2029 earnings outcome when discounting back using a rate of about 9.3%, even though that multiple is a touch above the current 27.1x for the wider GB Machinery industry.
Spirax Group's narrative projects £2.0b revenue and £285.2m earnings by 2029. This requires 5.3% yearly revenue growth and an earnings increase of £87.0m from £198.2m today.
Uncover why Spirax Group's fair value indicates an 11% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
One bullish twist on the Spirax Group story focuses on the decarbonization pull through effect. The most optimistic analysts were modelling about £2.2b revenue and £317.4m earnings by 2029, compared with the consensus £2.0b and £285.2m. That is a very different earnings path. Treat this latest news as a prompt to test which narrative you find more convincing, since both were written before the update.
Explore 3 other Spirax Group fair value estimates, including one that indicates up to 11% potential upside from the current price.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Spirax Group research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Spirax Group. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Spirax Group's overall financial health at a glance.
Looking For More Investment Ideas Beyond Spirax Group?
If the Spirax Group story has sharpened your thinking on decarbonization and efficiency, you can use that momentum to refresh your wider watchlist. The Simply Wall St Screener lets you line up potential opportunities by quality, balance sheet strength, income potential and more, so you can build a shortlist that matches your own risk and return preferences.
- For investors who value stability first, consider a basket of companies screened for resilient finances and muted risk scores through the 4 resilient stocks with low risk scores.
- If long term compounding and robust fundamentals matter more to you than headline popularity, scan a 5 high quality undiscovered gems that might not yet be on the broader market's radar.
- Income seekers who want yield backed by substance rather than hope can focus on a curated set of 6 dividend fortresses that aim to pair higher payouts with durable businesses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com