


- EDP, S.A. reported third quarter 2026 sales of €4,382.89m and net income of €462.02m, with nine month sales of €12,146.46m and net income of €1,193.79m, alongside higher basic and diluted earnings per share from continuing operations than a year earlier.
- The group upgraded 2026 guidance for recurring EBITDA to about €5.4b and recurring net profit to a range of €1.4b to €1.5b, highlighting contributions from electricity networks, renewables and a liquidity position that management indicates covers refinancing needs until 2029.
- We will now look at how EDP's higher 2026 recurring earnings guidance could reshape the investment narrative around its grid and renewables plans.
Compare EDP's upgraded 2026 guidance with peers and spot other grid and renewables players with potential momentum using our curated 42 power grid technology and infrastructure stocks
EDP Investment Narrative Recap
To own EDP, you need to be comfortable with a regulated grid and renewables story where capital spending, asset rotations and cost control drive the outcome. The analyst consensus narrative on Simply Wall St leans on that execution holding together. The upgraded recurring EBITDA and net profit guidance tightens focus on delivery of those 2026 to 2028 investment and OpEx plans.
The main short term swing factor is how efficiently EDP executes its heavier grid and renewables capex while keeping funding costs manageable, given interest cover is flagged as weak. The biggest operational risk still sits in external shocks, from FX in Brazil to weather events that could force extra, lower return capex.
The third quarter 2026 earnings release is the key update here. Sales reached €4,382.89m and net income came in at €462.02m for the quarter, with nine month net income at €1,193.79m. Basic and diluted earnings per share from continuing operations rose to €0.11 in the quarter and €0.29 over nine months, compared with the prior year periods.
Those figures give you a clearer yardstick for EDP against the catalysts in the analyst consensus narrative on Simply Wall St, including the €12b investment and €6b asset rotation ambitions for 2026 to 2028. They also frame the financing questions highlighted in the risk checks, such as interest coverage and dividend cash flow support, which remain important execution watchpoints.
EDP's current analyst narrative points to €16.5b in revenue and €1.4b in earnings by 2029, based on forecasts that assume 1.7% yearly revenue growth and an earnings increase of about €200m from the €1.2b level today.
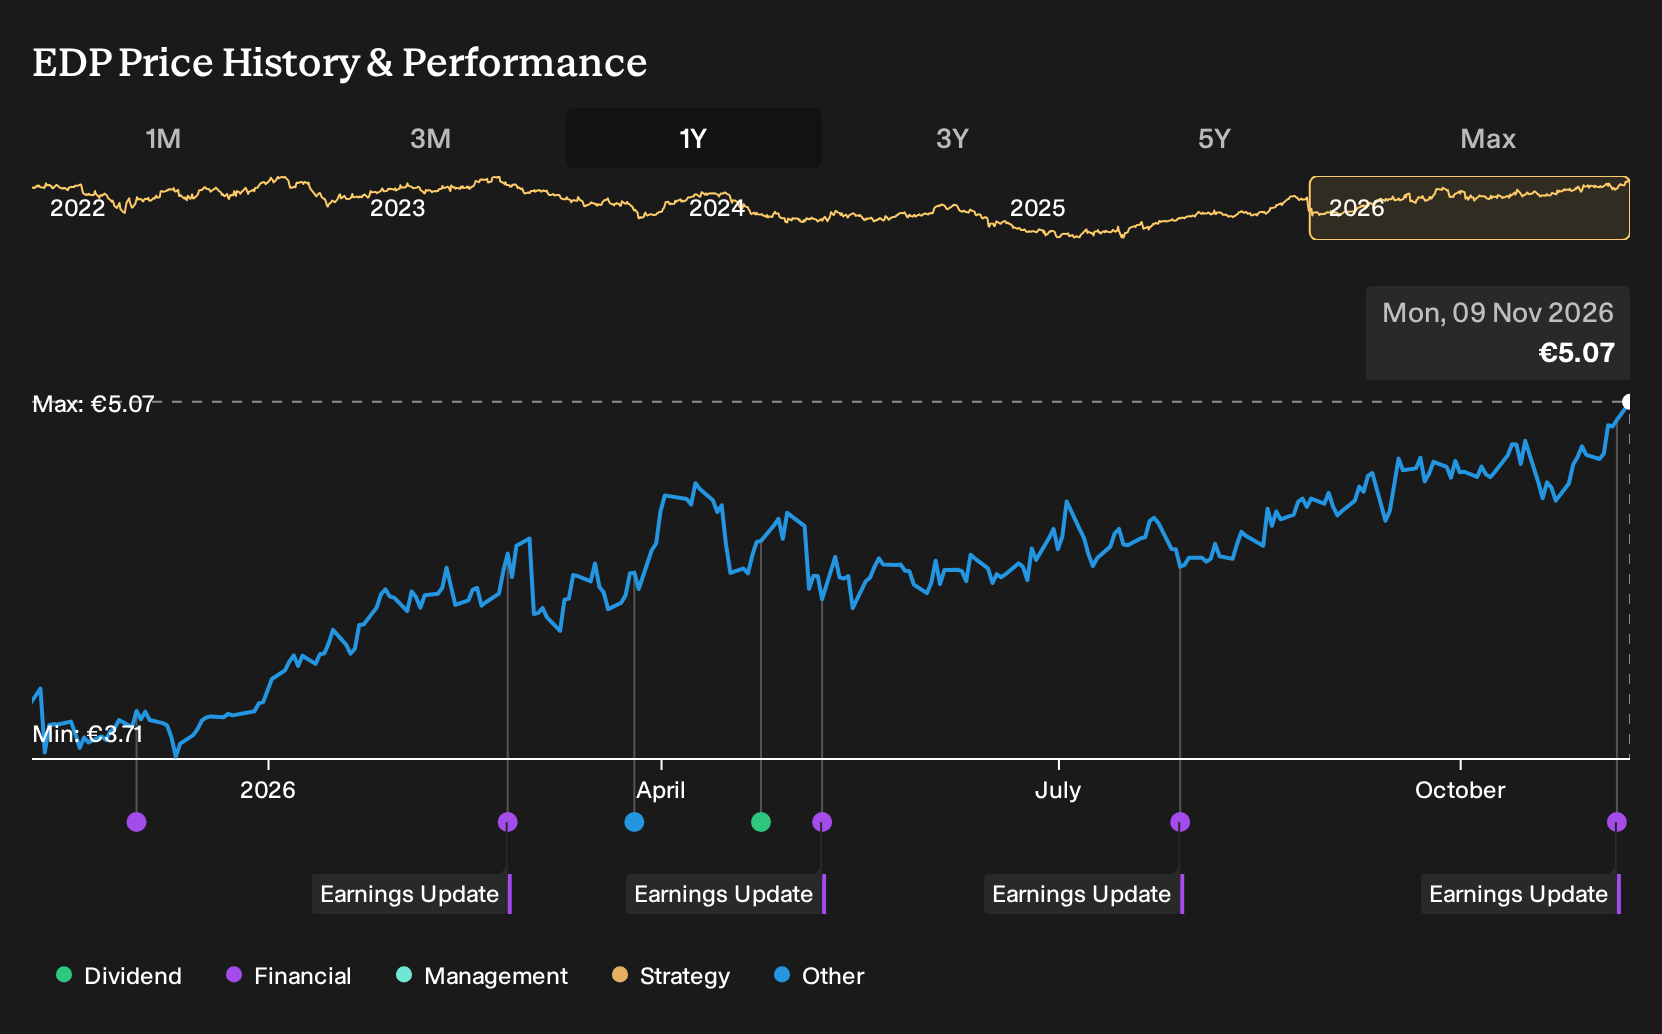
Uncover why EDP's fair value indicates a 3% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
One alternate take on EDP leans on grid flexibility as a catalyst. The most optimistic analysts were already pencilling in revenue of about €19.6b and earnings near €1.5b by 2029, compared with €16.5b and €1.4b in the consensus view before this earnings upgrade. Use this gap as a prompt to explore how your own expectations might differ.
Explore 5 other EDP fair value estimates, including one that suggests potential upside of up to 18% from the current price.
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your EDP research is our analysis highlighting 1 key reward and 2 important warning signs that could impact your investment decision.
- See our latest analysis for EDP. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate EDP's overall financial health at a glance.
Looking for more investment ideas beyond EDP?
If you want to stress test your view on EDP against what else is out there, cast the net wider using the Simply Wall St Screener. It can help you line up companies with similar characteristics, compare fundamentals side by side, and spot opportunities that fit your own risk and income preferences.
- For investors who care most about resilient balance sheets and fundamentals, start with our curated list of solid balance sheet and fundamentals (194 results) to see which businesses match that profile.
- If value and quality are your priority, scan our hand picked 218 high quality undervalued stocks to find companies that combine earnings strength with supportive valuations.
- For readers who prefer stability and income potential, check out a focused 224 dividend fortresses that highlights higher yielding payers with supporting metrics.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com