


- Dime Commercial Bancshares has been reshaping its business away from a thrift-style multifamily focus toward a broader commercial bank that leans more on business and commercial real estate lending tied to U.S. interest rates and credit conditions.
- This pivot toward a more diversified loan mix signals management’s intent to rely less on multifamily exposure and more on serving commercial clients. It is reshaping how the balance sheet earns income and manages risk.
- We will now look at how Dime Commercial Bancshares' shift toward diversified commercial lending could reshape its longer term investment narrative.
Scan Dime Commercial Bancshares’ shift toward commercial lending along with hand-picked peers by reviewing the list of solid balance sheet and fundamentals (25 results) that may handle interest rate and credit cycles with more resilience.
Dime Commercial Bancshares Investment Narrative Recap
To own Dime Commercial Bancshares, you need to be comfortable with a bank that is leaning harder into commercial lending and is closely tied to U.S. interest rate and credit trends. The analyst consensus Narrative on Simply Wall St highlights a simple requirement. Management needs to turn its low cost commercial deposits and loan repricing pipeline into a healthier net interest margin without credit problems or higher costs absorbing the benefit.
The short term swing factor is whether repricing roughly US$2.5b of loans near 4.25% and growing commercial deposits shows up clearly in earnings. The main risk is expense creep and credit costs. Core cash operating expenses are guided to about US$260m to fund new teams and verticals, while allowances for credit losses already sit near 98 basis points of loans after recent provisions.
Recent communication around Dime Commercial Bancshares’ push into equipment and franchise finance, together with new deposit gathering teams, ties directly into this pivot toward a fuller commercial bank profile. Those initiatives sit at the center of the expected commercial mix shift, from shrinking multifamily toward roughly 25% of total loans to expanding business lending categories.
The same update that flagged these expansions also pointed to higher operating costs and the prior US$14m provision related to investor commercial real estate and multifamily reserves. For you as a shareholder, that means execution risk is very tangible. The loan repricing opportunity, the larger commercial portfolio and the growing municipal and business deposit base all matter, but they need to outpace both new spending and any further credit charges for the thesis to hold together.
Dime Commercial Bancshares' narrative projects US$662.6 million in revenue and US$220.6 million in earnings by 2029. This implies 14.7% yearly revenue growth and an earnings increase of about US$101.3 million from current earnings of US$119.3 million.
Uncover why Dime Commercial Bancshares' fair value indicates an 8% potential upside to its current price that could narrow quickly.
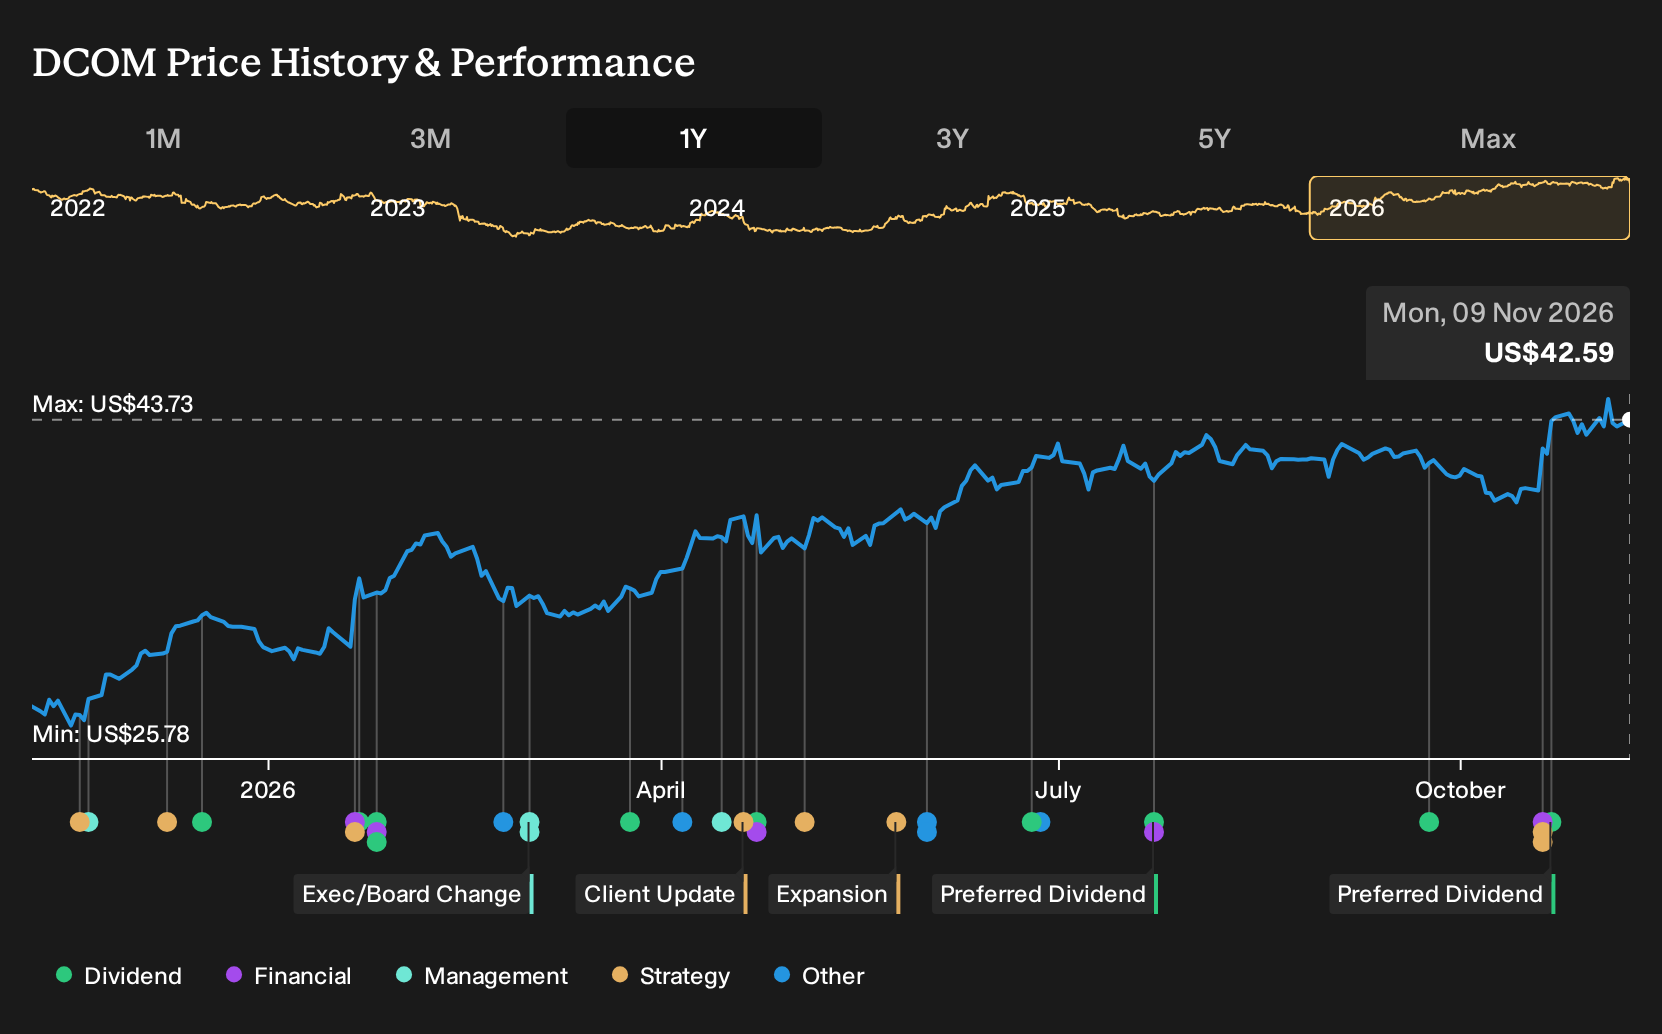
Exploring Other Perspectives
Three fair value estimates from the Simply Wall St Community span roughly US$46 to about US$88.6 per share, which is a wide gap for the same Dime Commercial Bancshares story. Before reacting to that spread, consider how rising operating costs, shifting loan mix and future credit conditions could all pull actual performance away from any single community forecast.
Explore 2 other Dime Commercial Bancshares fair value estimates, including one that suggests it could be worth just $46.00.
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Dime Commercial Bancshares research is our analysis highlighting 4 key rewards that could impact your investment decision.
- See our latest analysis for Dime Commercial Bancshares. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Dime Commercial Bancshares' overall financial health at a glance.
Looking For More Investment Ideas Beyond Dime Commercial Bancshares?
If you want to stress test what you think about Dime Commercial Bancshares against other opportunities, broaden your watchlist using the Simply Wall St Screener. It helps you line up banks and non financials side by side so you can compare balance sheets, income quality and risk profiles with a clear framework instead of relying on headlines.
- For investors who care most about financial resilience, start with companies that score well on leverage and liquidity checks by scanning the 31 resilient stocks with low risk scores.
- If dependable income is your priority, review businesses with higher yields and track records of paying shareholders through the 7 dividend fortresses.
- To spot opportunities that are not yet widely followed but backed by solid fundamentals, widen your search using the 19 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com