


Algonquin Power & Utilities (TSX:AQN) is back in focus after its Q3 2026 update, which combined higher adjusted earnings, a reaffirmed outlook, and fresh moves on portfolio simplification and U.S. redomicile.
Those Q3 headlines arrived against a backdrop of a CA$7.98 share price and a 1 month share price return of 9.62%. This suggests recent momentum has picked up, even though the year to date share price return is down 5.23% and the 1 year total shareholder return is down 5.67%, while the 3 year total shareholder return is up 23.72% and the 5 year total shareholder return is down 40.58%.
Scan how Algonquin Power & Utilities compares with other regulated utilities by reviewing our hand picked list of solid balance sheet and fundamentals (5 results) in the same income resilient corner of the market.
After that Q3 lift, a reaffirmed outlook, and early steps to simplify the portfolio, the key tension is clear: Does Algonquin Power & Utilities still offer enough upside to justify the risks at this price?
Most Popular Narrative: 16% Undervalued
On the Simply Wall St analyst consensus Narrative, Algonquin Power & Utilities screens as undervalued, with a fair value of CA$9.50 against the latest close of CA$7.98. That model leans on forecast earnings, revenue and tax changes, then discounts those future cash flows back at a 6.44% rate.
The main thing that has to go right is continued execution on rate cases, cost discipline and balance sheet repair so that credit metrics remain compatible with investment grade ratings while funding about $3.2b of 2026 to 2028 utility CapEx without issuing equity through 2027.
The current valuation implies that the market is cautious about Algonquin Power & Utilities delivering on its regulated growth, planned tax and EPS benefits from redomiciling, and maintaining its reset dividend while earning closer to allowed returns.
See why 63 investors see Algonquin Power & Utilities as 16% undervalued.
Result: Fair Value of CA$9.50 (UNDERVALUED)
Still, Algonquin Power & Utilities is exposed if rate base growth or allowed returns fall short, and if credit metrics weaken further as CapEx and funding needs build.
Find out about the key risks to this Algonquin Power & Utilities narrative.
Another View: What The P/E Ratio Says About Algonquin Power & Utilities
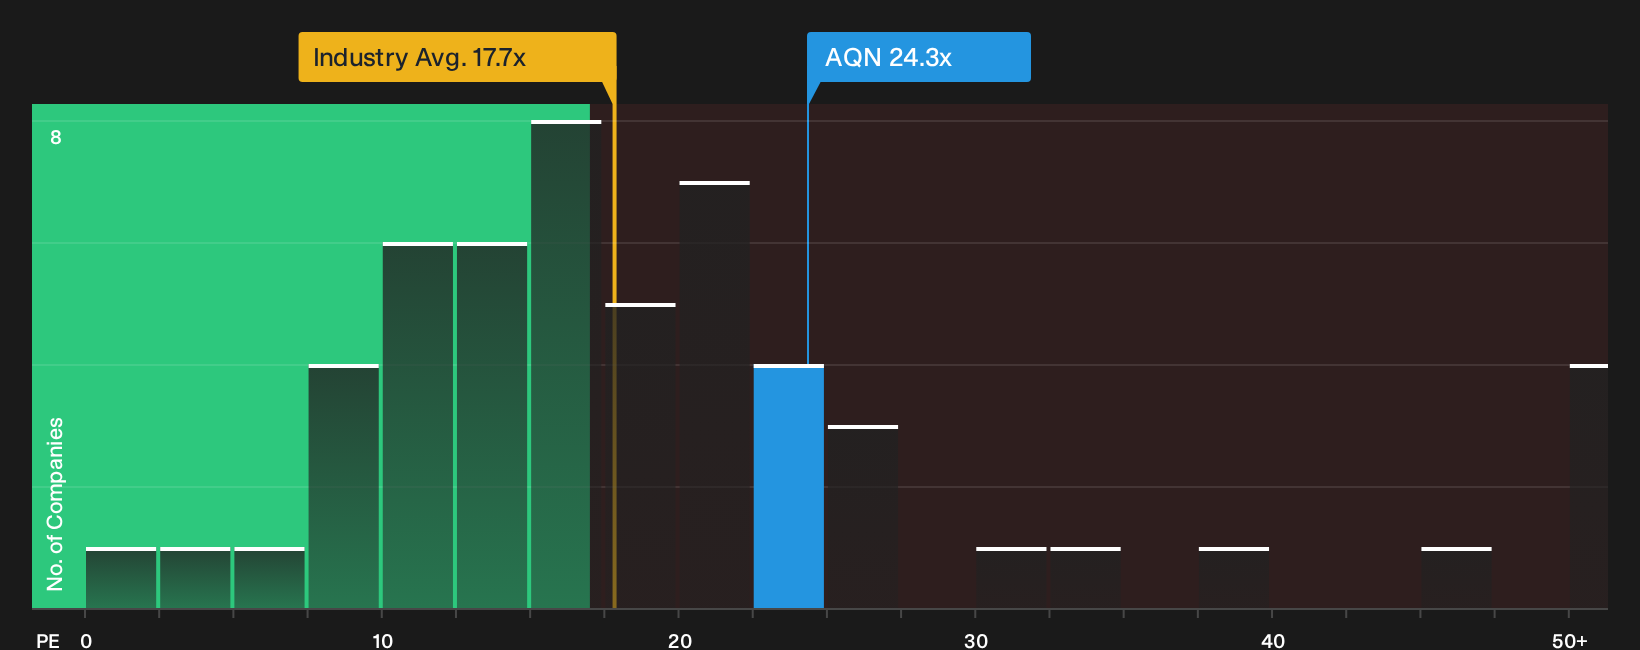
The DCF workup points to upside, yet the simple P/E snapshot tells a different story. Algonquin Power & Utilities trades on 24.8x earnings, which is richer than the global integrated utilities group at 17.7x, although below its own fair ratio of 34.9x. That mix of premium versus peers but discount to fair ratio raises a practical question for investors: Is the market overpaying for near term earnings, or underestimating the longer term earnings path implied by that higher fair ratio?
For a closer look at how this valuation gap might close in either direction over time, start with the fuller breakdown behind these multiples, then weigh it against your own expectations for earnings quality and growth. See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around Algonquin Power & Utilities can either sharpen conviction or create doubt, so move quickly, stress test the thesis, and weigh both the upside and the risk markers by checking the 3 key rewards and 3 important warning signs
Looking for more Algonquin Power & Utilities sized investment ideas?
If Algonquin Power & Utilities has sharpened your thinking on risk, income and value, use that same framework to size up a broader watchlist.
- Target potential mispricing opportunities by scanning a curated pool of companies on our 6 high quality undervalued stocks with strong fundamentals and disciplined balance sheets.
- Lock in potential income streams by reviewing a focused universe of resilient payers across the 3 dividend fortresses that emphasise yield alongside financial strength.
- Prioritise resilience first by filtering for businesses on the 9 resilient stocks with low risk scores that pair sturdier balance sheets with lower risk profiles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com