


UCB (ENXTBR:UCB) has put fresh clinical data at the center of the investment story, with new results for BIMZELX in psoriatic arthritis and dapirolizumab pegol in systemic lupus erythematosus spotlighting its late stage autoimmune pipeline.
For investors, the timing of this clinical news aligns with a powerful run in UCB’s shares. The current share price is €298.8 and a 30 day share price return of 46.83% points to rapidly rising enthusiasm, while a 1 year total shareholder return of 33.86% and a very large 3 year total shareholder return suggest that longer term holders have already seen substantial value creation even before these latest updates.
Capitalize on UCB’s momentum by scanning a curated 128 healthcare AI stocks that could be pricing in the next wave of clinically driven catalysts.After a 46.8% move in 30 days and UCB now close to €300, the real tension is simple: do you lean into this autoimmune pipeline story today or wait for a cooler entry that the valuation might eventually offer?
Most Popular Narrative: 28% Overvalued
UCB’s last close at €298.8 sits above the fair value of €232.56 set out in the narrative, which frames the current price as demanding and heavily reliant on long term cash flows according to StoxEurope, an investor in the Simply Wall St Community who built the valuation.
Back to the margin: About three quarters of the value (73.1%) comes from after year 5 (2030), so the margin UCB holds carries most of the number. Our base holds 28.99% from 2026; UCB guides 2026 only, and its 2026 results on 25 February 2027 are the first full-year test. The first half of 2026 included a favourable gross-to-net adjustment for earlier periods, with no amount printed. UCB's own impairment test discounts at 8.25% after tax, above our 7.24%.
See why 4 investors see UCB as 28% overvalued.
Result: Fair Value of €232.56 (OVERVALUED)
Still, the story can change quickly if BIMZELX or dapirolizumab data disappoints, or if pricing pressure squeezes the 28.99% margin that the narrative leans on.
Find out about the key risks to this UCB narrative.
Another View: SWS DCF Says Undervalued
The StoxEurope narrative frames UCB as 28% overvalued at €298.8 versus its €232.56 fair value. Our discounted cash flow model points the other way. It estimates a future cash flow value of €587.91 per share, which implies the current quote trades at roughly half that level. Which set of assumptions do you trust more?
Look into how the SWS DCF model arrives at its fair value.
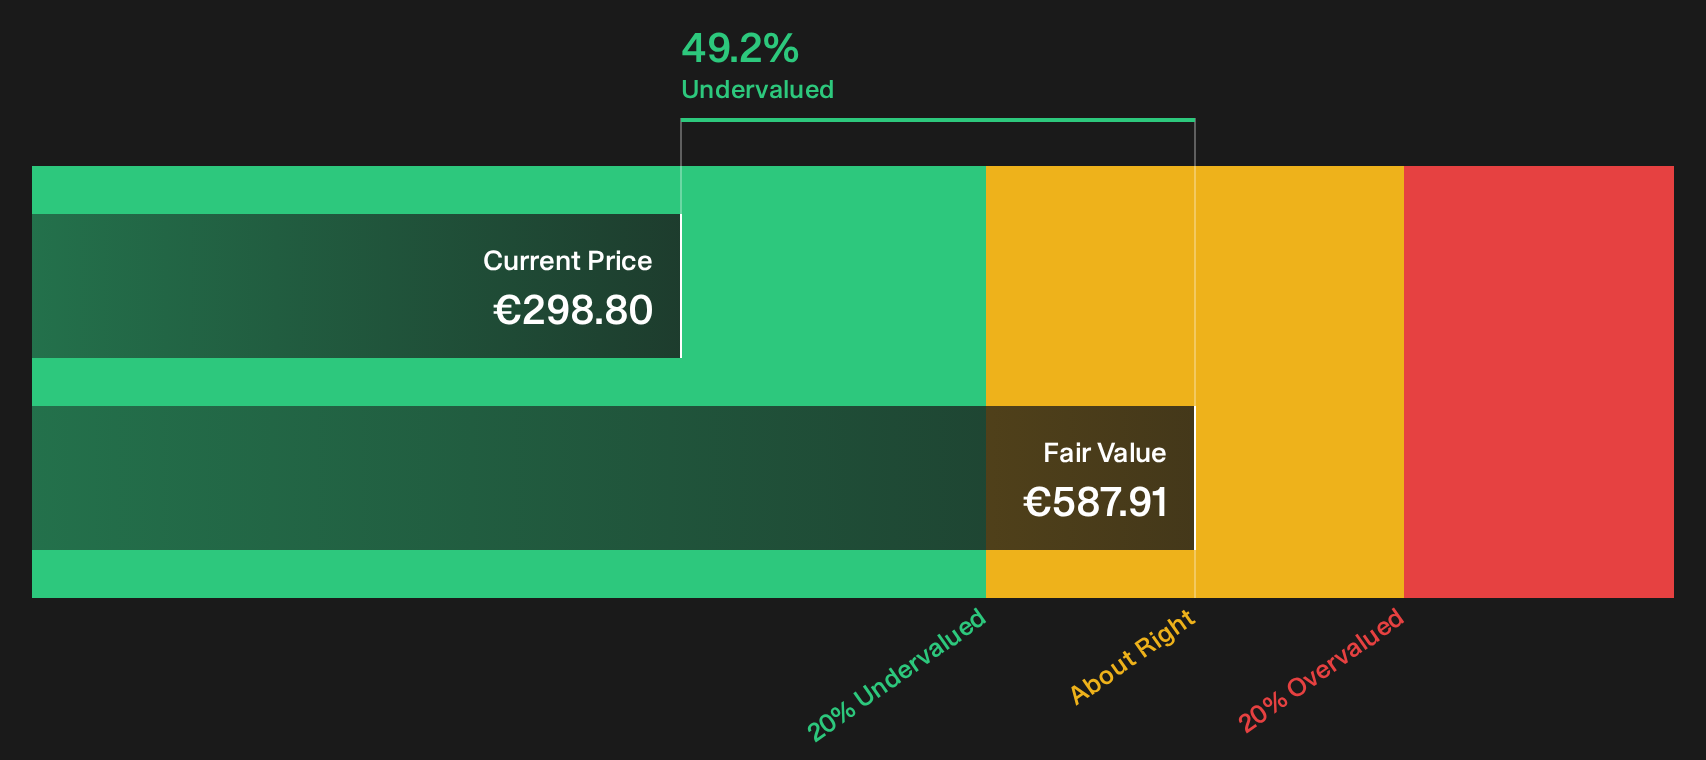
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out UCB for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 210 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed messages on UCB’s valuation and pipeline can pull you in both directions. Act while the information is fresh and weigh the 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond UCB?
Do not stop with a single autoimmune story when the wider market is full of potential. Use targeted stock lists to pressure test your next move.
- Target resilient cash generators by scanning a curated 210 high quality undervalued stocks that could align stronger fundamentals with more modest expectations.
- Prioritize sleep at night holdings and filter for a 202 resilient stocks with low risk scores that screens for sturdier balance sheets and steadier business profiles.
- Hunt for overlooked potential and sort through a 572 high quality undiscovered gems that may not yet feature on crowded watchlists but still show solid underpinnings.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com