


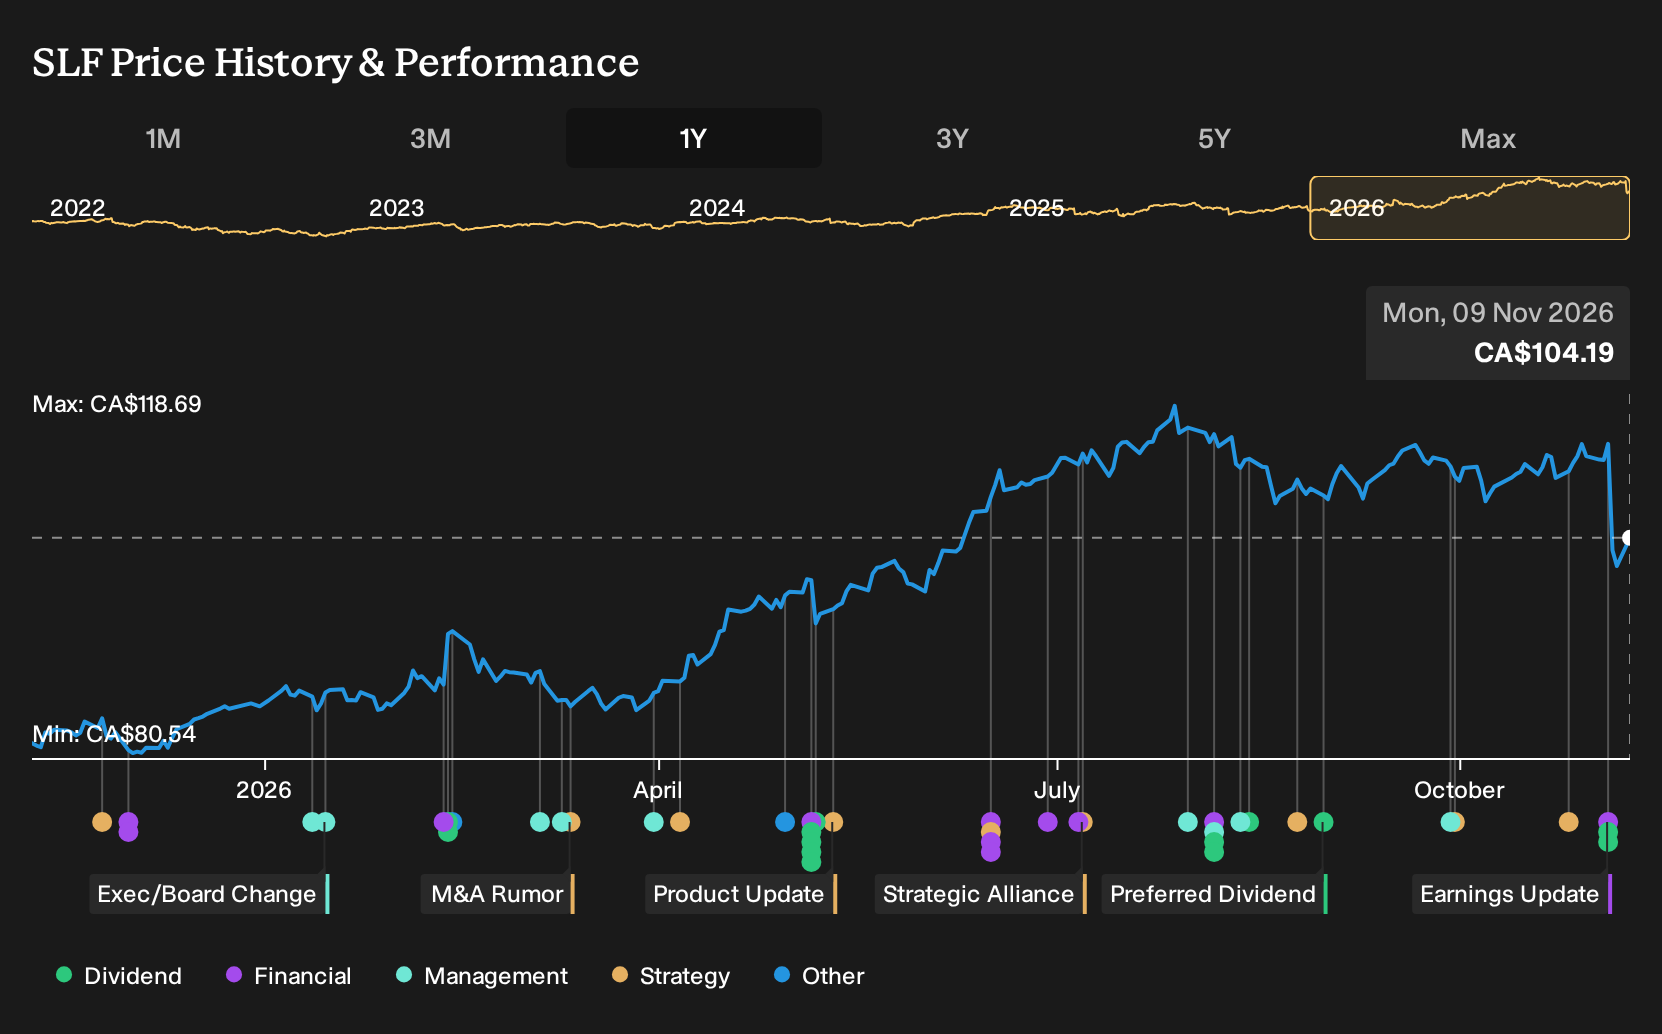
- Sun Life Financial reported third quarter 2026 net income of C$813 million and nine month net income of C$2.33 billion, alongside a quarterly common dividend of C$1.00 per share and declared preferred share dividends payable on December 31, 2026.
- Underlying earnings per share increased in the quarter while reported profit declined. The higher dividend signals management’s focus on consistent shareholder payouts supported by segment level operating strength in Canada, the U.S. and Asia.
- We will now look at how Sun Life Financial's stronger underlying earnings and higher dividend could influence the existing investment narrative.
Sun Life Financial Investment Narrative Recap
To own Sun Life Financial, you need to believe the business can keep leaning into capital light fee income in Asia, U.S. group benefits and SLC Management while keeping capital strength intact. The recent quarter showed reported net income of C$813 million and C$2.33b for the nine months, so the big picture on earnings power still matters more than one period.
The analyst consensus narrative on Simply Wall St focuses on execution in Asia and U.S. benefits as key near term drivers. At the same time, U.S. Dental and asset management fee pressure remain the biggest watchpoints. The Q3 earnings miss on a year over year basis does not materially change those core catalysts or the main risks.
The common dividend increase to C$1.00 per share looks most relevant here because it interacts directly with the story around capital generation and payout sustainability. Management lifted the quarterly amount by C$0.04 while reporting lower net income than a year ago. This puts more attention on cash generation, LICAT ratios and earnings mix quality over the next few quarters.
For income focused holders, the higher common payout and the declared preferred share dividends concentrate the conversation on dividend coverage from underlying results in Canada, the U.S. and Asia. That makes execution on growth in fee based businesses, control of U.S. Dental exposure and stability of asset management flows even more important as potential catalysts for sentiment around Sun Life Financial.
Sun Life Financial's current analyst scenario points to revenues of CA$44.2 billion and earnings of CA$4.7 billion by 2029, based on an assumed 7.5% yearly revenue growth rate and an earnings increase of about CA$1.7 billion from CA$3.0 billion today.
Uncover why Sun Life Financial's fair value indicates an 8% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
Some of the most optimistic analysts framed the dividend increase at Sun Life Financial against a very upbeat earnings path. Before this result, they were mapping out revenue of about CA$50.6b and earnings of roughly CA$5.8b by 2029. You can use those higher expectations to test how your own view might shift after this quarter.
Explore another Sun Life Financial fair value estimate, including one that suggests as much as 114% upside from the current price!
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment results rarely come from following the herd, so rely on your own analysis.
- A great starting point for your Sun Life Financial research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Sun Life Financial. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Sun Life Financial's overall financial health at a glance.
Looking for more investment ideas beyond Sun Life Financial?
If you want to stress test your view on Sun Life Financial against other opportunities, using the Simply Wall St Screener can help you scan for different types of companies that fit your risk and income preferences.
- If capital preservation matters most, consider starting with a set of resilient businesses screened for lower risk profiles by reviewing 9 resilient stocks with low risk scores.
- If reliable balance sheets appeal to you, compare Sun Life Financial with companies that pair solid financial footing and fundamentals through our list of solid balance sheet and fundamentals (5 results).
- If you are hunting for overlooked opportunities with stronger fundamentals, broaden your watchlist using the 7 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com