


- Western Digital is reporting strong demand for high-capacity hard disk drives linked to AI and cloud storage workloads, alongside higher-capacity product launches, a raised quarterly dividend, and long-term customer commitments that management says extend into the early 2030s.
- The company is also becoming more visible in momentum-based screens and in quantum computing collaborations, which ties its traditional storage expertise to emerging compute architectures and reinforces how central its drives are to AI and data center buildouts.
- We will now see how Western Digital's tighter link to AI driven high-capacity storage demand could reshape the existing investment narrative.
Scan Western Digital's peers riding similar AI and data infrastructure themes by running the curated 53 AI infrastructure stocks alongside this story.
Western Digital Investment Narrative Recap
To own Western Digital, you need to believe the AI and cloud buildout keeps pulling in high capacity HDDs and that the current tight market for drives does not reverse quickly. In the short term, the key swing factor is how well management converts that demand into consistent shipment volumes and cash flow, while keeping the focus on enterprise customers rather than more price-sensitive segments.
The biggest near term risk is exactly what mitchell_lawler, a Simply Wall St Community investor who wrote the narrative, flags. Very strong margins can tempt new capacity, which could soften pricing if supply rises or AI capex slows. Any meaningful shift in China storage supply or a faster move toward cheaper flash would also test that thesis.
The dividend increase is the clearest recent move that ties directly to the current news flow. Management is effectively saying the cash generation from high capacity drives linked to AI and cloud workloads is, in their view, solid enough to support higher regular payouts, on top of long term customer commitments running into 2030 and 2031.
For you as a shareholder, that payout shift makes execution on pricing and volumes even more important. A richer dividend policy can look attractive when earnings are strong. However, it raises the stakes if the HDD cycle normalises, if margins drift back toward industry averages, or if Western Digital needs heavier reinvestment to keep its technology roadmap competitive.
The narrative from mitchell_lawler pins fair value at US$329.76, mainly because it assumes Western Digital can hold net margins near 23% over the next decade. This is well above wider tech hardware levels and reflects the belief that the current HDD oligopoly keeps a meaningful share of today’s pricing power.
Uncover why Western Digital's fair value indicates a 14% potential upside to its current price before that discount closes.
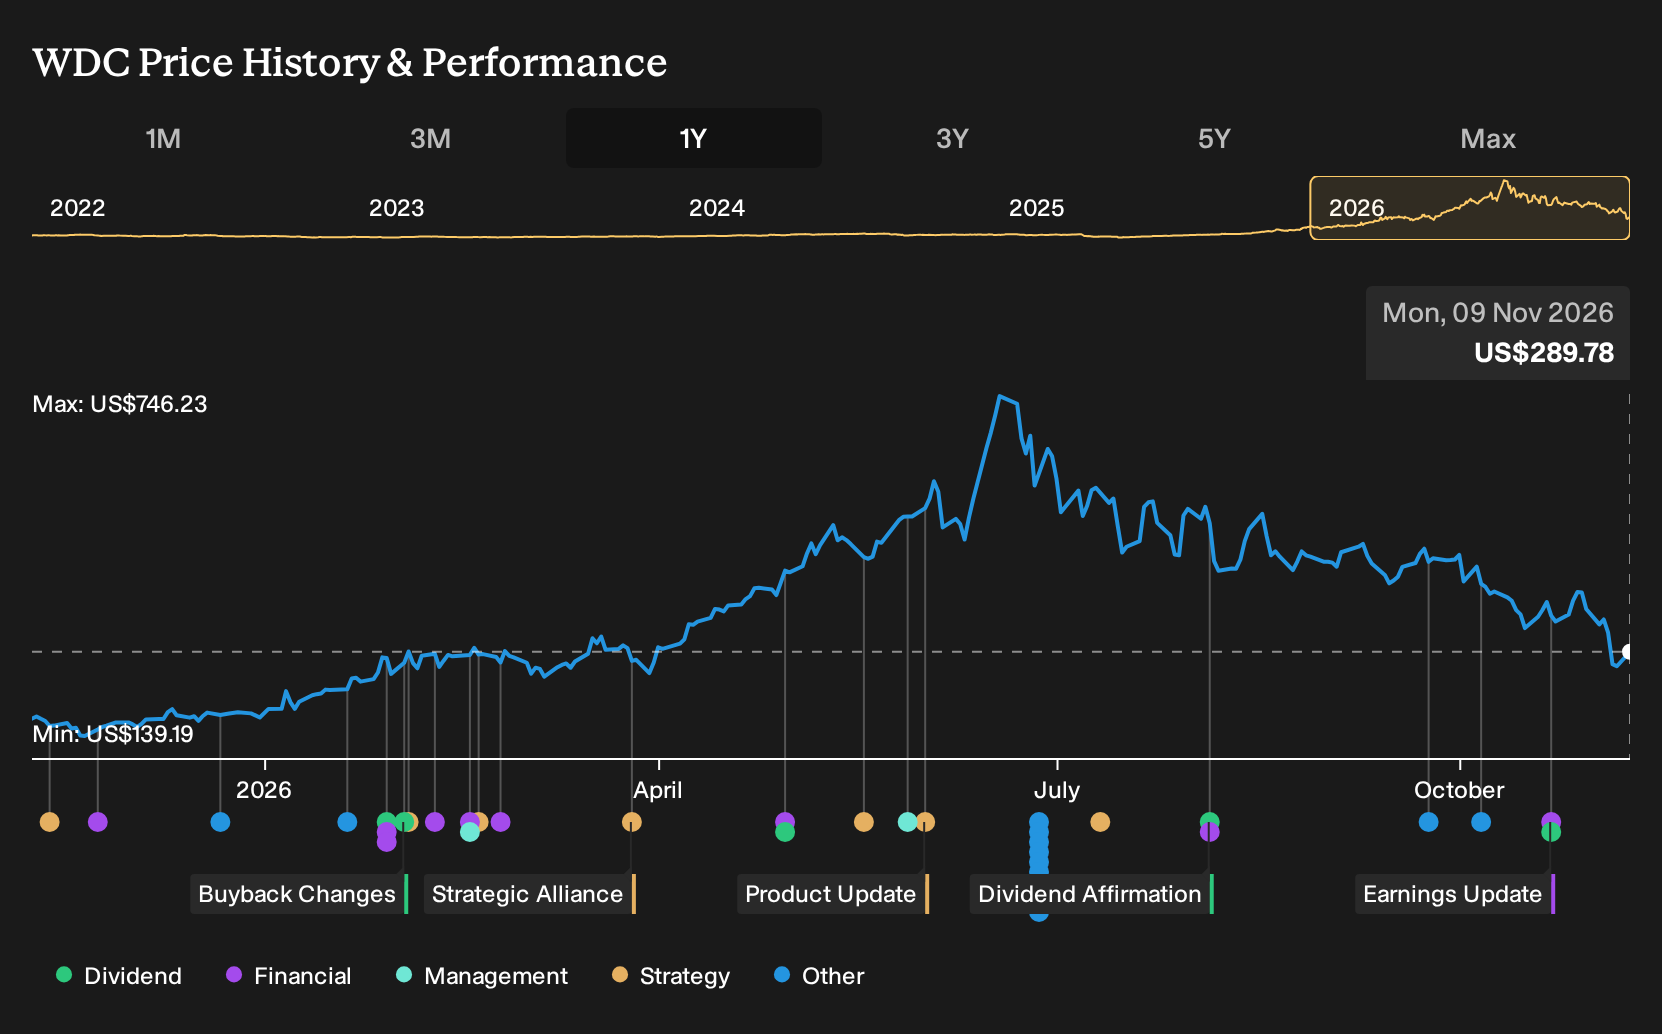
Exploring Other Perspectives
Some of the most optimistic analysts focus on Western Digital's high capacity roadmap as the real swing factor. They were projecting revenue of US$46.7b and earnings of US$23.7b by about October 2029, with a higher P/E multiple than today. Those forecasts came before this dividend and AI demand news, so opinions may evolve and it is important to explore several viewpoints yourself.
Explore 6 other Western Digital fair value estimates, including one that suggests as much as 202% upside from the current price.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Western Digital research is our analysis highlighting 4 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Western Digital. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Western Digital's overall financial health at a glance.
Looking for more Western Digital style investment ideas?
If you want to put the Western Digital story in context, it helps to scan a wider field of potential opportunities using the Simply Wall St Screener. Pick a few different angles, compare how businesses stack up on quality, risk, and income, then decide where you want to spend more research time.
- For investors who care most about quality and valuation together, start with a curated set of 33 high quality undervalued stocks that combine strong fundamentals with prices that may not fully reflect them yet.
- If capital preservation and steadier profiles matter more to you than rapid gains, focus on a 30 resilient stocks with low risk scores that screens for businesses with more resilient characteristics.
- Income focused investors can focus on reliable cash returns by reviewing a 6 dividend fortresses built around higher yielding payouts.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com