


BlackBerry (TSX:BB) is back in focus after its QNX unit, working with Valeo, secured multiple front-view smart camera design wins in China, while recent quarterly results showed 26% revenue growth and a 150% jump in earnings per share.
Recent trading has reflected that QNX story and the stronger quarterly numbers, with BlackBerry’s share price returning 5.35% over the past day and 15.78% over the past week. The 1 year total shareholder return of 100.15% and 3 year total shareholder return of 166.74% point to a powerful rebound that has lifted the CA$12.99 share price on rising optimism about both growth potential and perceived risk.
Spot 53 AI infrastructure stocks that, like BlackBerry’s QNX business, are tied to the build out of software and hardware powering the next wave of intelligent vehicles and automation.Bulls argue BlackBerry’s QNX traction and fresh earnings strength justify the rerating, while bears see a stretched story after a 100% 1 year return. Which side do the current valuation markers support?
Most Popular Narrative: 20% Undervalued
On the most followed valuation view, BlackBerry is worth CA$16.22 a share, compared with the latest CA$12.99 close. This frames the current rally as still short of that estimate according to ArtOfLosing, a Simply Wall St Community investor who wrote the narrative.
The market is pricing BlackBerry as a maturing automotive software company. What it actually has is the safety infrastructure layer that physical AI cannot be commercially deployed without. The automotive royalty backlog took fifteen years to reach $950M. The physical AI backlog is starting from zero right now, in a faster-growing market, with the same royalty model and the same impossibility of removal once embedded.
See why 23 investors see BlackBerry as 20% undervalued.
Result: Fair Value of CA$16.22 (UNDERVALUED)
Still, elevated P/E expectations and the long wait for physical AI royalties mean any setback in QNX design wins could quickly pressure BlackBerry’s rerating story.
Find out about the key risks to this BlackBerry narrative.
Another View: What BlackBerry’s P/E Is Telling You
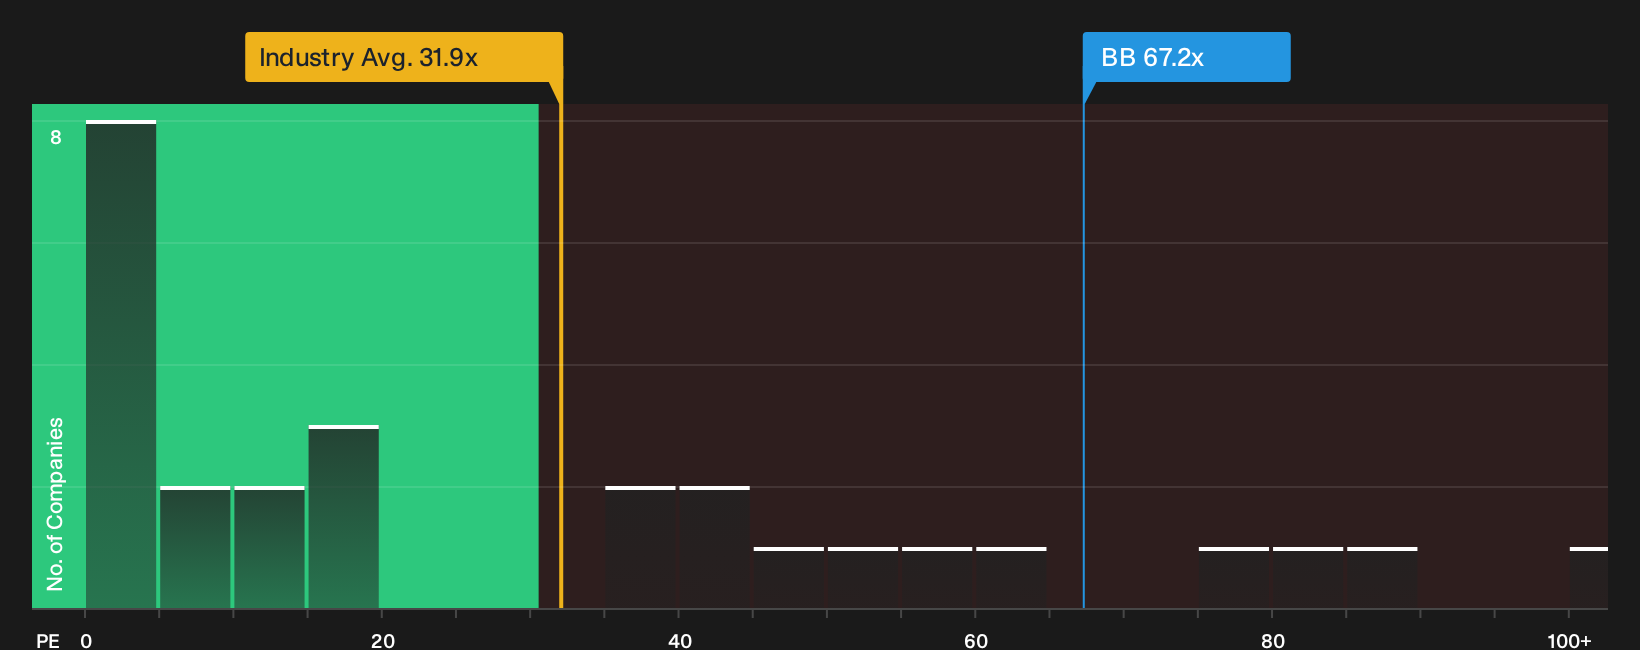
While the SWS DCF model points to a small 7.2% discount to fair value at CA$13.99, the market is already paying a rich price for BlackBerry on earnings. A 67.2x P/E sits well above the North American Software average of 31.9x, the peer group on 53.1x, and the 36.5x fair ratio, which suggests higher valuation risk if expectations cool from here.
See what the numbers say about this price in more detail in our valuation breakdown, then decide which signal you trust more: the cash flow model or the earnings multiple, when you think about position size and time horizon See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Mixed signals on BlackBerry’s value can be interpreted in different ways, so consider acting while sentiment is active and weigh the potential upside against the pushback by checking the 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond BlackBerry?
If BlackBerry has you thinking about what else could be hiding in plain sight, now is the time to widen your watchlist and pressure test your convictions.
- Zero in on resilient balance sheets and steady fundamentals by scanning a list of solid balance sheet and fundamentals (5 results) that can help you stress test your portfolio.
- Hunt for mispriced quality by checking a 7 high quality undiscovered gems before the broader market starts paying attention.
- Dial up defence in your holdings by focusing on a 9 resilient stocks with low risk scores that aims to keep surprises to a minimum when sentiment turns.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com