


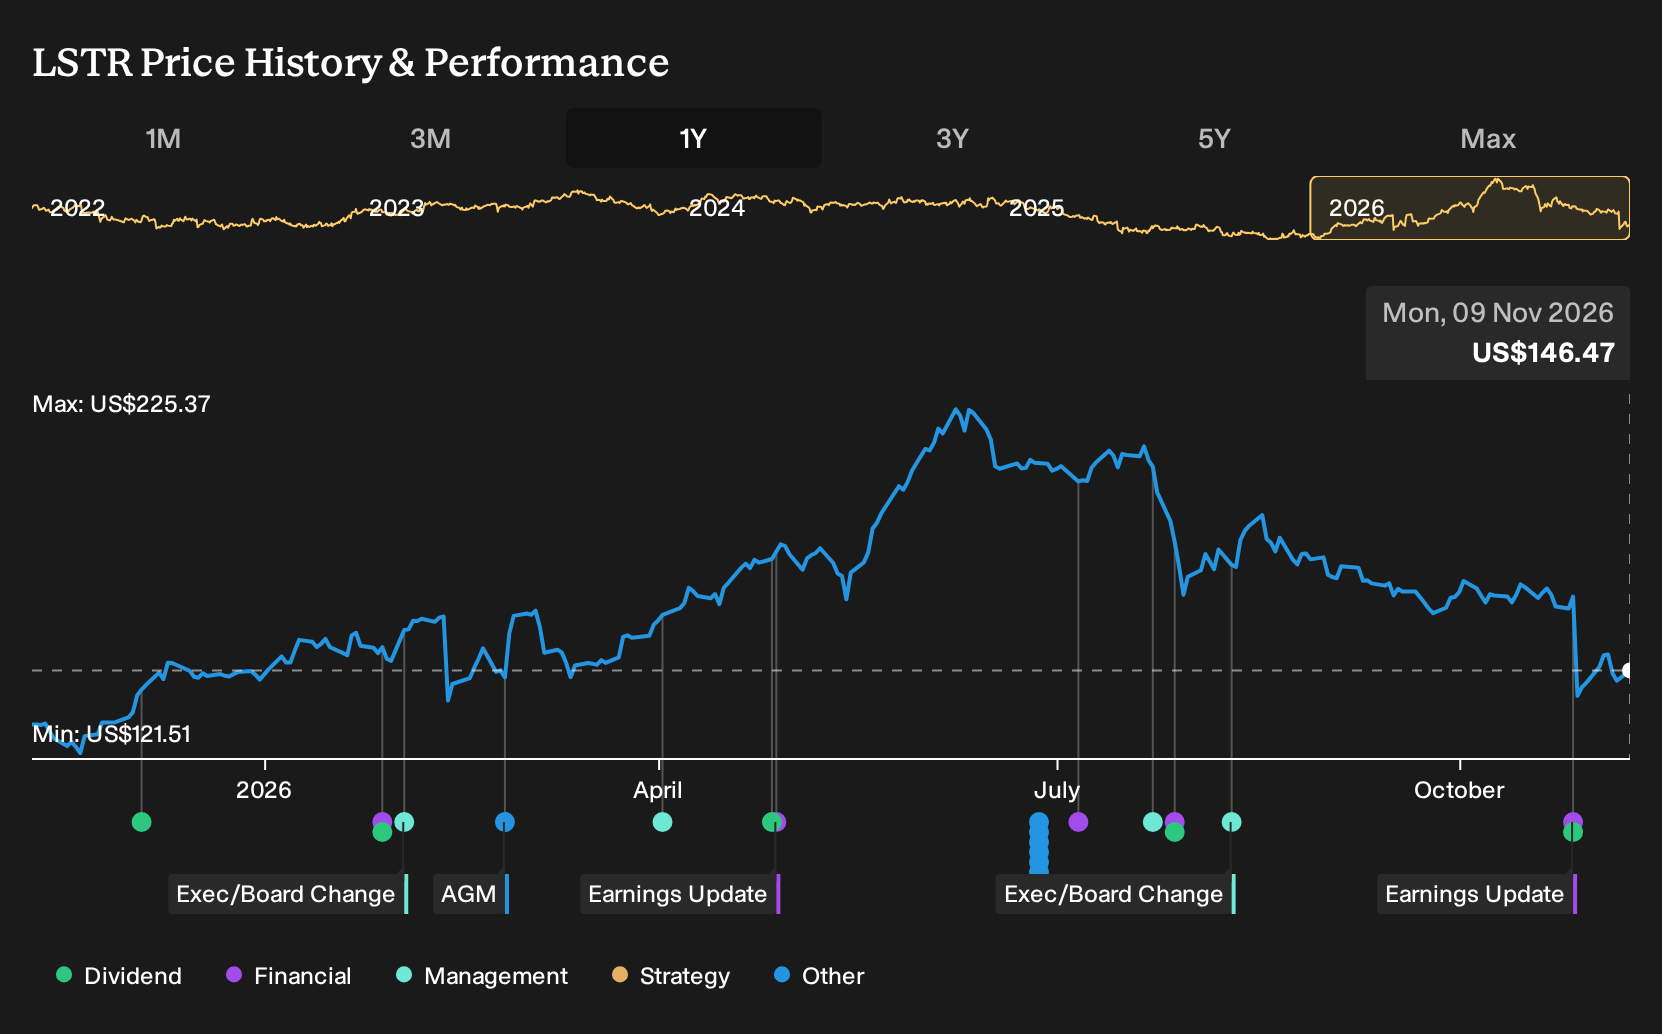
- Landstar System reported third quarter 2026 sales of US$1,490.31 million and net income of US$48.04 million, with basic EPS from continuing operations of US$1.42, alongside nine month sales of US$4,051.26 million and net income of US$136.43 million.
- The board affirmed a quarterly dividend of US$0.44 per share, which signals management’s willingness to keep returning cash while the asset light model and AI focused investment program continue to absorb capital and operational attention.
- Next, the focus shifts to how this stronger earnings performance and sustained dividend commitment could influence Landstar System's existing investment narrative.
Landstar System Investment Narrative Recap
To own Landstar System, you need to believe its asset light freight model and focus on safety and AI enabled tools can keep turning freight demand into resilient earnings. The recent quarter showed higher sales and net income compared with a year ago, which supports that narrative. The short term swing factor still sits in execution on AI and productivity, while the main risk remains insurance and claims costs staying elevated and eating into margins.
For now, the latest results read more as confirmation than reset. Profitability over nine months looks stronger than the prior period, so the analyst consensus Narrative on Simply Wall St that leans on efficiency gains and solid freight mix does not look directly challenged. The risk side is largely unchanged. Insurance expenses and any misfire in scaling AI projects could still pressure returns, particularly with the stock trading on a relatively high P/E multiple.
The clearest announcement for this catalyst story is the quarterly dividend of US$0.44 per share. A board willing to keep cash distributions steady while Landstar System pushes heavy AI and IT spend suggests management sees the current balance between reinvestment needs and shareholder returns as workable. For you, the signal is that capital allocation discipline remains a focal point alongside growth projects.
That dividend also sits next to earnings that moved higher year on year in both the third quarter and the first nine months of 2026. Taken together, the combination of stronger profitability, an affirmed payout and an asset light model leans into the catalysts highlighted in the analyst consensus Narrative on Simply Wall St, particularly around efficiency, freight mix and potential returns on that sizeable AI budget, while still keeping the well flagged insurance and valuation risks in view.
Landstar System's current analyst script points to revenues of US$6.7b and earnings of US$296.5 million by 2029, based on an assumed 10.0% yearly revenue growth rate and an earnings increase of about US$164.8 million from US$131.7 million today.
Uncover why Landstar System's fair value indicates a 24% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
Not every analyst views Landstar System’s AI spending as a clear win. The more cautious forecasters were already baking in revenue of about US$6.6b and earnings near US$288.1 million by 2029, with a lower P/E than the consensus path. You can compare those pre earnings views and decide which story feels closer to yours.
Explore another Landstar System fair value estimate, including one that suggests it could be worth just $181.12.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so rely on your own analysis and judgment.
- A great starting point for your Landstar System research is our analysis highlighting 4 key rewards that could impact your investment decision.
- See our latest analysis for Landstar System. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, which makes it easier to evaluate Landstar System's overall financial health at a glance.
Looking For More Investment Ideas Beyond Landstar System?
If Landstar System has sharpened your thinking about earnings quality, balance sheet strength and dividends, use that same checklist to scan a broader watchlist. The Simply Wall St Screener can help you quickly filter for businesses that match the traits you care about most.
- If capital preservation and stability matter to you, start by scanning a group of resilient companies through the 30 resilient stocks with low risk scores.
- For investors hunting for quality at a reasonable price, consider using a filter focused on mispriced opportunities with solid fundamentals via the 19 high quality undiscovered gems.
- If dependable income is a priority, you can shortlist potential payout candidates by reviewing a curated 6 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com