


Savaria (TSX:SIS) is back in focus after reporting record Q3 adjusted EBITDA, with higher sales and net income, as well as reiterated five-year growth and margin targets, drawing fresh attention from investors.
Investors have responded to the Q3 release with renewed interest, with Savaria’s share price up 4.6% over the past week and 31.1% year to date. The 1 year total shareholder return of 37.5% and 3 year total shareholder return of about 13x indicate strong longer term momentum.
Scan how Savaria’s momentum compares to other potential breakouts by running your eye over our hand picked list of 6 high quality undervalued stocks.
After that run, the real tension is the gap between Savaria’s CA$30.22 share price and a valuation range that points higher. How wide is the discount once fair value is pinned down?
Most Popular Narrative: 15% Undervalued
On the analyst consensus Narrative on Simply Wall St, Savaria screens as undervalued, with a fair value of about CA$35.69 against the recent CA$30.22 close. That gap is tied directly to how earnings and margins are expected to evolve over the rest of the decade.
Available liquidity of over CA$320 million, leverage below 1x net debt to EBITDA, and stated capacity to deploy about CA$200 million into tuck in acquisitions while maintaining a leverage ceiling of 2x create room for Savaria to add acquired revenue and potentially higher margin businesses that can scale earnings.
See why 81 investors see Savaria as 15% undervalued.
Using a 7.65% discount rate, the Narrative brings those forecast cash flows and profit margins back to today to land on that CA$35.69 figure. This implies the current share price reflects only part of the expected earnings path rather than the full set of assumptions on revenue growth, margin mix, and acquisition firepower.
Result: Fair Value of CA$35.69 (UNDERVALUED)
Still, the Savaria story can wobble if revenue growth trails the CA$1.6b 2030 path, or if Patient Care margins stay under pressure from input costs.
Find out about the key risks to this Savaria narrative.
Another View: What Savaria’s P/E Is Telling You
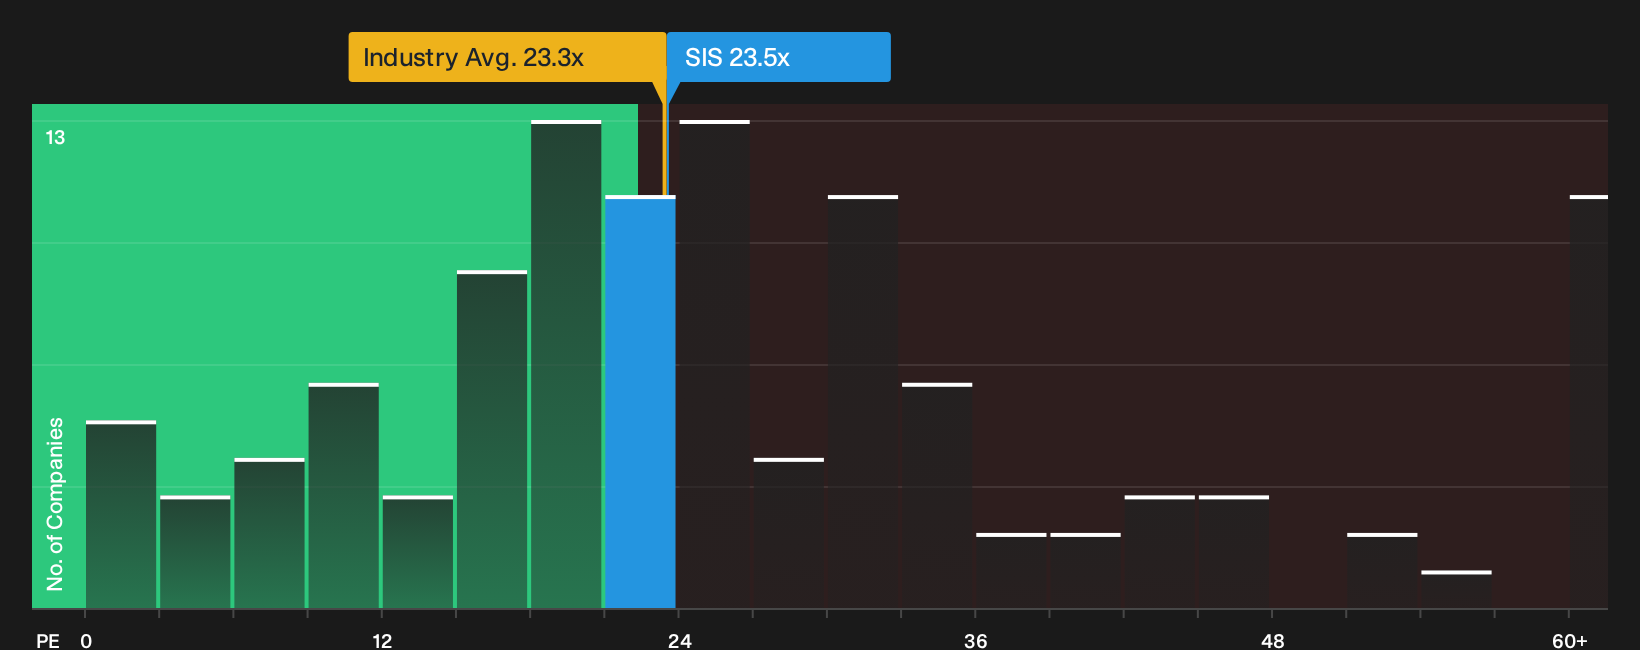
The first story frames Savaria as undervalued on future cash flows. On simple earnings, the picture is less generous. The stock trades on a P/E of 23.9x, which is above the North American Machinery industry at 23.3x, peers at 21.1x, and its own fair ratio of 20.5x. That premium suggests less margin of safety if sentiment cools.
To see how this earnings based view stacks up against the cash flow narrative, and where that leaves potential room for error, See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Mixed signals on Savaria so far. If you want to move quickly and build your own view from the ground up, consider both sides by checking the 5 key rewards and 1 important warning sign.
Ready for more ideas beyond Savaria?
If Savaria has your attention, do not stop here. Broaden your watchlist with a few targeted ideas that could sharpen your next move.
- Zero in on companies that pair quality with potential mispricing by scanning our hand picked list of 6 high quality undervalued stocks.
- Build a steadier income stream by reviewing a curated group of income focused opportunities in the 3 dividend fortresses.
- Dial down portfolio stress and spotlight sturdier businesses through the 9 resilient stocks with low risk scores before the crowd catches on.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com