


- RingCentral announced new AI tools for RingCX that let contact centers supervise, score, and forecast both AI and human agents from one dashboard, while adding AI Onboarding, mobile access, and a Microsoft Teams integration.
- The single workforce view across AI Receptionist, AIR Pro, and human staff shifts RingCentral from just call routing toward deeper operational control over customer service costs and capacity planning.
- Next, the focus will be on how RingCentral's broader investment narrative intersects with unified AI and human workforce management in RingCX.
Scan 53 AI infrastructure stocks to find other platforms like RingCentral that are building the plumbing for AI driven customer service and contact center automation.
RingCentral Investment Narrative Recap
To own RingCentral, you need to believe that a contact center platform built around voice AI, high margin subscriptions and free cash flow can stay relevant even if revenue growth runs in the mid single digits. The analyst consensus Narrative on Simply Wall St leans heavily on execution against free cash flow guidance of about US$620m to US$630m and high single digit GAAP operating margins.
The biggest near term swing factor is whether softer billings and modest top line forecasts settle into a slower but steady subscription trajectory or point to demand pressure. On the risk side, the Levi & Korsinsky investigation and RingCentral’s high debt load could both tug on margins and constrain flexibility if legal or funding conditions turn less friendly.
The new RingCX AI workforce management capabilities, including unified supervision and scoring of AI agents like AIR and AIR Pro alongside human staff, plug directly into the contact center cross sell and retention catalyst. If customers lean into these richer workflows, that supports the push toward higher ARPU AI cohorts and aligns with subscription gross margins above 80%.
AI Onboarding for RingCX and the Microsoft Teams integration matter for a different reason. They test whether RingCentral can shorten deployment times, keep configuration friction low and attach its contact center into tools customers already use. Execution here influences how much of the 40 billion minutes and broader AI portfolio actually convert into durable, higher value recurring contracts.
RingCentral’s current analyst setup assumes revenue grows at 5.5% a year, taking the top line to about US$3.1b and earnings to US$241.4m by 2029, compared with earnings today of US$656.8m. This implies an earnings decline of roughly US$415m over that period.
Uncover how RingCentral's fair value indicates a 34% potential upside to its current price before the rest of the market closes that gap.
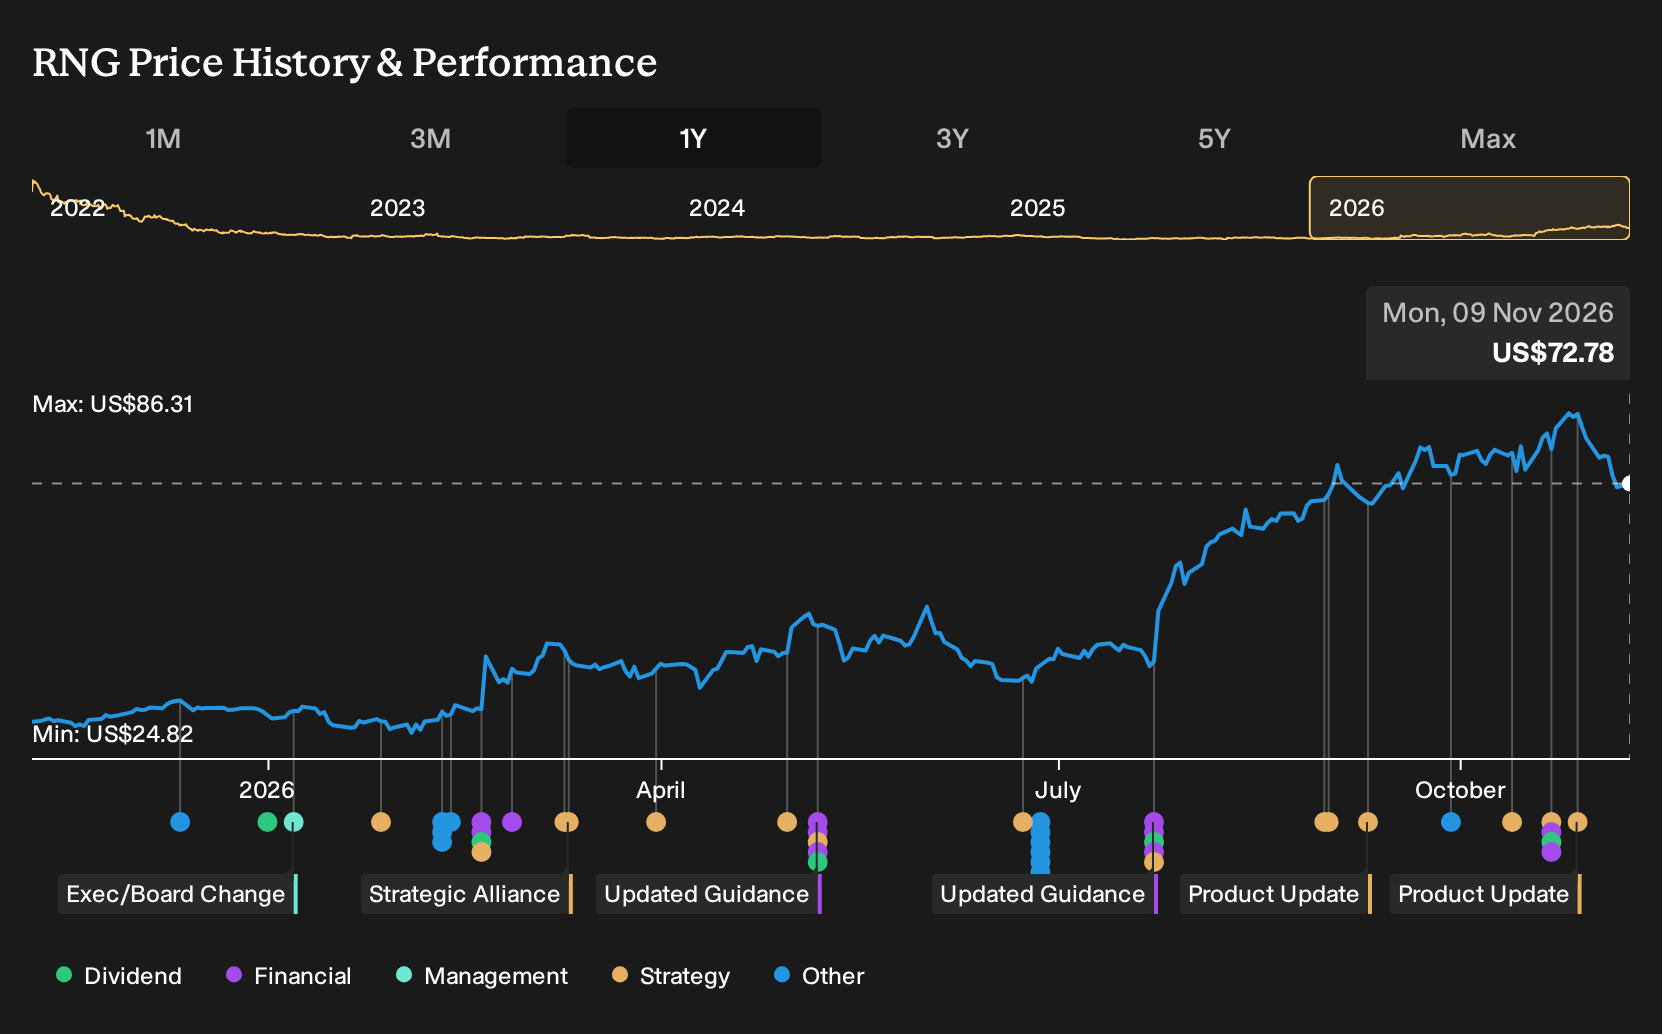
Exploring Other Perspectives
One bearish twist on RingCentral focuses on heavy AI R&D spend. The lowest analysts worry that with revenue growth assumptions of about 4.3% a year and 2029 earnings near US$195.9m, AI monetisation risk is high. Those views sit well below consensus and could shift as the new RingCX tools play out.
Explore 3 other RingCentral fair value estimates, including one that suggests it could be worth just $97.86.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment outcomes rarely come from following the herd, so go with your instincts.
- A great starting point for your RingCentral research is our analysis highlighting 4 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for RingCentral. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate RingCentral's overall financial health at a glance.
Looking For More Investment Ideas Beyond RingCentral?
If RingCentral has you rethinking how AI heavy platforms fit in your portfolio, it can help to line it up against other opportunities that share strong fundamentals or very different risk profiles. The Simply Wall St Screener lets you filter for traits that actually match your priorities rather than forcing every stock into the same mold.
- For investors who care most about financial resilience and clean balance sheets, start with this curated list of solid balance sheet and fundamentals (25 results) to see which businesses may handle shocks more comfortably.
- If value is your anchor and you want quality companies trading below what their fundamentals imply, work through this focused 33 high quality undervalued stocks and compare them to where RingCentral sits on your watchlist.
- For those who prefer cash returns today as well as potential price upside, scan this hand picked 6 dividend fortresses and see which income plays deserve a closer look next to growth oriented names.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com