


FirstCash Holdings (FCFS) drew fresh attention on October 28, 2026, after its board expanded the existing equity repurchase authorization by $200 million, increasing the total buyback capacity to $350 million.
Against that backdrop, FirstCash Holdings trades at US$187.83, with the share price up 1.16% on the day yet down 12.11% over the past month and 9.86% over the last quarter. Even so, the year-to-date share price return is 19.80% and the 5-year total shareholder return reaches 171.49%, suggesting shorter term momentum has cooled while the longer term record remains strong.
Spot 33 high quality undervalued stocks where sizable buyback firepower and stronger recent earnings growth, like FirstCash Holdings, could be pointing to management confidence.FirstCash Holdings now trades roughly 24% below the average analyst price target, while management commits US$350 million to buybacks. Is the market rightly cautious, or is it underpricing that conviction?
Price-to-Earnings of 19.8x: Is it justified?
FirstCash Holdings closed at $187.83 while trading on a P/E of 19.8x, and that sits well above both its industry and peer averages.
The P/E ratio compares the share price with earnings per share. For a lender and pawn operator like FirstCash Holdings, it captures how much investors are willing to pay today for each dollar of current profit, which often reflects expectations about future earnings, perceived risk, and the quality of those earnings.
In this case, the market is applying a P/E of 19.8x compared with the US Consumer Finance industry average of 8.4x and the peer average of 12.5x. The estimated fair P/E from the SWS fair ratio work is 15.1x, which is lower than the current trading multiple and indicates a level the market could move toward if sentiment or expectations change.
Explore the SWS fair ratio for FirstCash Holdings.Result: Price-to-Earnings of 19.8x (OVERVALUED)
Still, the FirstCash Holdings story could be challenged if earnings momentum slows, or if regulators tighten rules around pawn lending and consumer finance products.
Find out about the key risks to this FirstCash Holdings narrative.
Another View on FirstCash Holdings: Cash Flows Paint a Harsher Picture
FirstCash Holdings looks expensive on earnings, and the SWS DCF model points in the same direction. The stock trades at $187.83 while the model estimates future cash flow value at $97.44, which implies a meaningful premium that leaves less room if anything goes wrong.
That gap can matter for you because cash flows tend to anchor long term value more than short term sentiment. When the share price sits far above an intrinsic estimate, any disappointment on growth, regulation, or credit quality can affect both the multiple and the DCF story at the same time.
Look into how the SWS DCF model arrives at its fair value.
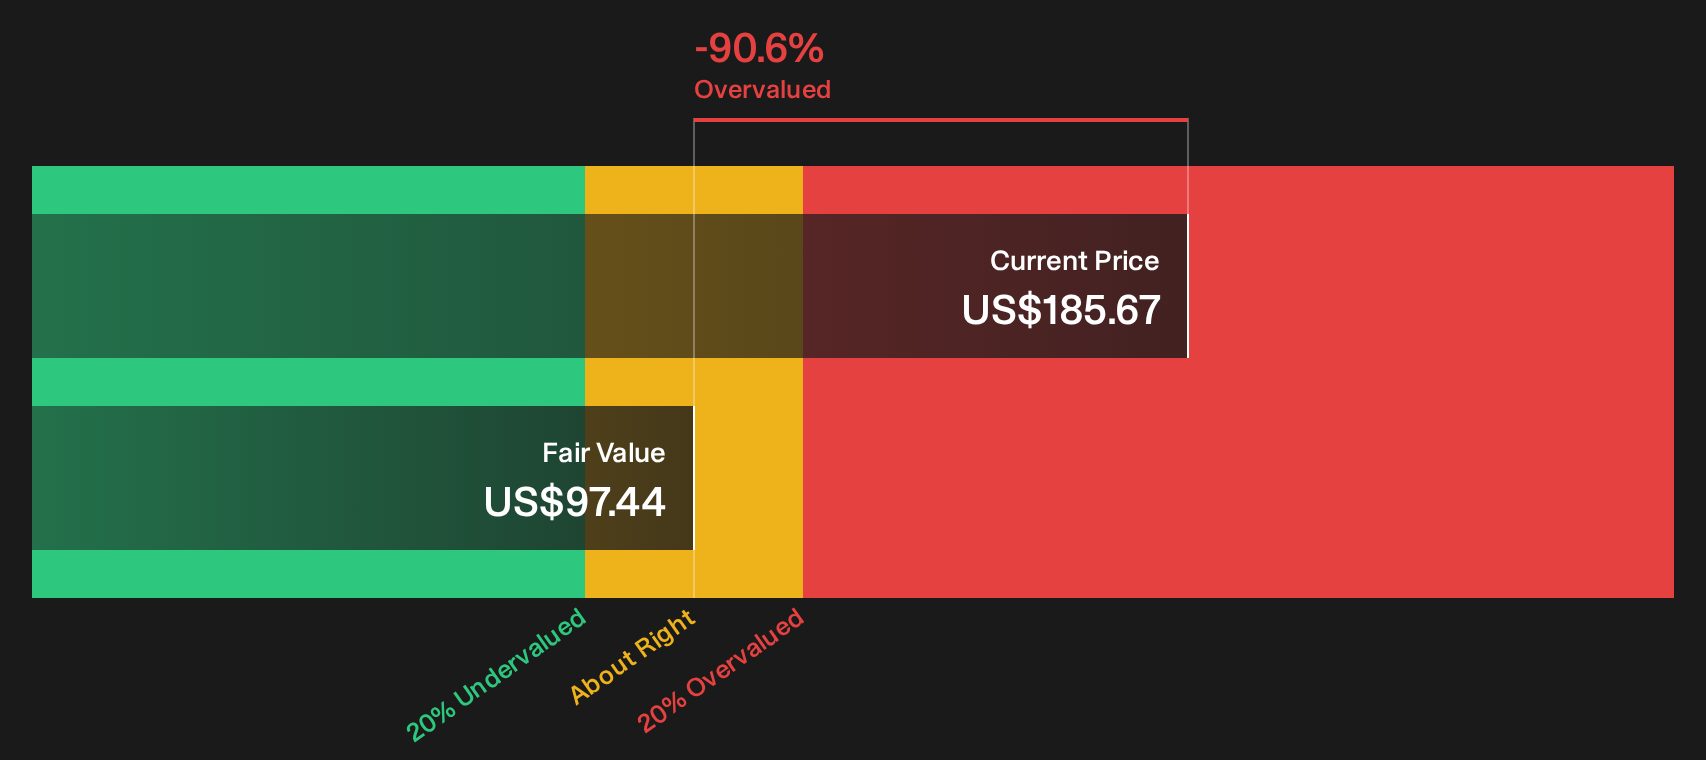
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out FirstCash Holdings for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 33 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
The mix of rich valuation signals and active buybacks around FirstCash Holdings can feel confusing at first glance, so move fast and test the data against your own instincts. Balance what the market seems to be rewarding with what could go wrong by weighing the 3 key rewards and 2 important warning signs.
Looking for more investment ideas beyond FirstCash Holdings?
Once you have a view on FirstCash Holdings, do not stop there. Broader opportunity often sits in places the market has not crowded yet.
- Spot potential mispricings by reviewing a 33 high quality undervalued stocks that match strong fundamentals with more modest expectations.
- Lock in income-focused ideas by scanning a 6 dividend fortresses that combine higher yields with disciplined payout profiles.
- Sleep easier during rough markets by filtering a 30 resilient stocks with low risk scores that carry more resilient financial and risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com