


Hammond Power Solutions (TSX:HPS.A) just posted fresh third quarter results that put sales at CA$446.26 million and net income at CA$27.7 million, drawing new attention to the transformer manufacturer.
The third quarter release lands after a sharp retreat in Hammond Power Solutions’ share price over the past month, with a 30-day share price return down 32.57% and a 90-day move down 23.12%. Even though the year-to-date share price return is still up 27.85% and the 5-year total shareholder return is extremely high, this points to strong long term momentum despite recent volatility around CA$207.75.
Scan beyond Hammond Power Solutions and compare its recent share price pullback with other power grid technology players screened as 42 power grid technology and infrastructure stocks.
Bulls see Hammond Power Solutions as a quality grid supplier now on sale, while bears argue the run has already gone too far. Which camp do the current valuation numbers support?
Most Popular Narrative: 46% Undervalued
On the analyst consensus Narrative on Simply Wall St, Hammond Power Solutions screens as materially undervalued, with a fair value of CA$383.50 against the latest close at CA$207.75. This frames the recent pullback very differently from the price action alone.
The ramp-up and optimization of expanded manufacturing capacity in Monterrey, which has already supported record shipment volumes and contributed to operating leverage, can continue to lift Hammond Power Solutions revenue and support higher earnings as more of the enlarged $1.3b North American capacity is utilized.
See why 39 investors see Hammond Power Solutions as 46% undervalued.
Result: Fair Value of CA$383.50 (UNDERVALUED)
Still, Hammond Power Solutions faces real pressure if tariffs and input costs remain elevated or if data centre and industrial project demand softens from current levels.
Find out about the key risks to this Hammond Power Solutions narrative.
Another View: Multiples Paint A Different Picture
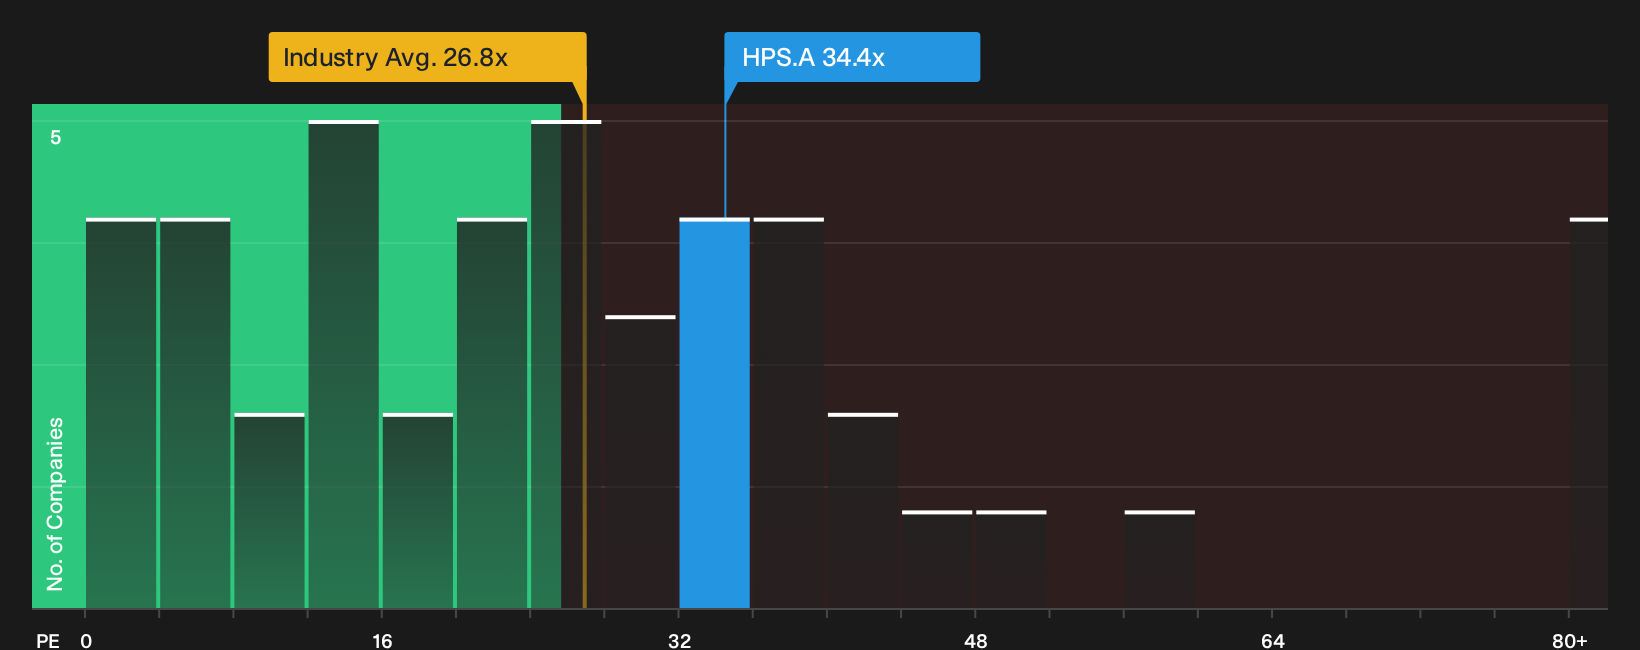
A second lens on Hammond Power Solutions uses its P/E ratio rather than fair value estimates. The shares trade on 34.4x earnings, which is higher than the North American Electrical industry at 26.8x but below peers at 36.1x and a fair ratio of 45.7x. Is that a cushion or a warning sign for you?
Before leaning too heavily on this single metric, it is worth stress testing the assumptions around earnings, peer quality and what could pull the P/E closer to that fair ratio over time. See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment in this Hammond Power Solutions story cuts both ways, with clear risks on one side and clear potential on the other. Move fast, examine the key metrics yourself, and then weigh the 3 key rewards and 3 important warning signs.
Looking for more investment ideas beyond Hammond Power Solutions?
If Hammond Power Solutions has your attention, do not stop there. Use the Simply Wall St screener to spot other opportunities before they move.
- Target resilient compounding potential by checking companies with robust cash flows and financial strength through the 6 high quality undervalued stocks.
- Build a steadier portfolio core by reviewing companies with reliable payouts and strong yields in the 3 dividend fortresses.
- Protect against downside shocks by focusing on businesses with stronger balance sheets and lower risk profiles using the 9 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com