


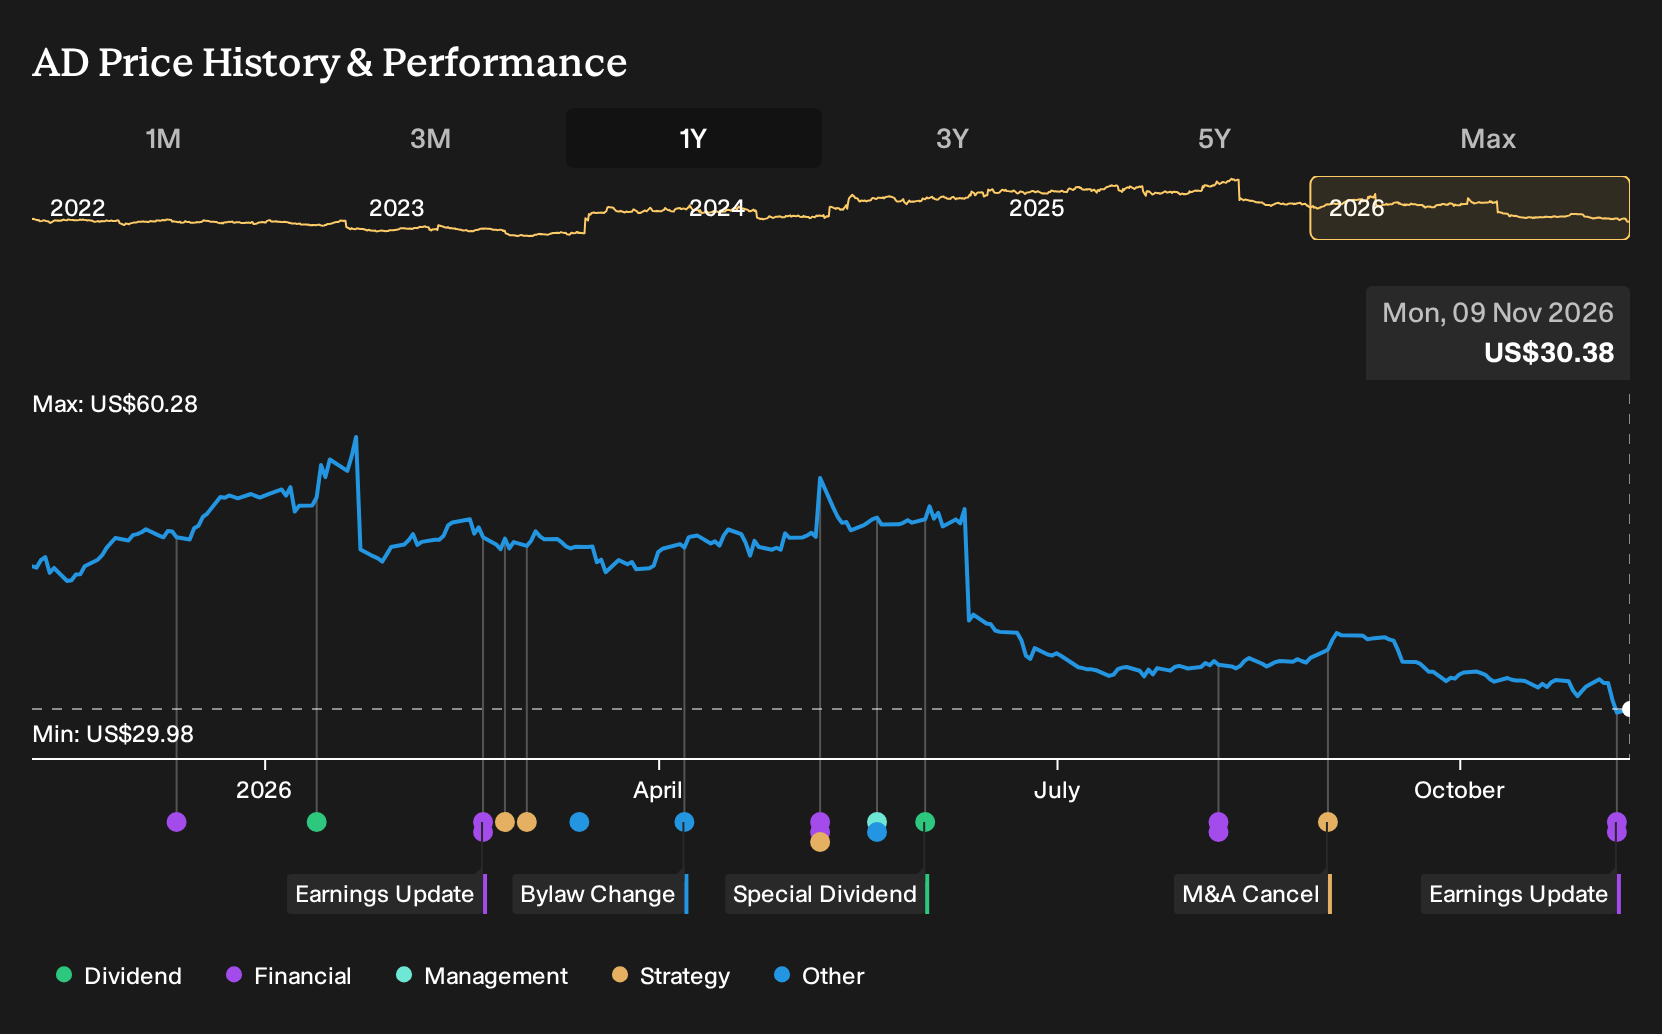
- Array Digital Infrastructure reported Q3 2026 sales of US$52.48 million and revenue of US$53.87 million, shifting from a net loss a year earlier to net income of US$68.8 million, and reaffirmed full year 2026 operating revenue guidance of US$205 million to US$215 million.
- The nine month period to September 30, 2026 showed revenue of US$159.95 million and net income of US$605.29 million, which materially reframes Array Digital Infrastructure’s earnings profile as it operates its U.S. tower portfolio and pursues spectrum monetization.
- The focus now is on how Array Digital Infrastructure’s sharp swing to profitability could reshape the existing investment narrative built around tower cash flow.
Scan how Array Digital Infrastructure’s sharp earnings swing compares with peers by reviewing the hand picked tower and infrastructure stocks in our 42 power grid technology and infrastructure stocks
Array Digital Infrastructure Investment Narrative Recap
To own Array Digital Infrastructure, you need to believe the tower focused model and spectrum monetization can support a cleaner, more predictable earnings mix after the exit from prior wireless operations and the loss of DISH revenue. The sharp move to net income in Q3 2026 and across the first nine months highlights that shift, but it does not remove execution risk on leasing up towers.
Right now, the key short term catalyst is how quickly Array Digital Infrastructure can deepen carrier relationships, improve tenancy on its 4,400 towers and keep cash site rental trends aligned with the analyst consensus Narrative on Simply Wall St. The biggest risk is that organic leasing and new tenants do not fill the DISH gap, which could leave operating revenue and margins more exposed if spectrum proceeds and partnership income moderate.
The reaffirmed 2026 operating revenue guidance of US$205 million to US$215 million sits at the center of this latest update. Management effectively noted that, despite Q3 and year to date swings in net income and the contribution from spectrum monetization and partnerships, their full year top line expectations remain intact.
For catalysts, that guidance matters more than the confirmation of the Q3 earnings date or the earnings call itself. It gives investors a concrete range to weigh against the analyst consensus Narrative on Simply Wall St, which already assumed revenue pressure and future earnings declines. The execution question is whether tower leasing, spectrum monetization and partnership income can keep reported figures inside that band while Array Digital Infrastructure manages tenant churn and non cash earnings items.
What The Array Digital Infrastructure Forecasts Really Assume
Array Digital Infrastructure's story now rests on analyst expectations that are pulling in the opposite direction to the recent profit swing. The Simply Wall St report links the current share price and consensus target directly to a model that bakes in lower revenue, thinner margins and meaningfully smaller earnings several years out.
Analysts are building in a 1.6% annual decline in Array Digital Infrastructure's revenue over the next three years, paired with a drop in profit margins from 310.9% today to 16.6% within roughly that same period. Current earnings are cited at US$663.8 million, with consensus forecasts pointing to US$33.7 million of profit by 2029. That implies an earnings reduction of about US$630 million between today and the 2029 estimate year.
Those assumptions feed directly into how the stock is being framed. To line up with the analyst price target, investors would need to accept that by 2029, Array Digital Infrastructure generates US$203.3 million of revenue, earns US$33.7 million and trades on a P/E multiple of 137.6x. That compares with a current P/E of 4.5x and is well above the 18.4x cited for the broader US wireless telecom industry in the same report.
Array Digital Infrastructure's narrative projects US$203.3 million of revenue and US$33.7 million of earnings by 2029. This assumes revenue will decline by 1.6% a year and earnings will fall by about US$630 million from the current US$663.8 million level.
Uncover why Array Digital Infrastructure's fair value highlights a 43% potential upside to its current price that could close more quickly than the market expects.
Exploring Other Perspectives
One alternate view leans heavily on the risk that Array Digital Infrastructure has already used most of its spectrum upside. Bearish analysts were pencilling in revenue of about US$194.0 million and earnings of US$39.5 million by 2029 before this Q3 surprise. That is a more pessimistic story, and it shows how far opinions can spread. Treat this as an invitation to compare those cautious forecasts with other estimates and decide which version of the future feels more reasonable to you, knowing that all of these models were built before the latest earnings and guidance reaffirmation.
Explore 2 other Array Digital Infrastructure fair value estimates, including one that suggests it could be worth just $31.19.
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Array Digital Infrastructure research is our analysis highlighting 4 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Array Digital Infrastructure. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Array Digital Infrastructure's overall financial health at a glance.
Looking for more investment ideas beyond Array Digital Infrastructure?
Once you have a handle on Array Digital Infrastructure, it can help to widen the lens and compare it with other businesses that fit different profiles using the Simply Wall St Screener.
- If you want potential upside without ignoring quality, scan a curated set of 33 high quality undervalued stocks that combine solid fundamentals with compressed valuations.
- If resilience is your priority, filter for 30 resilient stocks with low risk scores that score well on financial strength and business stability, and then weigh them against your own risk tolerance.
- If balance sheet strength is non negotiable for you, start with our list of solid balance sheet and fundamentals (25 results) to focus on companies with cleaner finances before you go deeper on the story.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com