


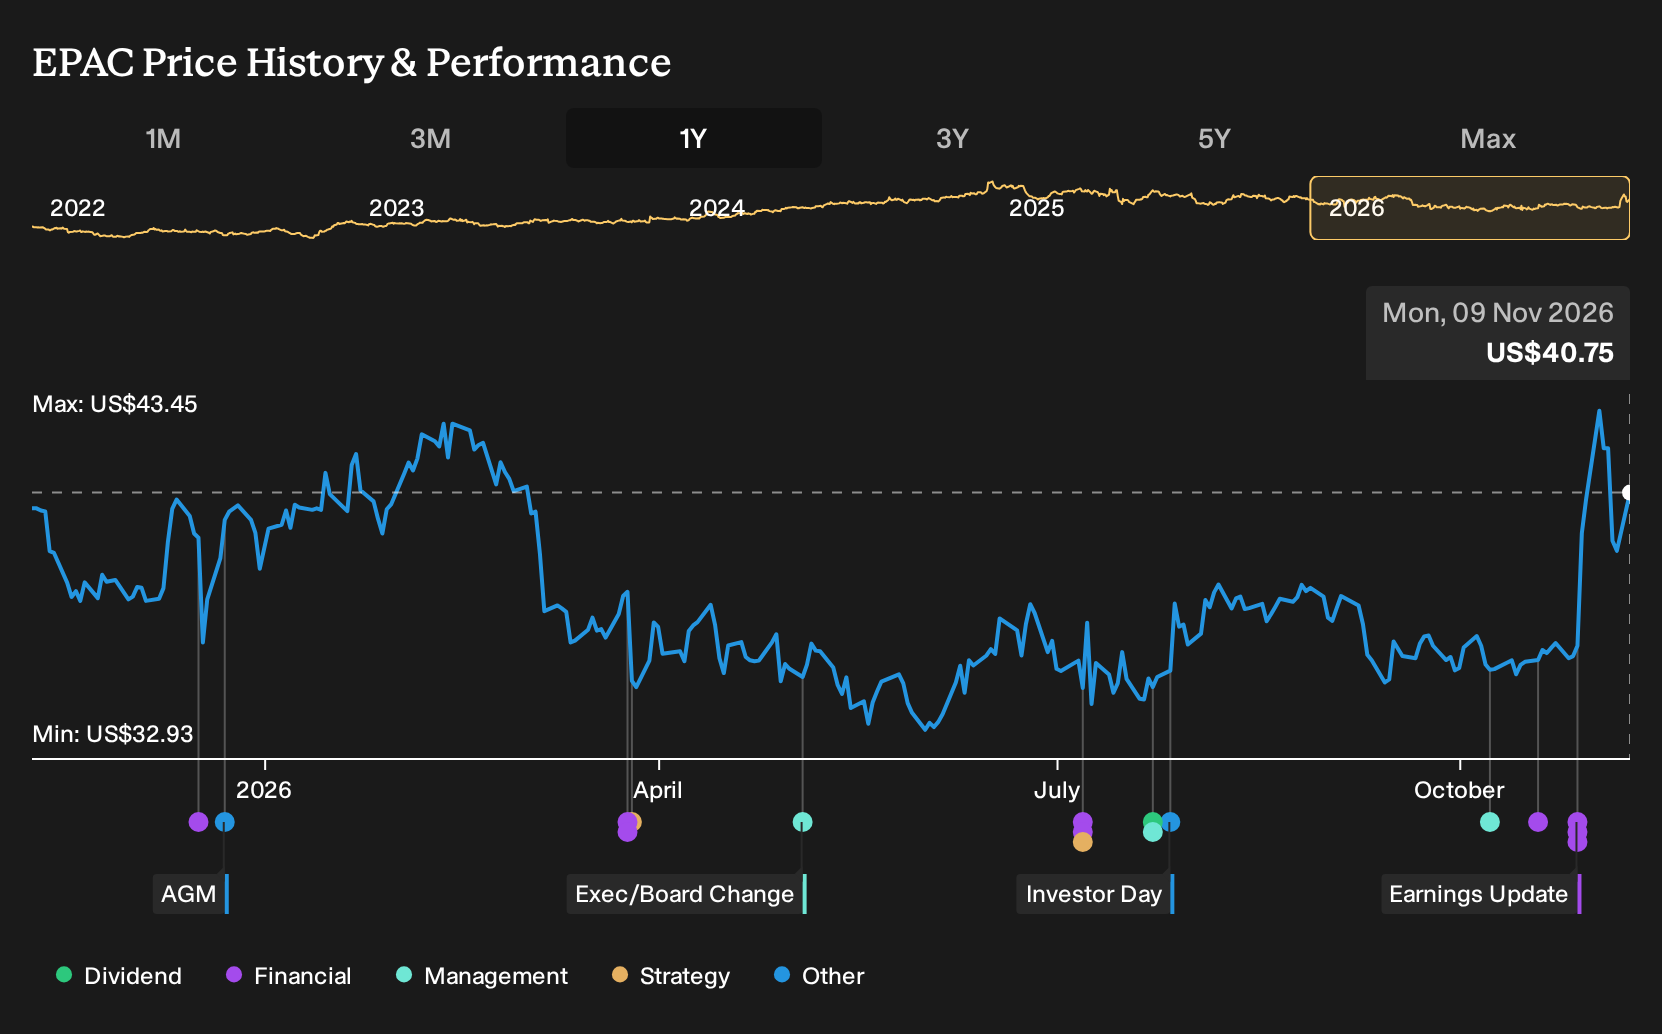
- Enerpac Tool Group reported fourth quarter 2026 sales of US$185.7 million and full year sales of US$652.3 million, with basic earnings per share from continuing operations of US$0.48 for the quarter and US$1.73 for the year. The company also issued 2027 net sales guidance of US$825 million to US$845 million.
- The firm also filed a US$22.19 million shelf registration tied to an ESOP related Class A share offering and scheduled a conference appearance by its CEO and CFO. Together, these developments highlight an emphasis on employee ownership, capital flexibility, and active communication of its operating outlook.
- We will now examine how Enerpac Tool Group's 2027 sales outlook may influence the investment narrative around growth, margins, and capital deployment.
Scan beyond Enerpac Tool Group and compare its guidance driven story with a curated group of industrials on the move using the 33 high quality undervalued stocks.
Enerpac Tool Group Investment Narrative Recap
To own Enerpac Tool Group, you need to be comfortable with a story built on industrial tool demand, infrastructure and energy projects, and disciplined cost work. The latest quarter shows sales of US$185.7 million and full year sales of US$652.3 million, with earnings per share roughly steady year on year, so the core engine is still grinding forward rather than resetting.
The analyst consensus narrative on Simply Wall St leans on future earnings and margin improvement, but the short term hinge remains execution on that 2027 net sales outlook of US$825 million to US$845 million. The biggest near term risk is softer industrial activity or tariffs squeezing profitability before restructuring, product launches, and M&A integration benefits show through.
The 2027 net sales guidance is the announcement that really matters here. Management is effectively telling you what sort of top line they think Enerpac Tool Group can support as infrastructure, power, and energy transition projects move through, on top of recent restructuring in EMEA and ongoing new product introductions.
If you see that guidance as realistic, then your focus probably shifts to whether SFE Group and prior deals can be integrated cleanly enough to support it, especially given past mixed acquisition performance. If you are more cautious, that same guidance becomes a yardstick for risk, particularly if tariffs, Western European demand, or execution missteps pressure the margin story that underpins the current analyst narrative.
Enerpac Tool Group's current analyst story centers on a path to US$727.5 million in revenue and US$123.6 million in earnings by 2029. That profile assumes revenue grows at about 4.7% per year and earnings rise by roughly US$30.3 million from the US$93.3 million reported today.
Uncover how Enerpac Tool Group's fair value indicates an 18% potential upside to its current price, while that discount to Enerpac Tool Group's outlook remains open.
Exploring Other Perspectives
Three fair value estimates from the Simply Wall St Community cluster between about US$44.90 and US$54 per share, so you see a tight band rather than wild disagreement on Enerpac Tool Group. Those views were set before the 2026 earnings, 2027 sales guidance, tariff exposure, and M&A execution risks or catalysts fully played through. Use them as starting points and compare several alternative angles before deciding how compelling the story looks to you.
Explore 2 other Enerpac Tool Group fair value estimates, including one that suggests it could be worth just $44.90.
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Enerpac Tool Group research is our analysis highlighting 2 key rewards that could impact your investment decision.
- See our latest analysis for Enerpac Tool Group. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Enerpac Tool Group's overall financial health at a glance.
Looking For More Ideas Beyond Enerpac Tool Group?
If Enerpac Tool Group has sharpened your interest in industrial stories but you want a broader watchlist, the Simply Wall St Screener can help you quickly surface other opportunities that match your risk and income preferences.
- For investors who want capital growth potential backed by fundamentals, consider a curated set of companies trading below their estimated value through the 33 high quality undervalued stocks.
- If resilience and balance sheet strength matter most to you, focus on businesses with dependable financial structures by scanning the list of solid balance sheet and fundamentals (25 results).
- For readers who like the idea of strong operations that are still under the radar, broaden your research with a group of lesser known but fundamentally sound stocks using the 19 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com