


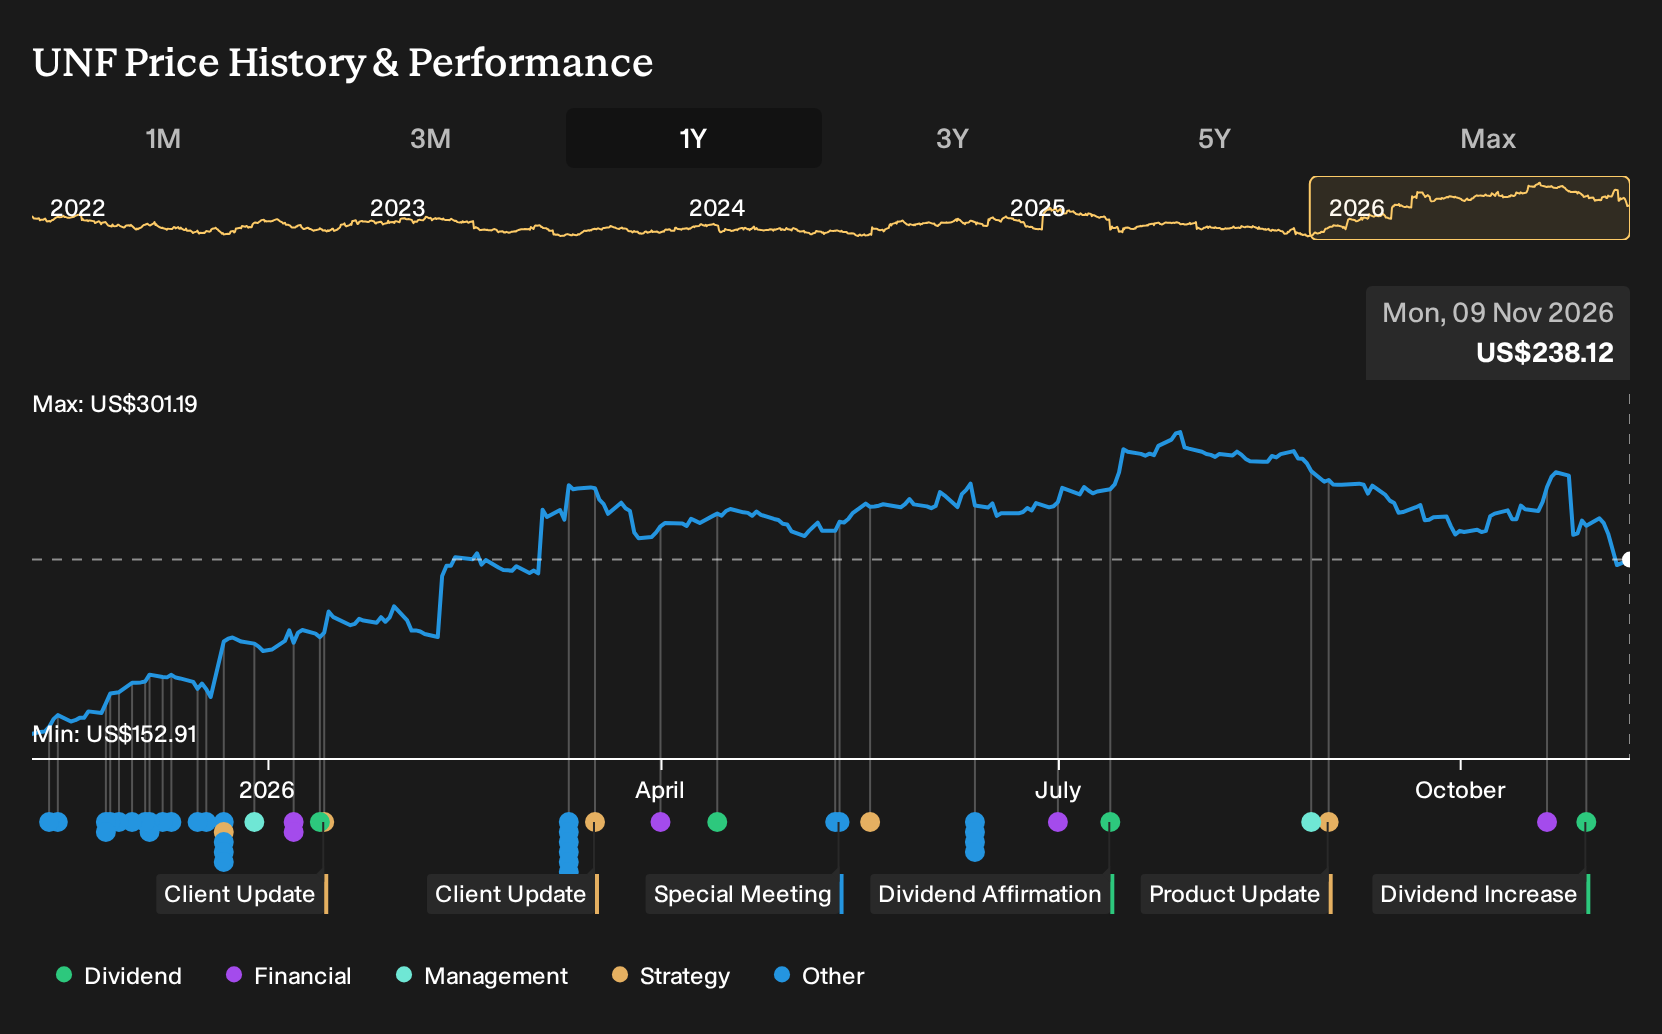
- UniFirst's Board of Directors approved higher quarterly cash dividends, setting payments at $0.375 per share for Common Stock and $0.300 for Class B shares, payable on December 15, 2026 to investors of record on November 13, 2026.
- The richer payout signals management's willingness to return more cash to shareholders at a time when UniFirst is still funding ERP, service and integration initiatives that affect margins and capital allocation choices.
- We now examine how UniFirst's investment narrative is affected by this higher quarterly dividend commitment from the Board.
Compare UniFirst's richer dividend move with other income focused opportunities by checking the hand picked 6 dividend fortresses that are also returning substantial cash to shareholders.
UniFirst Investment Narrative Recap
To own UniFirst, you need to be comfortable with a business that is in the middle of a heavy investment phase, particularly in ERP and service capabilities, while still dealing with higher health care, legal and tariff costs. The analyst consensus Narrative on Simply Wall St highlights those projects as potentially supporting margins, but execution and timing remain key.
At the moment, the main near-term catalyst is progress on ERP modules going live and on the planned Cintas integration, because both tie directly into future cost efficiency. The biggest risk is that costs from technology, tariffs and one-off items persist, leaving net margins under pressure. The higher dividend does not materially change that trade-off in the short term.
The dividend increase itself is the most relevant recent announcement, because it interacts directly with UniFirst’s capital allocation while ERP and integration work are still underway. A richer payout shifts more cash to investors at a time when analysts, according to the analyst consensus Narrative on Simply Wall St, already incorporate expected earnings growth of about 17.7% a year.
For investors, the practical question is how this higher quarterly dividend fits alongside other moving parts such as elevated P/E multiples compared with industry averages, weaker recent net profit margins and planned cost synergies from the Cintas deal. The new payout does not remove execution risk on technology rollouts, service improvements or tariff exposure, although it may make the stock more relevant to some income-focused portfolios.
UniFirst's narrative projects US$2.8b revenue and US$193.3m earnings by 2029. This is based on an assumption of 3.7% yearly revenue growth and an earnings increase of about US$77.5m from current earnings of US$115.8m.
Uncover why UniFirst's fair value indicates a 15% potential upside to its current price before the market closes that gap.
Exploring Other Perspectives
One bullish twist on UniFirst comes from analysts who treat the Cintas merger as the real catalyst. Before this dividend news, the most optimistic forecasts were for revenue of about US$2.8b and earnings of roughly US$191.9m by 2029. Those analysts see more room for upside, and their views could shift again as this richer dividend becomes established.
Explore 2 other UniFirst fair value estimates, including one that suggests as much as 18% upside from the current price.
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your UniFirst research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for UniFirst. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate UniFirst's overall financial health at a glance.
Looking for more UniFirst-sized investment ideas?
Once you have formed a view on UniFirst, it can help to line it up against other opportunities that offer different mixes of quality, risk and income using the Simply Wall St Screener.
- If you want resilience first and foremost, start with a group of companies filtered for stronger balance sheets and fundamentals by reviewing the list of solid balance sheet and fundamentals (25 results).
- For investors focused on high quality at a reasonable entry point, compare UniFirst with a 33 high quality undervalued stocks that combines solid fundamentals with more attractive valuations.
- If you are hunting for future leaders before they are widely followed, cast a wider net across a 19 high quality undiscovered gems that still shows strong underlying business strength.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com