


Turning Point Brands (TPB) landed back on investor radars after third quarter 2026 results showed sales of US$151.1 million, higher than a year earlier, while net income and earnings per share declined sharply.
The latest earnings release and dividend affirmation have landed against a tricky backdrop for Turning Point Brands shareholders, with the 1-day share price return down 3.98% and the 7-day share price return down 4.84% even after a 10.25% gain over the past month. Despite that short-term bounce, share price momentum has faded over 90 days with a 28.18% decline, and the year-to-date share price return down 42.62%. However, the 3-year total shareholder return of about 3x and 5-year total shareholder return of 64.52% still point to a very different long-run experience for investors who have held through past swings.
Spot patterns like Turning Point Brands’ recent share-price swings and earnings shift, then scan a curated list of 33 high quality undervalued stocks showing stronger fundamentals and potential mispricing.Turning Point Brands has moved sharply in both directions, with strong recent revenue data alongside a sharp share price pullback. Is that a setup to step in now, or does patience offer a better entry point as valuation comes into focus?
Most Popular Narrative: 47% Undervalued
On the analyst consensus Narrative on Simply Wall St, Turning Point Brands screens as undervalued, with a fair value of $118.50 against a last close of $63.26. This puts the focus squarely on how Modern Oral develops from here.
Strong growth in the Modern Oral nicotine pouch segment, with FRE and ALP net sales reaching $68 million and representing 48% of total revenue in Q2 2026 after very large year-over-year growth, keeps Turning Point Brands leveraged to a rising share of nicotine consumption and can continue to reweight the business mix toward higher revenue and gross margin.
See why 7 investors see Turning Point Brands as 47% undervalued.
Result: Fair Value of $118.50 (UNDERVALUED)
Still, the Modern Oral push at Turning Point Brands relies on heavy spending and new U.S. manufacturing, so any delay or regulatory setback could quickly challenge the case that the stock is undervalued.
Find out about the key risks to this Turning Point Brands narrative.
Another View on Turning Point Brands’ Valuation
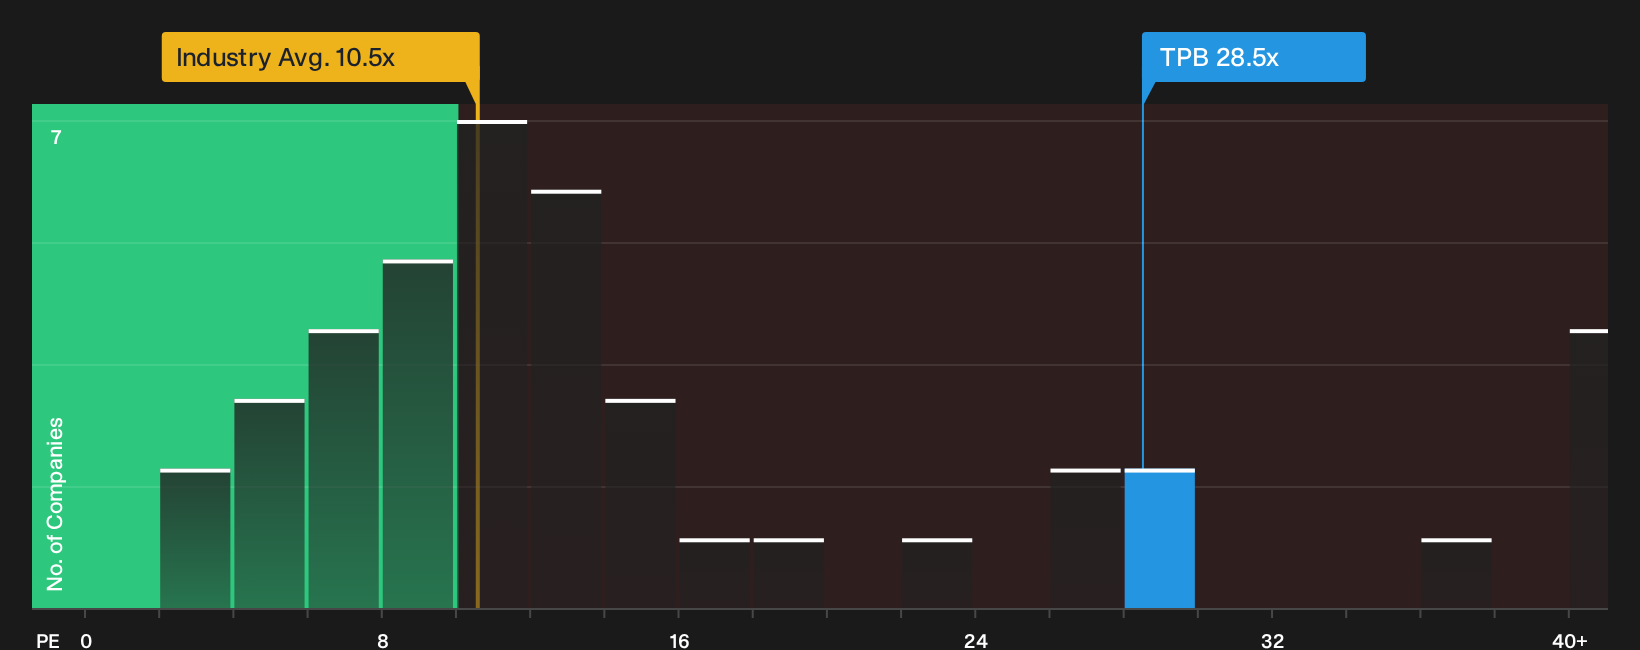
The analyst narrative leans on earnings forecasts and a P/E of 22.5x in 2029. Step back and the current P/E of 28.5x looks expensive against both US peers on 24.4x and the global tobacco group on 10.5x, even if a fair ratio of 40.1x suggests the market could move higher over time. Investors may wish to consider whether this is a mispricing or a margin of error they are comfortable with.
For a closer look at how this pricing gap lines up with earnings power and sector norms, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on Turning Point Brands so far. If sentiment feels split, review the data yourself and weigh the 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Turning Point Brands?
If Turning Point Brands has sharpened your focus on valuation and risk, do not stop here. Broaden your watchlist now and give yourself more options before the next move hits.
- Target steady cash generators and scan a curated pool of robust dividend payers through 6 dividend fortresses built for income-focused portfolios.
- Spot potential mispricing early and review a focused set of 19 high quality undiscovered gems that combine strong fundamentals with limited investor attention.
- Dial down portfolio stress by analysing companies in the 30 resilient stocks with low risk scores that pair resilience scores with solid financial profiles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com