


Diageo (LSE:DGE) just wrapped its 5 November AGM with a busy agenda, combining fresh board appointments, a revised set of articles of association and a quarterly sales update.
Against that AGM backdrop, Diageo’s share price has climbed over recent weeks, with a 30 day share price return of 14.77% and a year to date gain of 16.95%, suggesting momentum has picked up even though the 5 year total shareholder return is still down 43.40%.
Scan how Diageo’s renewed momentum compares with other established consumer brands by reviewing the hand picked 16 high quality undervalued stocks that combine cash generation with sturdier balance sheets.
Diageo now trades at a clear discount to both analyst targets and some intrinsic estimates after a sharp short term rebound. Is the market prudence here still warranted, or has caution gone too far?
Most Popular Narrative: 9% Undervalued
On the analyst consensus Narrative on Simply Wall St, Diageo’s fair value of £20.62 sits above the last close of £18.80. This frames the AGM updates against a market that still prices in some caution despite the recent rebound.
The main thing that has to go right is that Diageo executes the multi year restructuring and North America turnaround without major disruption, so the targeted overhead reductions, route to market changes and category strategies in key regions translate into sustained operating profit and free cash flow delivery.
The current valuation implies the share price already reflects cautious assumptions on near term net sales growth and North America pressure. If Diageo delivers on its plan for mid single digit operating profit growth, material recurring savings and multi year capex behind Guinness, the stock appears undervalued on this narrative.
See why 157 investors see Diageo as 9% undervalued.
Result: Fair Value of £20.62 (UNDERVALUED)
Still, the narrative can unwind if alcohol moderation pressures hit volumes harder than expected, or if emerging market currency and regulatory shocks undercut Diageo’s profitability story.
Find out about the key risks to this Diageo narrative.
Another View: Diageo Looks Pricy On Earnings
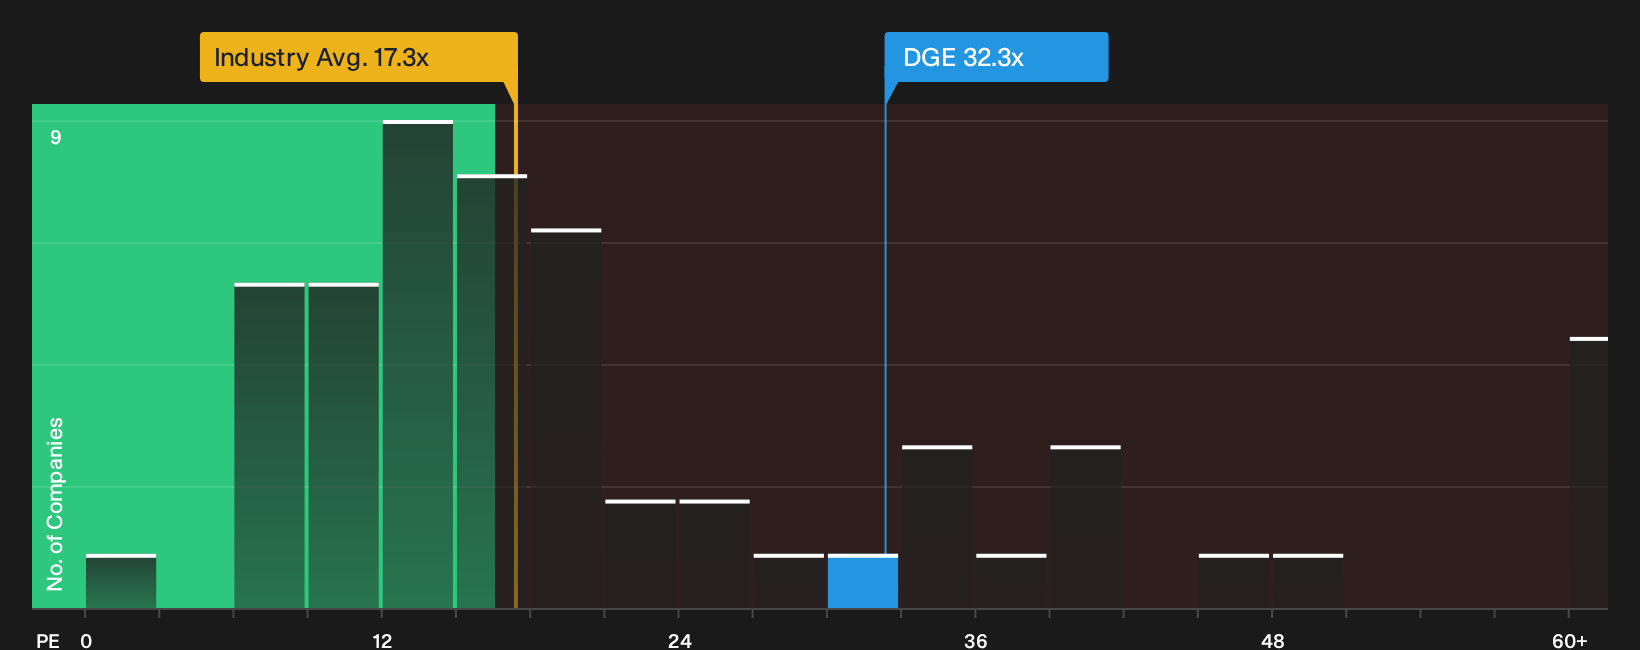
There is a twist when you look at Diageo through its P/E. The shares trade on 32.3x earnings, above the 30.1x fair ratio and well ahead of the European Beverage average on 17.3x. That kind of gap can signal valuation risk if sentiment cools.
For anyone weighing this against the earlier fair value work, it is worth stepping through the full earnings based breakdown in more detail, starting with the See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Mixed messages on Diageo’s valuation and earnings can pull you in both directions, so act while sentiment is split and weigh the 2 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Diageo?
Do not stop at Diageo. Use the screener to surface fresh opportunities that match your style so your watchlist does not miss the next move.
- Target potential mispricing by scanning a hand picked 16 high quality undervalued stocks that could offer quality profiles at more modest valuations.
- Strengthen portfolio resilience by focusing on a list of solid balance sheet and fundamentals (9 results) and filter for companies with sturdier financial footing.
- Get ahead of the crowd by reviewing a 5 high quality undiscovered gems that have strong fundamentals but limited current attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com