


Teijin (TSE:3401) has reported half-year results for the period to 30 September 2026, with sales of ¥439,562 million and net income of ¥52,541 million, compared with a net loss a year earlier.
Teijin’s latest half year earnings have landed just as momentum in the share price has picked up again, with a 7 day share price return of 6.64% and a 30 day gain of 5.24% helping the stock reach ¥1,726.5. Over a longer horizon, the 1 year total shareholder return of 40.88% and 3 year total shareholder return of 43.08% suggest investors have been rewarded while sentiment has recently cooled a little, given the share price return over the last 90 days declined 2.15%.
Scan how Teijin’s rebound compares with other material stocks showing strong recent moves by reviewing our hand picked list of 22 high quality undervalued stocks that may warrant a closer look.
After a sharp rebound and a return to profit, Teijin now sits at a point where some investors see the easy gains as history. Others suspect the valuation still leaves room on the upside.
Most Popular Narrative: 7% Undervalued
Teijin’s bullish analyst Narrative on Simply Wall St anchors fair value at ¥1,860, a touch above the last close of ¥1,726.5, and builds its case around execution of restructuring and business mix changes rather than short term trading moves.
The shift to a customer issue driven business model across Apparel & Industries, Healthcare & Life Solutions, Electronics & Energy and Specialty Materials aims to move Teijin toward higher value solutions rather than commoditized materials. This is intended to support more resilient revenue growth and a higher adjusted operating income base.
See why 0 investors see Teijin as 7% undervalued.
The valuation work behind that narrative uses a discount rate of 6.63% and assumes revenue, margins and returns improve enough for Teijin to justify a fair value of ¥1,860. This view sits at the optimistic end of analyst forecasts and contrasts with the separate Simply Wall St DCF output, which points to a future cash flow value of ¥2,276.18 and a 24.1% gap between that estimate and the current share price.
For readers comparing signals, this means the bullish analyst Narrative frames Teijin as modestly undervalued against its own assumptions, while the SWS DCF model suggests a larger valuation cushion if the projected cash flows are achieved.
Result: Fair Value of ¥1,860 (UNDERVALUED)
Still, Teijin’s story depends on restructuring delivering the planned earnings uplift, and on price pressure in aramid and carbon fibers not eroding margins further.
Find out about the key risks to this Teijin narrative.
Another View: What Teijin’s P/E Is Signalling
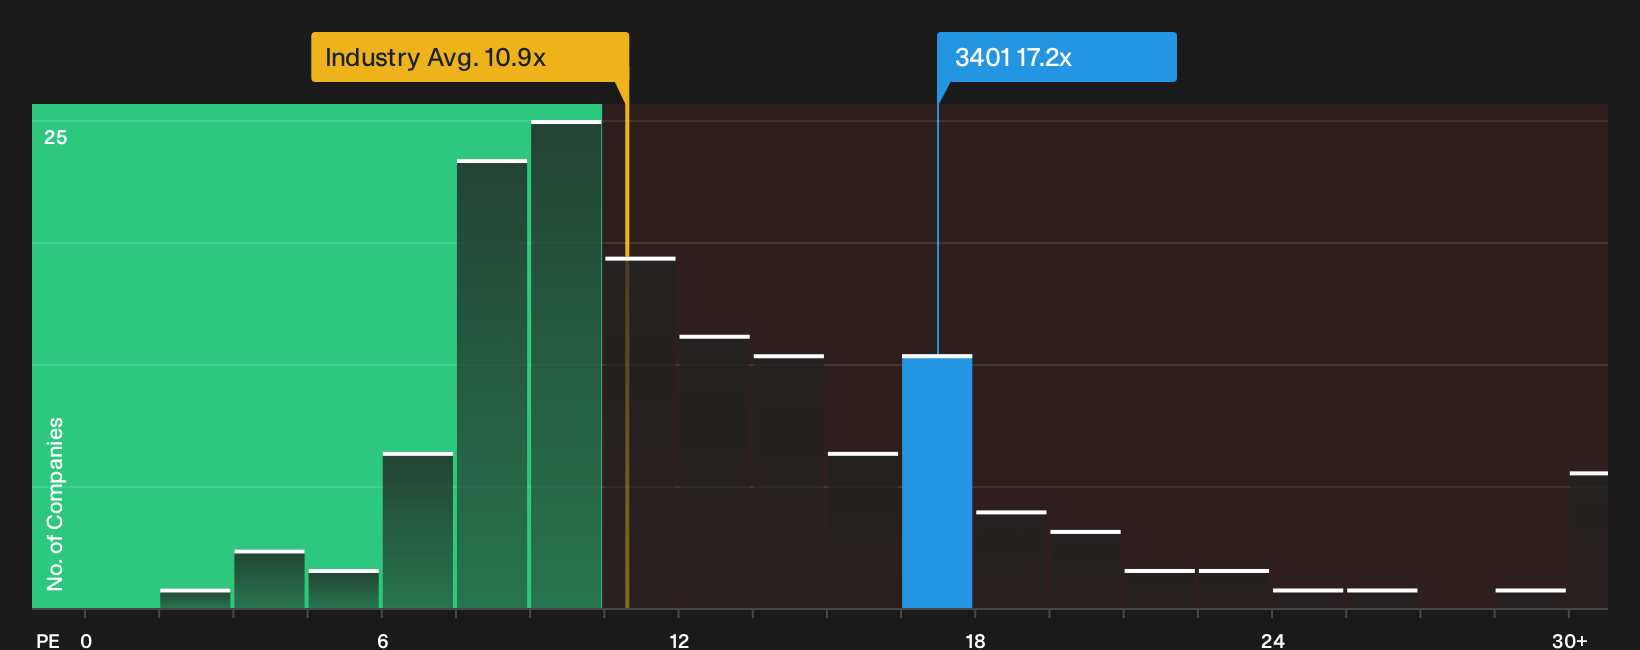
There is a very different message coming from Teijin’s current P/E of 17.2x. That ratio sits well above the JP Chemicals group at 10.9x and also above the peer average of 12.2x, while the fair ratio is 11.5x. For investors, that gap points to valuation risk if expectations soften or earnings slip from here.
To see how that premium lines up against the underlying numbers, and where the price could drift if the market leans closer to the fair ratio, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If this mix of optimism and caution around Teijin feels familiar, consider taking a closer look while the data is current and pressure test the story for yourself with 2 key rewards and 4 important warning signs
Looking for more investment ideas beyond Teijin?
Teijin’s valuation debate is a useful starting point, but your portfolio deserves a wider bench of ideas that match your own goals and risk tolerance.
- Target potential mispricings in quality companies by scanning our hand picked list of 22 high quality undervalued stocks while sentiment is still catching up.
- Strengthen your income stream by focusing on resilient cash payouts using the curated 35 dividend fortresses before yields move away from current levels.
- Protect your downside by concentrating on sturdier balance sheets with the focused 18 resilient stocks with low risk scores that many investors only find after volatility hits.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com