


What Lattice Semiconductor’s Latest Earnings Signal For Investors
Lattice Semiconductor (LSCC) has drawn fresh attention after releasing third quarter results and issuing fourth quarter 2026 revenue guidance between US$325 million and US$345 million. The dual update gives investors new data on both recent performance and near term expectations.
Recent trading shows how quickly sentiment around Lattice Semiconductor can swing. The share price jumped 8.45% in the last session and gained 19.33% over the past week after the earnings and guidance update, even though the 30 day share price return is down 9.65% and the 90 day return is down 9.70%. At the same time, the 1 year total shareholder return of 69.83% and 3 year total shareholder return of 107.60% point to longer term momentum that has rewarded investors who stayed the course.
Scan other fast moving chip opportunities by reviewing the 53 AI infrastructure stocks that are experiencing similar earnings and guidance momentum to Lattice Semiconductor.
Lattice Semiconductor now has strong reported growth and a stock that just jumped hard on the news. The real tension is whether that business strength is already fully reflected in the price.
Most Popular Narrative: 28% Undervalued
The analyst consensus Narrative on Simply Wall St marks Lattice Semiconductor's fair value at $158, above the last close of $113.89, and frames that gap using a detailed set of growth, margin, and risk assumptions built around AI infrastructure and industrial demand.
The main thing that has to go right is the company successfully scaling the combined FPGA and AMI platform while managing supply constraints, new tariffs, and higher leverage without eroding margins.
The valuation implied by this narrative is that Lattice Semiconductor is valued relative to its guided revenue run rate of about US$1.2b exiting 2026 and its long term revenue target of US$3b by 2030.
See why 30 investors see Lattice Semiconductor as 28% undervalued.
Result: Fair Value of $158 (UNDERVALUED)
Still, the story around Lattice Semiconductor can break if supply chain bottlenecks squeeze margins or if AI and industrial demand fall short of analyst assumptions.
Find out about the key risks to this Lattice Semiconductor narrative.
Another View On Lattice Semiconductor’s Valuation
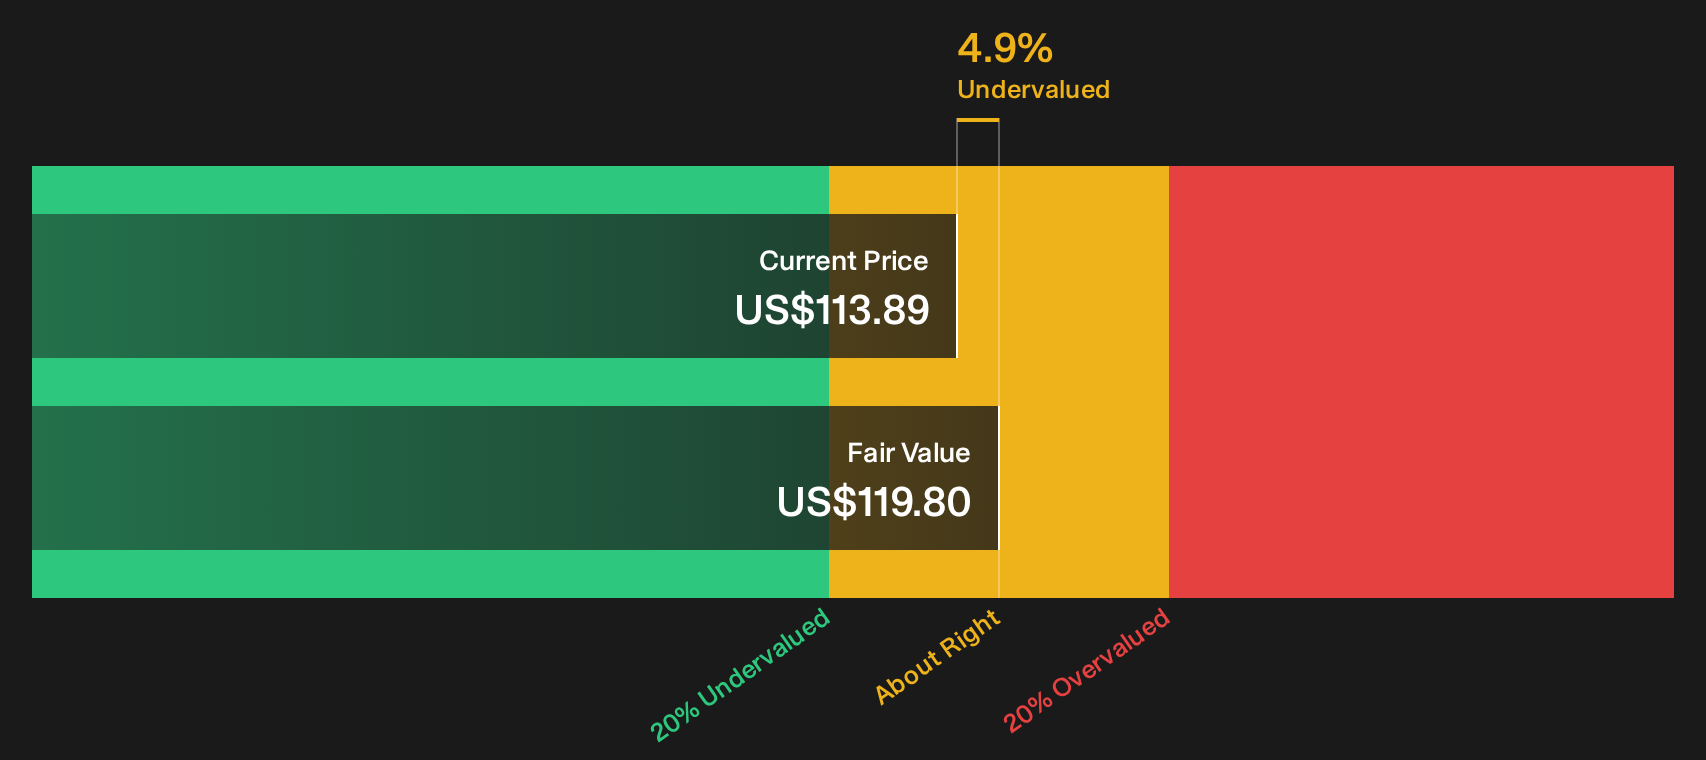
While the Simply Wall St DCF model points to Lattice Semiconductor trading about 4.9% below its estimated future cash flow value of $119.8, the market is already attaching a rich P/S ratio of 20x, well above both the US Semiconductor average and peers. Which signal do you trust more when real money is on the line?
For a closer look at how this cash flow based estimate is built, walk through the full workings in the Look into how the SWS DCF model arrives at its fair value..
Next Steps
Mixed messages on Lattice Semiconductor's value and risk can feel unsettling, so move quickly to review the full picture and decide where you stand by weighing the 3 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Lattice Semiconductor?
If you stop with just Lattice Semiconductor, you miss a whole field of potential opportunities. Widen your view and pressure test your next move.
- Spot potential mispricings early by scanning a curated set of 33 high quality undervalued stocks that pair quality fundamentals with compressed expectations.
- Build a more resilient portfolio by focusing on companies with sturdy finances using the list of solid balance sheet and fundamentals (25 results) to filter out weaker balance sheets.
- Get ahead of the crowd by hunting through 19 high quality undiscovered gems where strong underlying metrics have not yet attracted broad attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com