


- Plug Power has flagged an expected third quarter loss of about 7 cents per share on roughly US$195 million of revenue, alongside pre announced cash use of US$28 million and quarter end cash of US$134 million, which indicates lower cash burn than before.
- The company is promoting hydrogen fuel cells as backup power for data centers, using active discussions and deals with developers to position this segment as a potential new pillar alongside material handling, electrolyzers and stationary power.
- We will now examine how Plug Power's investment narrative is affected by the focus on hydrogen fuel cells for data centers.
Scan hand picked peers riding the same energy and data-center theme as Plug Power by filtering for 42 power grid technology and infrastructure stocks in your next watchlist update.
Plug Power Investment Narrative Recap
To own Plug Power, you need to buy into a hydrogen build out where fuel cells, electrolyzers and service contracts can eventually support a more efficient cost base. The analyst consensus Narrative on Simply Wall St leans on Project Quantum Leap to keep gross margins near breakeven and restrain operating costs. The latest pre announcement, with an expected Q3 loss of about 7 cents per share and US$28 million of cash use, suggests the operating reset is still the key story.
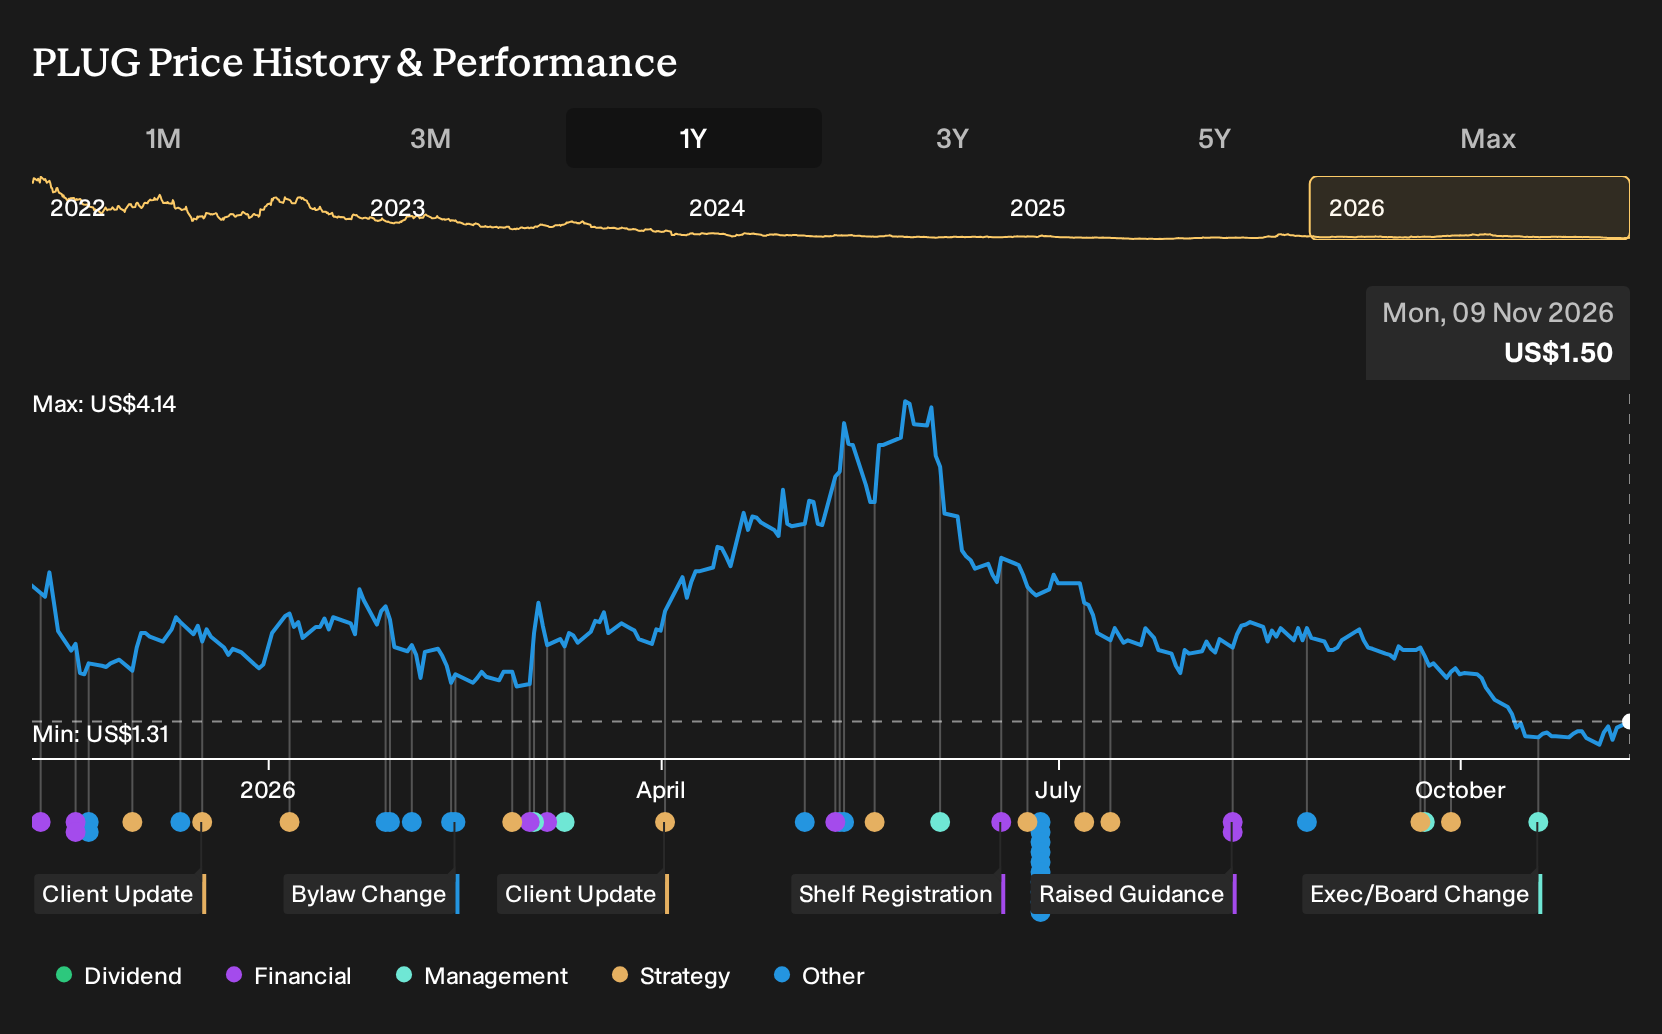
The short term catalyst is whether Plug Power can keep cash burn contained while pushing newer areas like data center backup power into meaningful orders. Reported quarter end cash of US$134 million keeps funding risk in focus, since the group is still unprofitable and carries less than one year of cash runway. If project execution wobbles or cost discipline slips, the need for fresh capital, and potential dilution, remains the biggest swing factor.
The data center hydrogen backup pitch ties directly to those catalysts. If Plug Power can convert its current discussions and deals with developers into repeatable deployments, that could complement the existing material handling and electrolyzer base and help support the revenue growth that analysts are forecasting. The early signals here matter because the firm is trying to broaden its customer mix without taking on outsized project risk.
This focus also interacts with the risks already flagged in the analyst consensus Narrative on Simply Wall St. Large infrastructure and electrolyzer projects have shown they can be cancelled, as seen with the 100 MW Antwerp plant, so any data center wins will still be judged on execution quality and contract structure. For you as an investor, the key questions are whether these deployments can be done with disciplined capital use, limited reliance on external funding and steady progress on margins under Project Quantum Leap.
Plug Power's narrative projects US$1.3b revenue and US$148.3 million earnings by 2029. This assumes 21.4% yearly revenue growth and an earnings increase of about US$1.75b from current earnings of a US$1.6b loss today.
Discover how Plug Power's fair value indicates a 126% potential upside to its current price, which could see any discount close faster than expected.
Exploring Other Perspectives
One bearish angle on Plug Power focuses on project risk. The lowest analysts were already wary that cancellations could leave the business with only about US$1.1b of revenue and US$125.6 million of earnings by 2029. Those forecasts came before this data center hydrogen update, so your view may shift as the story evolves.
Explore 6 other Plug Power fair value estimates, including one that suggests as much as 73% downside from the current price.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Plug Power research is our analysis highlighting 1 key reward and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Plug Power. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Plug Power's overall financial health at a glance.
Looking For More Investment Ideas Beyond Plug Power?
If the Plug Power story has you rethinking where risk, balance sheet strength and income fit in your portfolio, it can help to line it up against other options using the Simply Wall St Screener.
- For investors who want income to pull more weight in total returns, scan for higher yield opportunities through 6 dividend fortresses that might better match your payout targets.
- If capital preservation sits higher on your priority list, review 30 resilient stocks with low risk scores and compare those results with Plug Power's risk profile.
- When the goal is to back financially robust operators, start with a list of solid balance sheet and fundamentals (25 results) and see which businesses offer the mix of resilience and fundamentals you are looking for.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com