


In the context of the accelerated expansion of global AI computing power infrastructure, the cost restructuring of the consumer electronics industry chain, and the continuous advancement of electrification of new energy vehicles, connector and precision interconnect companies are undergoing a round of profound value revaluation.
The Zhitong Finance App notes that Hongteng Precision (06088) achieved revenue of about US$1,378 billion in the third quarter of 2026, an increase of about 4.0% year on year; net profit from continuing operations was about US$50.63 million, down about 32.7% year on year. The gross margin was about 19.36%, and the operating profit was about US$58 million, down about 38.8% year on year. The operating profit margin narrowed to 4.2% from about 7.1% in the same period last year. It can be seen that the company's short-term profits are still disrupted by factors such as rising storage prices, rising AI production lines, and foreign exchange. Looking at it from a longer perspective, this is more like the phased pressure experienced by a company in a transition period.
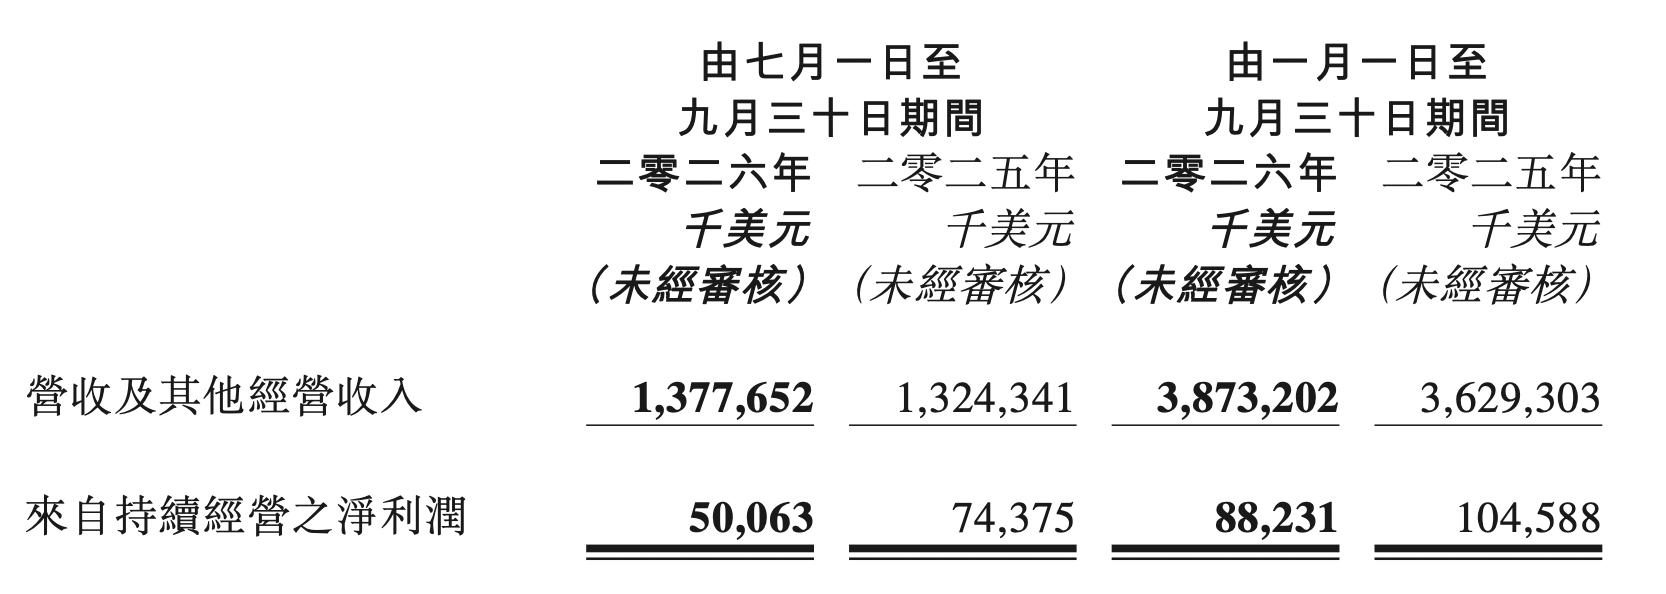
So, when consumer electronics are under short-term pressure and operating profits are still climbing, where exactly is Hongteng Precision's real growth fulcrum? Let's start by looking at the fundamentals.
Revenue growth, profit pressure
Judging from financial performance, Hongteng Precision's profit performance in the third quarter of 2026 showed the characteristics of “revenue growth and profit pressure”. There was a slight year-on-year increase in revenue, but operating profit and operating profit margins declined markedly. The reason behind this was not a single one. The computer and consumer electronics terminal market revenue fell 22% year over year, mainly affected by the shortage of upstream components such as memory chips and price increases, and terminal demand was somewhat suppressed. This pressure is not a company case, but rather a cost disruption that the consumer electronics industry chain is currently facing together.
According to the Zhitong Finance App, although Apple's fourth fiscal quarter results are better than market expectations, management has clearly indicated that rising storage costs will put pressure on subsequent gross margins; Nomura also pointed out in the research report that due to rising memory chip costs, the Apple supply chain will face more serious challenges from the fourth quarter of this year to the first quarter of next year, and overall supplier revenue from Apple in the first half of next year may drop by double digits year on year. For Hongteng Precision, this means that the consumer electronics sector may still be in a period of double testing of demand and costs in the next few quarters. In particular, the order rhythm, product restructuring, and inventory digestion related to the Apple ecosystem will disrupt short-term revenue recognition and profit margins.
At the same time, the new production line for next-generation AI products is in a climbing phase. Learning costs, yield improvement investment, and cost pressure brought about by capacity expansion are all squeezing current operating margins. Furthermore, new production capacity such as Vietnam climbed slower than expected, which also dragged down gross margins. The combination of these factors makes it easy for the market to interpret the decline in short-term operating profits as weakening fundamentals.
Looking at it another way, the company is currently in a transition phase where the product structure is being upgraded and production capacity is gradually climbing. The consumer electronics sector is being impacted by upstream storage costs, which is a phased issue faced by the industry chain; the rise in new AI production lines means that the company is preparing for the subsequent release of high-value products. The company maintained the 2026 annual revenue growth rate of 5% to 15% and gross profit growth of more than 15% year on year, but lowered the year-on-year operating profit growth rate guide to the range of -5% to +5%, mainly reflecting the effects of new production capacity climbing slower than expected, rising raw material prices, and changes in product structure. As a result, phased headwinds in the consumer electronics sector have highlighted the structural significance of 41% high growth in data center business. While traditional consumer electronics orders are likely to decline sharply in the next few quarters, the share of revenue related to AI data centers has increased, providing more definitive growth support for the company.
Data center business is growing rapidly, and the value of AI connectivity platforms is showing
As mentioned earlier, the data center business is arguably the most definitive source of growth today. In the third quarter of 2026, the business's revenue reached US$303 million, up 41% year over year, and increased its share of revenue to about 22%. This increase is not due to the expansion of the scale of low-value-added products, but rather the increase in demand for AI servers, driving the joint release of copper-based components, high-speed connectors, cable components, backplane connectors, power modules, and liquid cooling-related products. As AI cabinets evolve to higher bandwidth and higher power density, the degree of coupling between connectivity, power supply, and cooling has increased significantly, and the value of a single component supplier is being replaced by system-level solution capabilities.
Hongteng Precision's product layout is progressing rapidly in this direction. The company expects the share of data center business revenue to increase from about 16% in 2025 to a high 20% range in 2027, and to more than 30% in 2028. Meanwhile, the company is promoting next-generation optical interconnection projects with strategic partners, and is expected to announce new developments in the next 6 to 9 months. These products cover key aspects of AI servers from inter-chip interconnection and high-speed transmission within the cabinet to power and thermal management, enabling the company to upgrade from traditional connector suppliers to an integrated platform of “copper connection+optical connection+power supply+liquid cooling”.
More importantly, the increase in the revenue share of the data center business is structurally significant. As new plant yields and capacity utilization improve, revenue from the data center business is expected to contribute more profit. This means that revenue related to AI data centers will gradually become one of the company's core revenue sources, and the company's valuation anchor may also shift from the consumer electronics cycle to the AI infrastructure growth logic.
The automobile business fluctuated in the short term, and the business layout gradually took shape
Compared to the boom in the data center business, the automotive business performed poorly in the third quarter of 2026, achieving revenue of US$218 million, a year-on-year decrease of 9%. The main reason is weak demand in the automotive industry and the impact of supply chain pressure, which affects the pace of short-term orders. However, judging the long-term potential of the automobile business based on single-quarter data alone may underestimate the company's completed front-line layout.
Over the past few years, Hongteng Precision has significantly enhanced its automotive electrification capabilities through mergers and acquisitions. The company has successively integrated the German Prettl SWH business and completed the acquisition of the Auto-Kabel Group in 2024, which has strong accumulation in automotive energy distribution, high-voltage wiring, busbars and aluminum cable technology. These mergers and acquisitions have extended the company from traditional automotive connectors to higher value links such as high-voltage electric vehicle systems, battery wiring harnesses, charging sockets, and drive cables. As integration progresses, cross-selling, customer resource collaboration, and manufacturing efficiency improvements are expected to be gradually unleashed.
In the field of charging piles, the company is also promoting a global production capacity layout. Hongteng Precision and its Saudi partner have set up a joint venture Smart Mobility to build a manufacturing base for electric vehicle charging stations in the Middle East in Saudi Arabia. The project is expected to be put into operation in 2026. This layout not only fits the promotion of electrification policies in the Middle East region, but also helps the company lower the market entry threshold through localized production, and collaborate with Hon Hai Group's strategies in electric vehicle foundry and energy infrastructure. Although the automobile business is still affected by the industry cycle in the short term, in the medium term, the implementation of high-voltage wiring harnesses, charging solutions, and overseas production capacity will provide the company with a second layer of growth support.
Industrial chain collaboration between Hongteng Precision and Hon Hai is another main line for understanding the certainty of growth in the medium term. In November 2026, the company announced the renewal of ten continuing connected transaction framework agreements with the controlling shareholder Hon Hai, covering the period 2027 to 2029. Among them, the annual upper limits of product sales under the sales framework agreement are US$856 million in 2027, US$1,050 billion in 2028, and US$110 billion in 2029, respectively, showing a trend of increasing year by year. This increase in the upper limit of the framework reflects the expectation that Hon Hai Group's procurement demand for Hongteng Precision will continue to expand in the field of AI servers, high-speed connections and related components.
Hon Hai's own progress in the field of AI servers has also provided a foundation for collaboration. Hon Hai recently stated that the AI server business already accounts for more than 50% of its total server revenue, and AI rack shipments are expected to double throughout the year. As an important partner of Hon Hai in high-speed connectivity, optical interconnection, power supply and liquid cooling components, Hongteng Precision is expected to directly benefit from the parent company's order expansion. It should be emphasized that the framework still needs to be approved by independent shareholders, but the upper limit increase itself has sent a signal of strengthening collaboration within the industrial chain. For companies that are in the process of climbing production capacity and upgrading products, this relatively stable order environment helps reduce the uncertainty of new business expansion.
Taken together, Hongteng Precision's current profit pressure is more a phased pain caused by product switching, rising production capacity, and rising costs, rather than damage to the long-term growth logic. The consumer electronics and automotive business is still being dragged down by weak demand in the short term, but the 41% high growth in data center business has shown that AI is becoming the new spindle. With the advancement of next-generation optical interconnection, liquid cooling and power solutions, and the collaboration of Hon Hai's industrial chain, the company is expected to gradually shift from traditional connector suppliers to AI infrastructure and automotive electrification platforms. For investors, short-term operating margin fluctuations require patience; however, judging from industry trends, Hongteng Precision is standing at a critical point from “cycle repair” to “structural upgrading”. The resonance between AI and the automobile dual engine may become the core driving force for the next stage of value revaluation.