


West Japan Railway (TSE:9021) has raised its full year FY2027 earnings forecasts and declared a higher second quarter dividend, moves that highlight how the business is responding to increased railway and retail activity.
The guidance upgrade and higher interim dividend have come alongside a sharp 30 day share price return of 13.48% and a 90 day gain of 14.85%, with the stock now at ¥3,295. Over the past year, total shareholder return of 10.14% and a 5 year total shareholder return of 39.75% indicate that recent momentum is building on a longer recovery story, rather than appearing as a short lived spike.
Spot opportunities riding similar themes of upgraded guidance and rising payouts by scanning our curated 35 dividend fortresses alongside West Japan Railway's latest moves.After that sharp move on refreshed guidance and a higher dividend, the question for West Japan Railway now is simple. Is most of the upside already priced in, or is the market still catching up to the fundamentals?
Preferred P/E of 13.1x for West Japan Railway: Is it justified?
On a simple snapshot, West Japan Railway trades on a P/E ratio of 13.1x, while our system estimates a fair P/E of 15.7x and the broader JP Transportation group sits closer to 12x. At ¥3,295 per share and with the stock having already moved sharply over the last 30 days, that mismatch between current pricing and these reference points is what investors are now trying to make sense of.
The P/E multiple compares the share price to earnings per share. For a railway and related retail and property operator like West Japan Railway, this lens effectively shows how much of a premium or discount the market is placing on its profit stream compared with similar transportation businesses.
There are cross currents. On one side, 9021 is described as expensive versus the JP Transportation industry average P/E of 12x, which implies the market is paying more for each yen of current earnings than it does for the typical peer. On the other side, the ratio is flagged as good value relative to both the peer average of 16x and the estimated fair P/E of 15.7x. This signals that if sentiment were to line up with those reference levels then the multiple could shift higher rather than lower.
This spread in comparisons is important. Against the industry, the current P/E looks rich. Against the peer average and the fair ratio, West Japan Railway screens cheaper, which suggests the market may be assigning a more cautious view of its future earnings than those benchmarks imply.
Explore the SWS fair ratio for West Japan Railway.
Result: Price-to-Earnings of 13.1x (ABOUT RIGHT)
Still, that fair P/E argument can unravel fast if West Japan Railway faces weaker passenger volumes or if analysts cut earnings expectations from this point forward.
Find out about the key risks to this West Japan Railway narrative.
Another view on West Japan Railway's value
The DCF model paints a very different picture. At ¥3,295, West Japan Railway is trading above our estimate of future cash flow value of ¥1,821.31, which points to the shares looking expensive rather than cheap. That gap raises a simple question for you: Which signal deserves more weight?
Look into how the SWS DCF model arrives at its fair value.
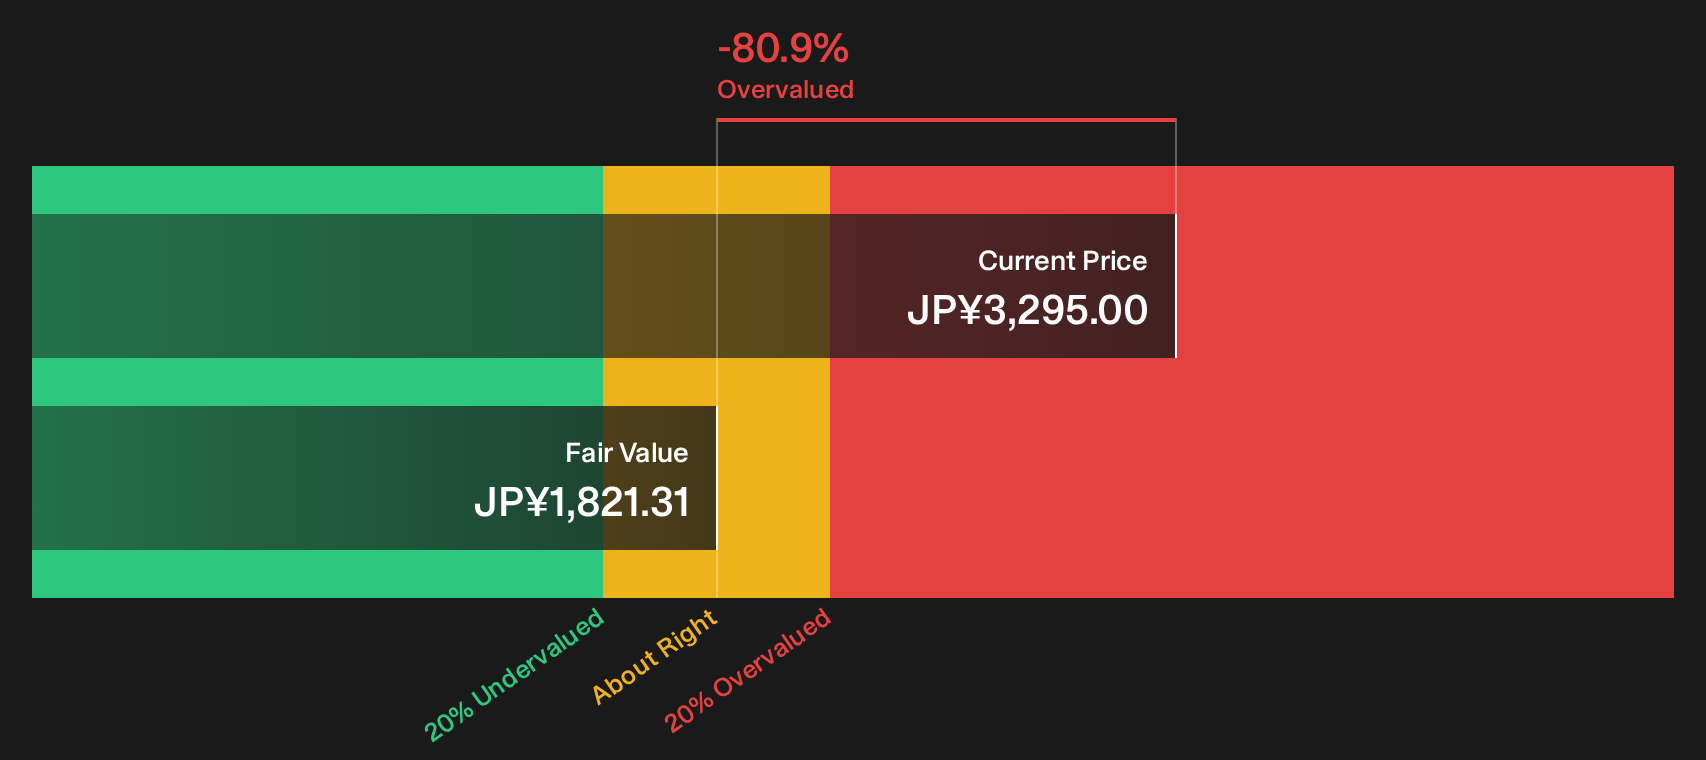
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out West Japan Railway for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 22 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
If this mix of signals around West Japan Railway feels conflicted, treat it as a prompt to dig into the details yourself and pressure test the assumptions on risk. To frame that work, start by understanding the 2 important warning signs.
Looking for more investment ideas beyond West Japan Railway?
If West Japan Railway has sharpened your focus on valuation and income, you can broaden your watchlist now with a few targeted filters built for different goals.
- Target resilient balance sheets and steady fundamentals by scanning our list of solid balance sheet and fundamentals (23 results).
- Hunt for mispriced quality where expectations look muted compared to fundamentals through the 22 high quality undervalued stocks.
- Prioritize income potential and consistent payout profiles by reviewing the 35 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com