


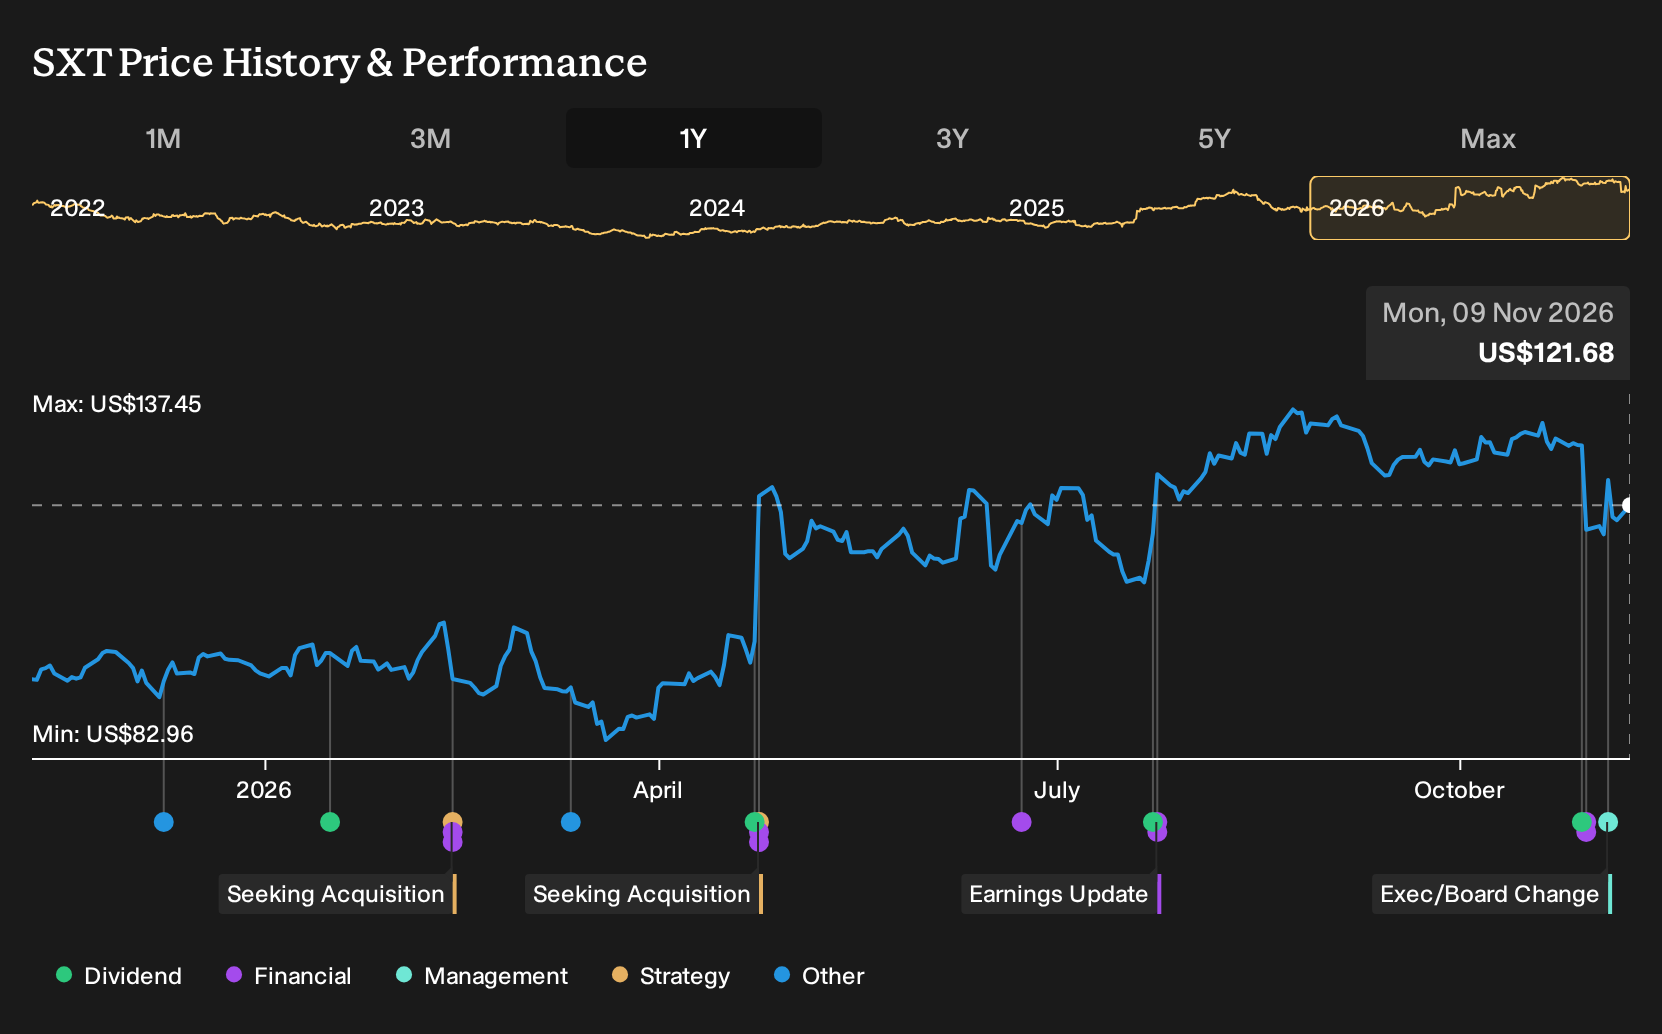
- Sensient Technologies reported third quarter 2026 sales of US$455.84 million and net income of US$48.34 million, with full year 2026 diluted EPS guidance nudged to a US$4.15 to US$4.20 range.
- The combination of higher quarterly and year to date earnings per share from continuing operations and a slight guidance lift indicates that management views current demand and cost conditions as supportive enough to refine the profit outlook upward.
- We will now examine how Sensient Technologies' slightly raised full year earnings guidance shapes the broader investment narrative around natural colors.
Sensient Technologies Investment Narrative Recap
To own Sensient Technologies, you need to believe the regulatory shift toward natural colors can support years of demand for its ingredients while the heavy capex plan is absorbed without straining cash flow. The slight 2026 EPS guidance lift suggests current trading conditions are supportive, yet it does not radically change that longer term thesis.
The main short term catalyst remains execution on natural color conversions and capacity ramp up that can keep earnings growth in line with the analyst consensus Narrative on Simply Wall St. The main near term risk continues to be supply chain and input cost pressure, which could squeeze margins if pricing power softens.
The most relevant recent announcement is the appointment of Ernest Chan and Philip Yu to the board, both joining the Scientific Advisory Committee. Fresh oversight on that committee could matter for how Sensient Technologies prioritizes R&D and capital for natural colors, especially with US$225m to US$250m planned natural color spending through 2028.
For you as an investor, this board refresh feeds directly into the existing catalysts and risks. Better technical oversight can help align capacity, agricultural sourcing, and technology choices with the natural color opportunity, while any misstep in these decisions would compound the existing concerns around debt coverage and input cost volatility.
Sensient Technologies' current analyst narrative points to 2029 revenue of US$2.6b and earnings of US$312.0m, based on an assumed 14.7% yearly increase in sales and an earnings step up of US$154.0m from the US$158.0m reported today.
Uncover why Sensient Technologies' fair value indicates a 19% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
Some lower ranked analysts focus less on natural colors and more on leverage risk at Sensient Technologies. Before this board refresh and guidance tweak, the most cautious group still modeled revenue reaching about US$2.6b and earnings of roughly US$317.0m by 2029. That is a different story from consensus, and it shows how sharply views can diverge. Use this news as a prompt to compare several narratives rather than rely on a single script.
The Verdict Is Yours
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Sensient Technologies research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Sensient Technologies. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Sensient Technologies' overall financial health at a glance.
Looking For More Investment Ideas Beyond Sensient Technologies?
If Sensient Technologies has sharpened your interest in how different businesses balance growth plans with financial discipline, it can be useful to compare it with other listed stocks that share some of the traits you care about most. The Simply Wall St Screener helps you scan the market through that lens in a few clicks.
- If capital preservation sits high on your priority list, start with companies that our filters flag as relatively steady using the 30 resilient stocks with low risk scores.
- For readers hunting for quality at a reasonable price, line up businesses that currently look attractively priced on both fundamentals and balance sheet strength via the 33 high quality undervalued stocks.
- Income focused investors can zero in on stocks offering robust cash returns to shareholders by reviewing the 6 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com