


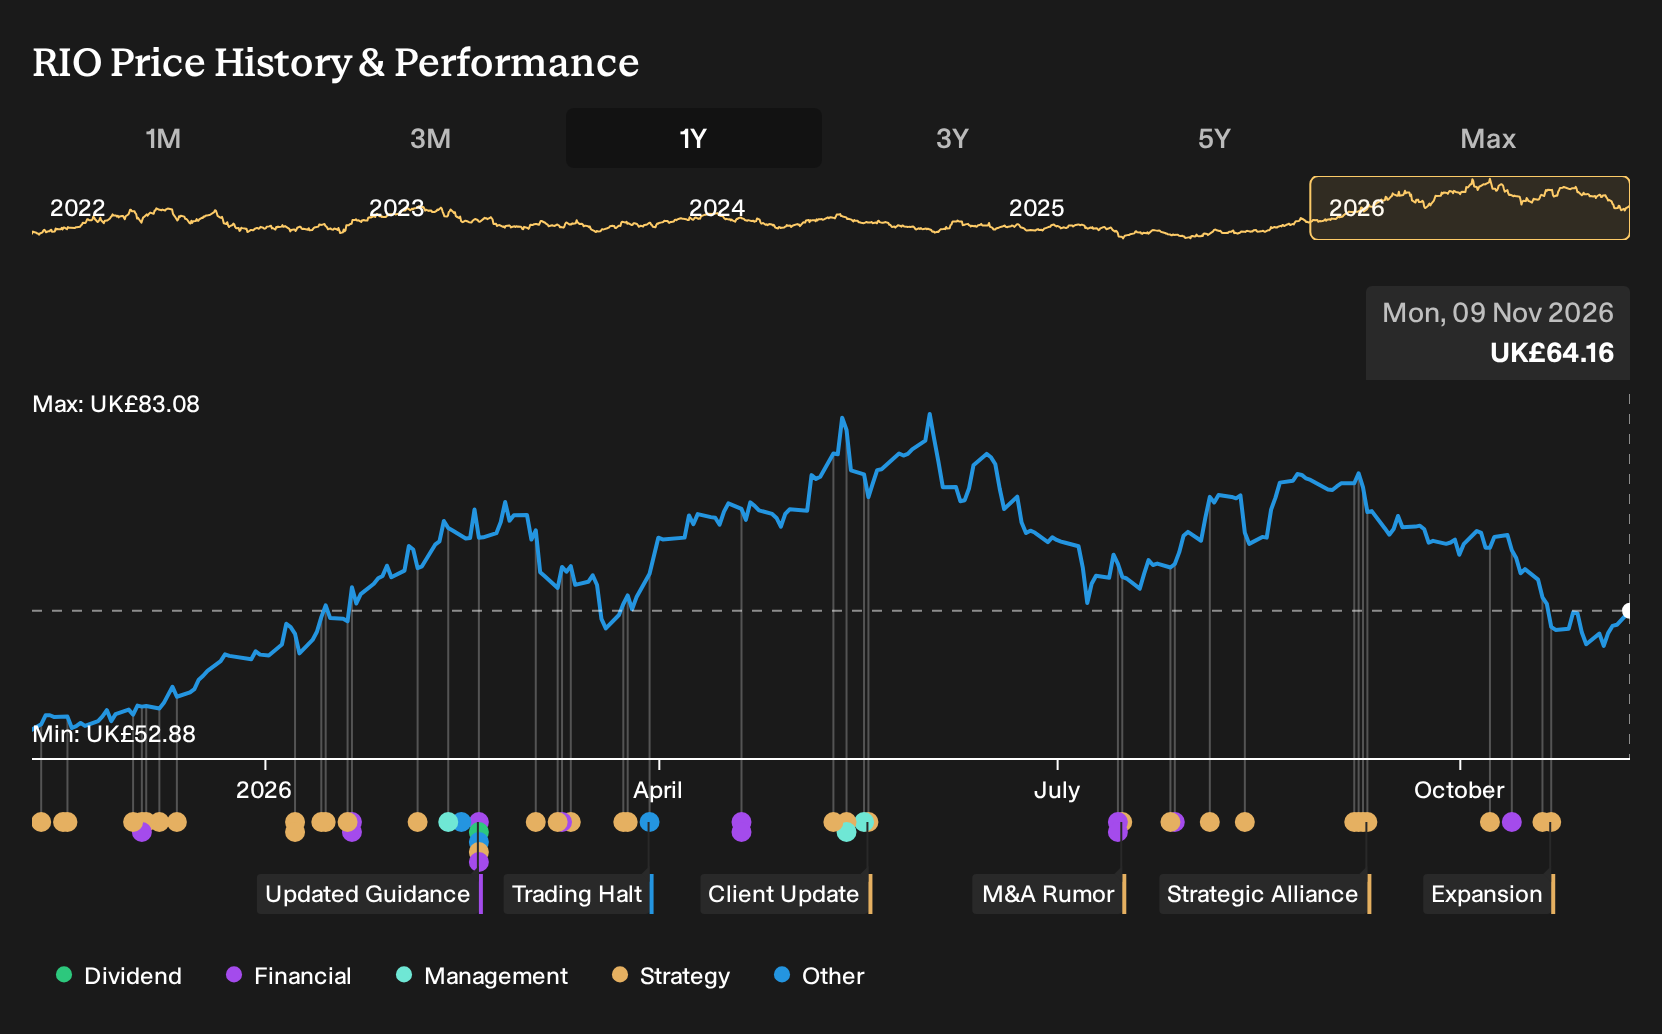
- Rio Tinto Group recently expanded its presence in China through new partnerships, including a copper concentrate agreement with Jinchuan, while benefiting from firmer iron ore demand that supported Australian mining stocks.
- This combination of deeper Chinese relationships and supportive commodity pricing directly affects Rio Tinto's mix of copper and iron ore exposure, which is central to its long term electrification and infrastructure demand thesis.
- We will examine how Rio Tinto's growing Chinese copper partnerships intersect with its long term, electrification focused investment narrative.
Scan for other miners that align with Rio Tinto Group's electrification and infrastructure focus by reviewing the hand picked 16 top copper producer stocks alongside this thesis.
Rio Tinto Group Investment Narrative Recap
To own Rio Tinto Group, you really need to buy into a long run story of electrification metals, iron ore demand tied to infrastructure and ongoing productivity gains. The analyst consensus Narrative on Simply Wall St leans on projects like Oyu Tolgoi, Simandou and new lithium capacity, which all depend on smooth execution and no major ESG or operational setbacks.
In the short term, the key swing factor is still operational reliability and volume delivery from iron ore and copper. Recent firmness in iron ore prices and support for mining stocks looks helpful for near term cash generation, while the biggest immediate risk remains unplanned outages or logistics issues that can quickly pressure unit costs and earnings.
Among the recent developments, the new copper concentrate deal with China’s Jinchuan looks most relevant. It ties directly into Rio Tinto Group’s aim to grow copper exposure, which analysts link to long term electrification and infrastructure demand. The agreement also deepens engagement with China, currently the largest geographic revenue contributor for the group.
For catalysts, this Jinchuan supply relationship may help underpin throughput and offtake as Oyu Tolgoi and other copper assets move through their ramp up paths described in the analyst consensus Narrative on Simply Wall St. The operational upside sits alongside clear risks, including ESG scrutiny and class actions in Australia, which could still slow projects or lift ongoing costs if issues escalate.
How Rio Tinto Group’s Forecasts Tie Back to Electrification Metals
Analysts are effectively asking investors to look at Rio Tinto Group through the lens of slow but steady expansion in cash flow that can support its copper heavy electrification pitch. The forecasts assume revenue grows by 2.8% a year for the next few years while profit margins widen from 19.6% today to 23.8%. This would be a meaningful shift in how much of every sales dollar becomes profit if it plays out as expected.
The earnings path in those models is clear enough to quantify. Current profit is set at about US$12.1b, while the consensus points to US$15.9b of earnings by 2029, with a wide range of US$12.4b to US$21.5b depending on the analyst. That move from US$12.1b to US$15.9b implies roughly a 31% step up in earnings, which is what has to be underwritten by projects like Oyu Tolgoi and the China linked copper offtakes tied into the electrification story.
On the top line, those same projections call for revenue of US$67.1b in 2029. Taken together, the combination of 2.8% annual revenue growth, higher margins and an earnings bridge from US$12.1b to US$15.9b underpins the current analyst narrative that Rio Tinto Group’s mix shift toward copper, aluminium and lithium could support long run exposure to grid build out, renewables and broader infrastructure demand.
Rio Tinto Group's narrative projects US$67.1b revenue and US$15.9b earnings by 2029. This rests on 2.8% yearly revenue growth and roughly a 31% earnings increase from US$12.1b today.
Uncover why Rio Tinto Group's fair value indicates a 17% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
You are seeing two very different stories around Rio Tinto Group. The most optimistic analysts lean heavily on productivity gains as a catalyst, with models that already pencilled in about US$76.1b of 2029 revenue and US$21.4b of earnings before this China copper news. That gap versus consensus highlights how sharply views can diverge, so it can be worth comparing several narratives and deciding which assumptions you find most realistic.
Explore 6 other Rio Tinto Group fair value estimates, including one that suggests up to 38% potential upside from the current price!
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Rio Tinto Group research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Rio Tinto Group. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Rio Tinto Group's overall financial health at a glance.
Looking For More Investment Ideas Beyond Rio Tinto Group?
Once you have formed a view on Rio Tinto Group, it can help to cross check that thesis against other opportunities with similar or contrasting characteristics. The Simply Wall St Screener is built for exactly that kind of comparison.
- If you care most about valuation support, scan a curated set of companies screened for quality and pricing through 16 high quality undervalued stocks that might align with your risk and return preferences.
- If balance sheet resilience comes first for you, narrow the field to businesses with stronger financial footing by using the list of solid balance sheet and fundamentals (9 results) to stress test your watchlist.
- If you are building an income focused portfolio, zero in on higher yielding opportunities with more robust payouts through the targeted 6 dividend fortresses and compare how those cash flows stack up over time.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com