


Havas (ENXTAM:HAVAS) has put leadership changes in the spotlight after promoting W. Joe DeMiero to CEO of Havas North America, Creative and Media, adding a fresh angle for investors tracking the stock.
Recent price action has been more subdued, with the share price return down 6.02% over the past 90 days and the latest close at €17.95. However, the 1 year total shareholder return of 28.37% points to momentum that has built over a longer stretch rather than faded in recent weeks.
Scan how Havas compares to other media and marketing players by reviewing a curated 572 high quality undiscovered gems that may be moving under most investors' radar.
Bulls view Havas as a solid communications group trading below some estimates of fair value. Bears highlight the recent 90-day share price decline. Which case does the valuation appear to support?
Price-to-Earnings of 8.8x: Is it justified?
On the numbers, Havas looks cheap against its own earnings profile, with the stock trading on a P/E of 8.8x at a share price of €17.95.
The P/E ratio compares the current market price to annual earnings per share and is a common yardstick for marketing and media groups where profit generation is a key focus. A lower multiple can indicate that investors are not currently willing to pay as much for each euro of profit as they do for comparable businesses.
For Havas, that 8.8x multiple sits well below the estimated fair P/E of 16.1x from the SWS framework. This suggests room for the valuation to move closer to that fair level if earnings quality and growth trends remain intact.
The gap to peers is also wide. Management is running on a P/E of 8.8x compared with a 25.9x peer average and 15.6x across the broader European Media industry. This points to the market applying a heavy discount rather than simply marking the stock in line with sector norms.
Explore the SWS fair ratio for Havas.
Result: Price-to-Earnings of 8.8x (UNDERVALUED)
Still, revenue growth of 1.01% and earnings growth of 9.05% leave little room for disappointment if client budgets tighten or media spend becomes more volatile.
Find out about the key risks to this Havas narrative.
Another View on Havas: Cash Flow Paints an Even Cheaper Picture
While the P/E of 8.8x points to Havas trading below its earnings profile, the SWS DCF model goes further, with an estimated future cash flow value of €38.48 against a market price of €17.95. That gap suggests a deeper discount. The open question is whether the cash flow assumptions hold up.
Look into how the SWS DCF model arrives at its fair value.
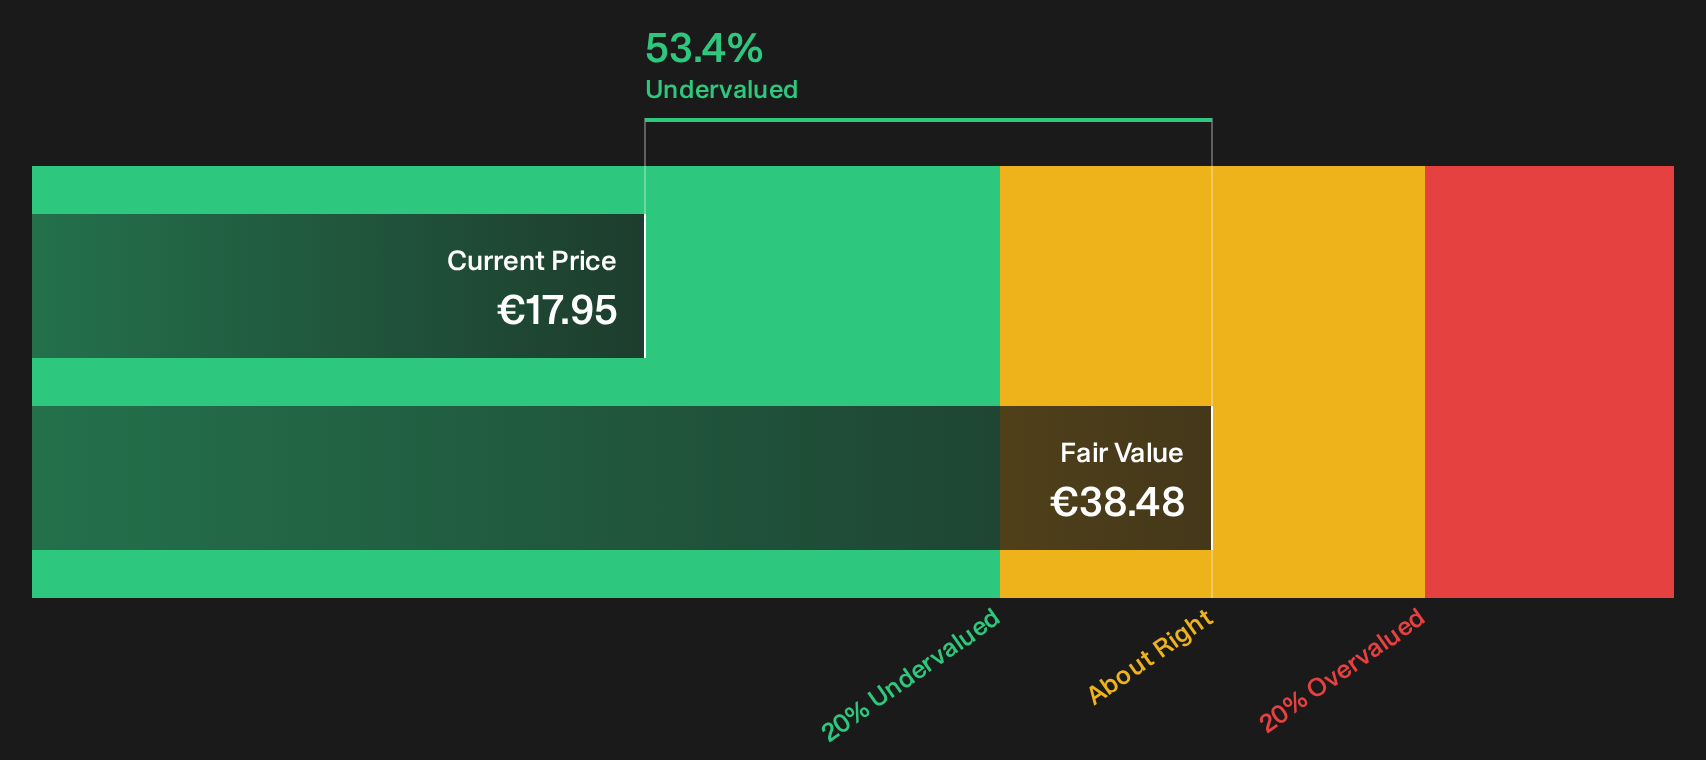
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Havas for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 209 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Feeling the mixed tone around Havas, with low multiples and at least one clear reward in the mix, you can move fast and pressure test the numbers yourself. To see what sits behind that optimism, review the 4 key rewards
Looking for more Havas-sized investment ideas?
Do not stop with Havas. Put the same disciplined lens over fresh opportunities so your watchlist keeps working for you long after this article.
- Target resilient upside while keeping an eye on valuation by scanning a 209 high quality undervalued stocks that filters for quality first.
- Prioritise capital preservation and sleep better at night with a 202 resilient stocks with low risk scores focused on sturdier business profiles.
- Strengthen the foundation of your portfolio by reviewing a list of solid balance sheet and fundamentals (194 results) that screens for durable financial footing.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com