


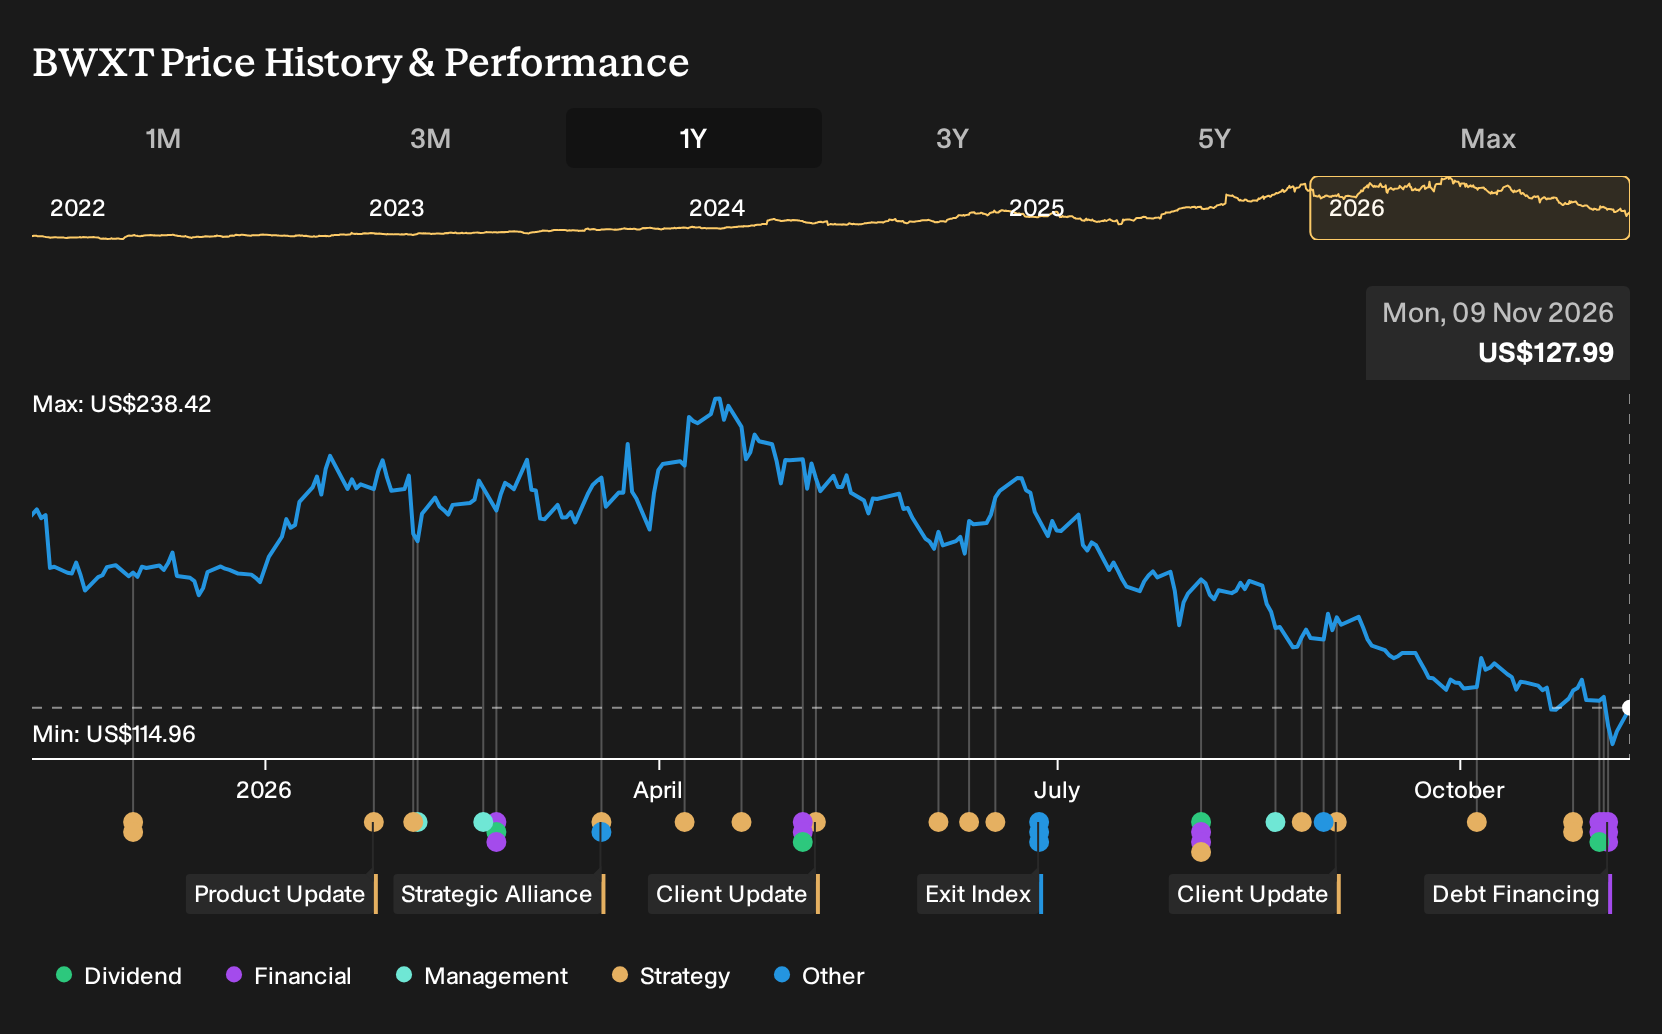
If you had backed BWX Technologies at the start of this review period, the outcome would have been painful. Holding BWX Technologies over the past year would have meant a 35.2% loss, including dividends. That decline came even as later news highlighted large defense contracts, microreactor wins, and fuel supply deals. If the original thesis leaned on high teens revenue growth, rising margins to 12.9%, and a steady 50.4x P/E, what exactly did that optimism miss?
This theme extends beyond BWX Technologies. See which of 17 nuclear energy infrastructure stocks may still merit a closer look.
The Two Stories Investors Had To Weigh On BWX Technologies
BWX Technologies shares cost US$194 at the start of the period, and investors were effectively choosing between an upbeat clean energy narrative and a more cautious regulatory story.
The bullish view saw a Fair Value of US$233, the price implied if its assumptions played out, built on the idea that high teens annual revenue growth and margins rising to 12.9% could support a future P/E of 50.4x on projected 2028 earnings of US$565.9 million.
The bearish narrative pointed to a Fair Value of US$110, framed as the level consistent with slower 9.2% yearly revenue growth, only modest margin expansion to 11.3%, and the risk that heavy reliance on U.S. government and Navy contracts could undermine earnings if policy priorities shifted.
What The Results Changed For The BWX Technologies Story
BWX Technologies landed fresh evidence for the upbeat case when the U.S. Army picked its Advanced Nuclear Reactor for the Fort Campbell Janus program and later agreed a multi year, US$2.2b contract for rail shippable microreactors. Q3 2026 results showed revenue and net income higher than Q3 2025, with net margin rising from 9.5% to 10.7%. The evidence cut both ways but leaned optimistic.
The key assumption tested here was whether growth stories rest on contracted demand or on share price mood. For another stock with an ambitious forecast, it may be useful to track signed backlog, multi year agreements, and reported margins against the original thesis rather than assuming future projects will arrive on schedule or at hoped for profitability.
What You Are Paying For In BWX Technologies After The Fall
BWX Technologies now trades at US$128, with this one year period leaving holders down 35.2%. The analyst consensus Narrative on Simply Wall St sees its fair value above that level, based on how much of the current nuclear backlog and long cycle work it expects to translate into cash generation.
The same Narrative leans on BWX Technologies using its government backed contract base to help fund commercial operations. For the decline to suggest potential opportunity rather than warning, a buyer today would have to believe backlog conversion and commercial expansion can support the business case that Narrative presents.
"Record backlog of about US$8.4b, supported by a trailing 12 month book to bill ratio of 1.7x and roughly nine quarters of revenue coverage, points to continued conversion of awarded work into higher revenue and earnings for BWX Technologies."
Not everyone reads the same price the same way. → See the higher figure this Narrative lands on, and how it gets there
Go Straight To The Source
Passing on this one could have spared you a loss. Where might you find the opposite surprise? Start looking for companies whose prices leave room for a better outcome than investors expect. These three trade below our estimated value.
- Company 1 - 37% below our estimate - shifts enterprise networking and data workloads onto higher-margin recurring service contracts.
- Company 2 - 31% below our estimate - scales device refurbishment and trade in programs that channel units into direct retail.
- Company 3 - 40% below our estimate - expands digital payment connectivity so merchants can route transactions through more local rails.
That is three of the list. See the full list of 33 companies trading below our fair value estimates →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com