


Federated Hermes (FHI) reported higher third quarter and year-to-date revenue and net income compared with 2025, and also confirmed a regular US$0.38 per share cash dividend for November 2026.
The earnings release and dividend confirmation on 29 October have come alongside a strong run in Federated Hermes' share price. A 1-month share price return of 14.92% and year-to-date share price gain of 24.02% have helped lift the 1-year total shareholder return to 34.14%. A very large 3-year total shareholder return of about 13x signals that momentum has been in place for some time but is now drawing fresh attention to how much future growth and risk are already reflected in the current US$64.95 level.
Scan how Federated Hermes stacks up against a hand picked group of income and quality plays by running the 6 dividend fortresses alongside your own watchlist.After a 3 year total shareholder return of about 13x and a share price above the average analyst target, the real question now is where fair value for Federated Hermes actually sits in that spread.
Most Popular Narrative: 6% Overvalued
On the Simply Wall St analyst consensus Narrative, Federated Hermes carries a fair value of $61, which sits below the recent $64.95 close. The focus therefore shifts to whether the underlying growth engines justify that gap at an 8.06% discount rate.
Expansion of MDT quantitative equity strategies into UCITS and ETF wrappers, supported by record gross sales of US$6 billion and over US$3.5 billion in net sales in Q2 2026 with strong three year rankings, positions Federated Hermes to grow fee based equity revenue and support earnings.
See why 8 investors see Federated Hermes as 6% overvalued.
Result: Fair Value of $61 (OVERVALUED)
Still, the Federated Hermes story can change quickly if fee compression in active products intensifies or money market fund flows become more volatile again.
Find out about the key risks to this Federated Hermes narrative.
Another View On Federated Hermes
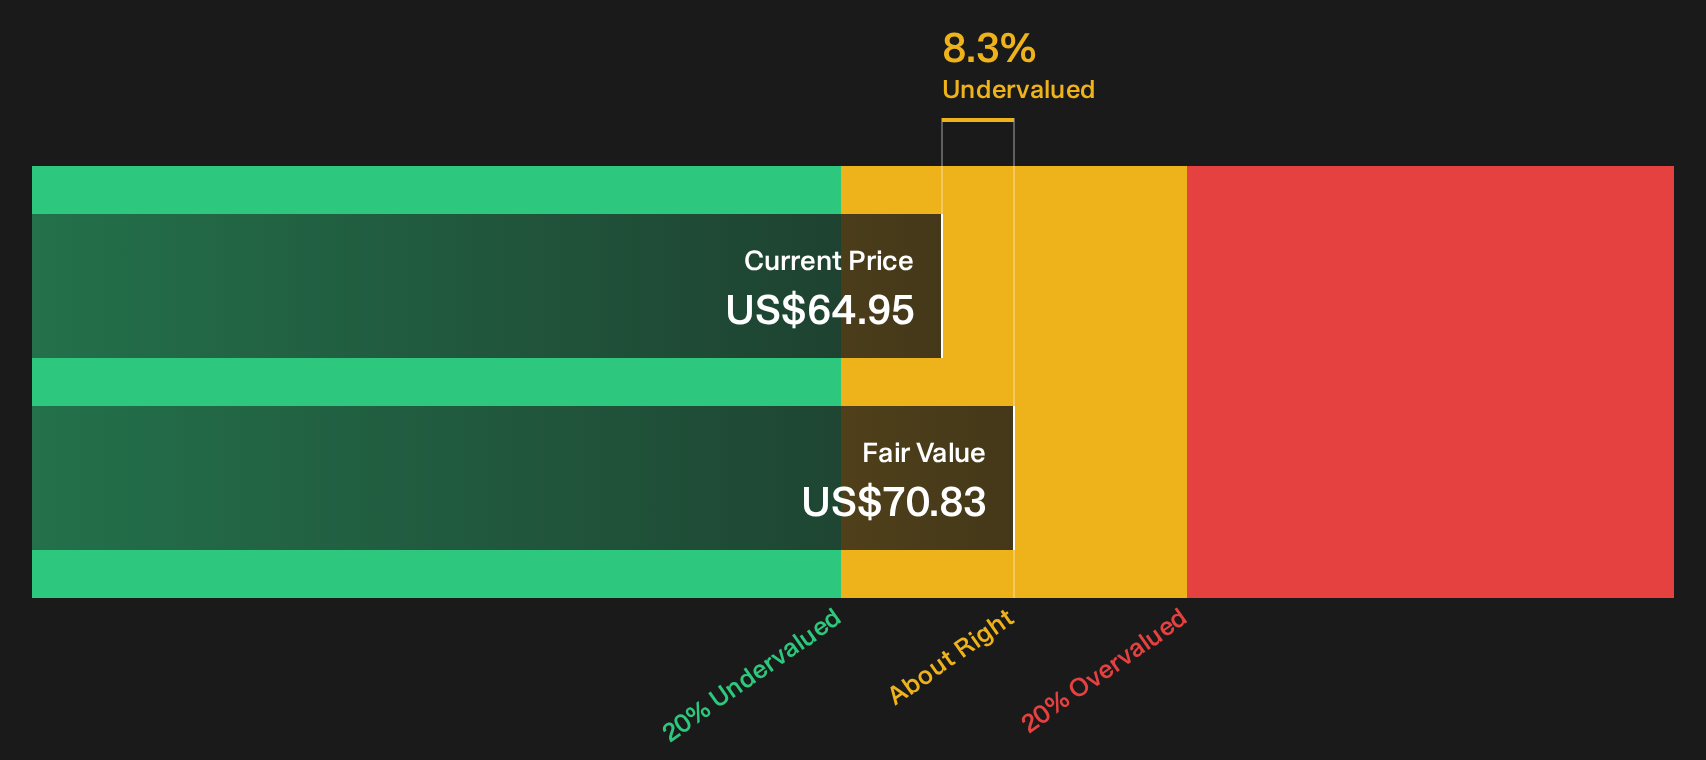
While the Simply Wall St narrative tags Federated Hermes as about 6% overvalued at $61, the SWS DCF model points the other way. On that cash flow view, FHI at $64.95 trades roughly 8% below an estimated $70.83 value. That sets up a clear question: Are you more comfortable with earnings multiples or long term cash flows?
Look into how the SWS DCF model arrives at its fair value.
Next Steps
Mixed views on Federated Hermes so far. If you want to move fast and build your own take on the risk and reward balance, weigh the data against the 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Federated Hermes?
Do not stop your research with Federated Hermes. The market will not wait, and you should not either, especially when curated idea lists are already built for you.
- Target long term compounding by scanning a curated pool of resilient cash generators via the 33 high quality undervalued stocks.
- Prioritize financial strength first and filter for balance sheets that can handle shocks using the list of solid balance sheet and fundamentals (25 results).
- Look for lesser known opportunities with strong fundamentals by working through the 19 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com