


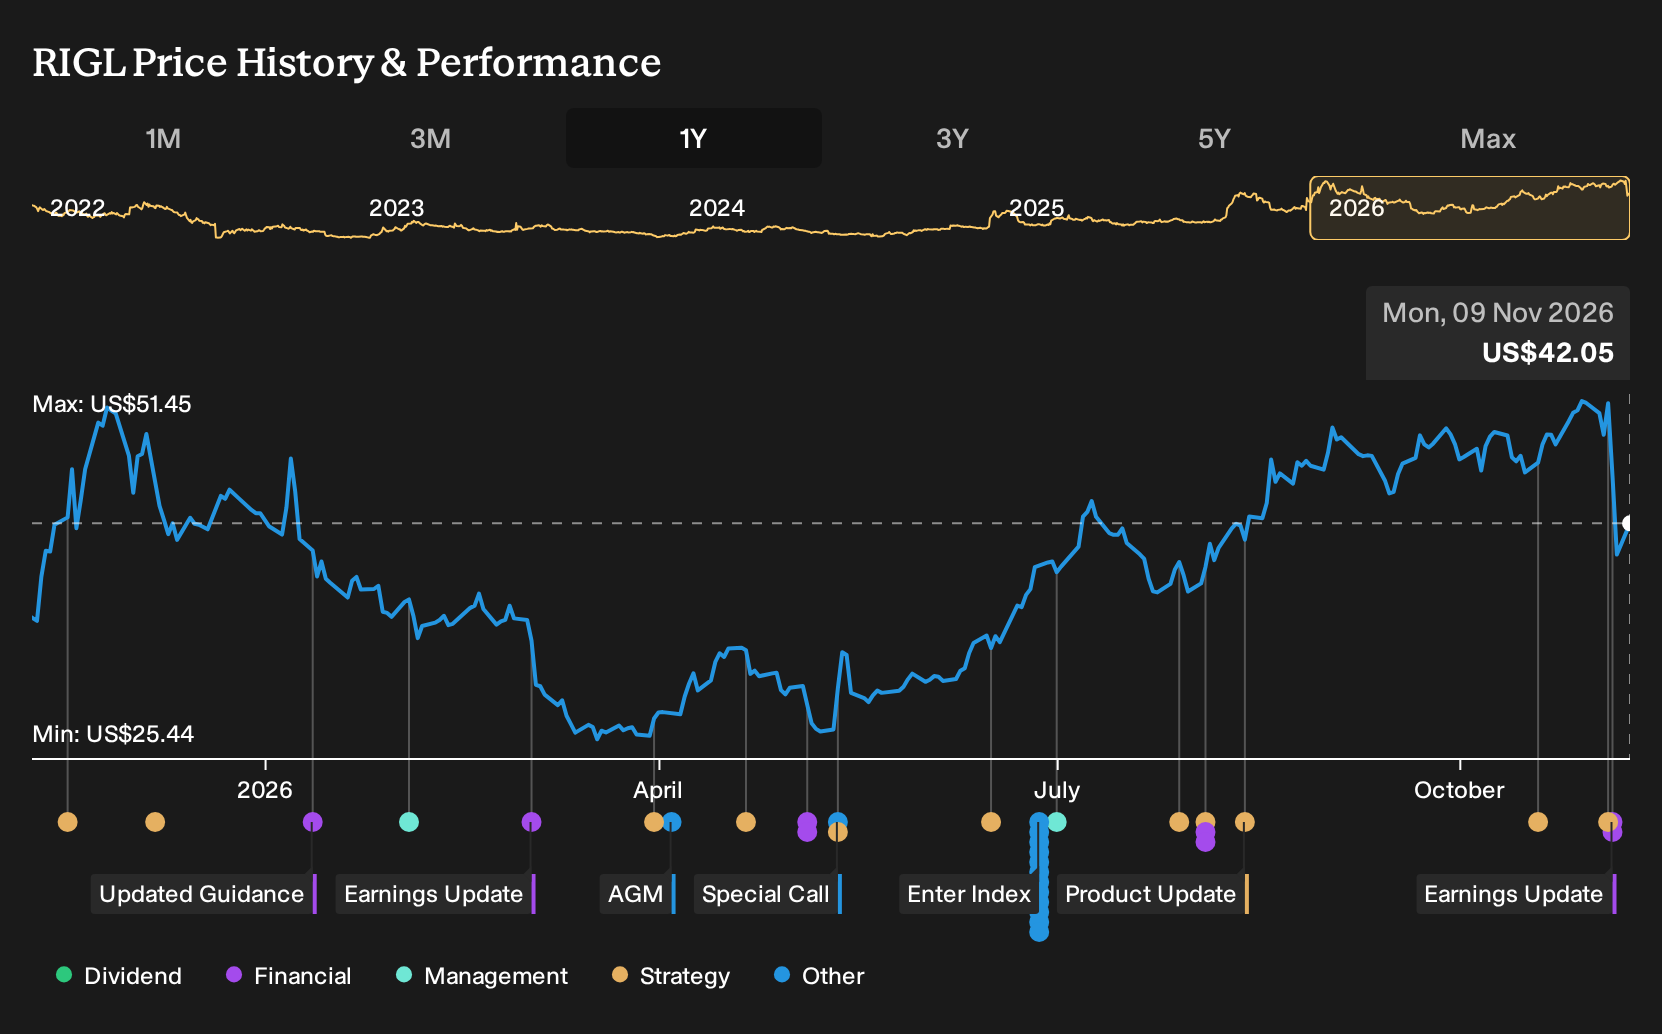
Rigel Pharmaceuticals spent this past year reshaping its future around VEPPANU, the newly licensed oral PROTAC for ESR1-mutated breast cancer, even as its existing portfolio kept the lights on. For Rigel Pharmaceuticals shareholders, the return over the past year was 21.7%, including dividends. If you were deciding back on 2025-11-09 whether to buy, you had to ask what it meant to back a small biotech taking on a costly, global oncology launch.
A Narrative on Simply Wall St is one investor's written case for a company, with its growth, margin and multiple assumptions spelled out. Those assumptions imply an estimated Fair Value.
Rigel Pharmaceuticals has already moved. Pinpoint other ways to investigate the theme among 36 healthcare AI stocks.
The Argument You Would Have Been Weighing Up On Rigel Pharmaceuticals
The shares cost US$35.19 at the start of the period, and Rigel Pharmaceuticals sat between two very different stories about where it might head next.
On the optimistic side, one narrative saw fair value at US$38.33, which was 9% above the start price, built on revenue growth of 3.5% a year and profit margins settling at 14.3% with a future P/E of 20.9x.
The bearish view put fair value at US$22.02, 37% below the start price, and focused on earnings pressure from a decline in revenue of 0.8% a year and margins drifting to 12.9% even if the shares traded on a 14.9x P/E.
What The Evidence Did To The Rigel Pharmaceuticals Argument
The VEPPANU licensing deal gave Rigel Pharmaceuticals a new FDA approved oncology product and backed the bullish focus on portfolio expansion, yet the upfront and milestone commitments also echoed bearish worries about funding pressure. Q3 2026 results added another wrinkle. Revenue reached US$80.89m versus US$69.462m a year earlier, while net income fell and net margin compressed from 40.2% to 16.3%, so the period cut both ways.
The key assumption investors can reuse elsewhere is how added products are meant to translate into durable profitability. When judging another biotech, track whether new assets coincide with higher revenue but also stable or improving net margin in the following filings, rather than relying only on headline pipeline news.
What Rigel Pharmaceuticals' Recent Run Leaves You Paying For
Rigel Pharmaceuticals now trades at US$42.05 after a 21.7% gain over the past year, and the analyst consensus Narrative on Simply Wall St places its Fair Value above that level based on business assumptions rather than any guarantee.
That Narrative leans on the shift from promise to active commercialization, with VEPPANU and R289 layered onto an existing three drug franchise. A buyer today would need to judge whether hematology oncology product sales and partnerships can keep supporting that broader earnings base.
"The expansion and diversification of Rigel Pharmaceuticals' commercial portfolio has moved from aspiration to execution, with three marketed hematology and oncology drugs generating $67 million of U.S. net product sales in Q2 2026. Management is now guiding to $255 million to $265 million of net product sales for 2026, which can provide a larger base of recurring revenue and operating leverage as additional assets contribute."
The price and this Narrative do not agree. → Uncover what this Narrative says Rigel Pharmaceuticals is actually worth
Looking Beyond Rigel Pharmaceuticals
Rigel Pharmaceuticals points you toward a clear theme. Cancer and chronic disease treatments keep demanding fresh tools.
One large drug maker is leaning on a broad late stage pipeline. It is trying to turn new oncology approaches and vaccines into future pillars.
The same group is pushing into heart and metabolic disease. An oral cholesterol drug and changing treatment targets aim to reach patients still not at goal.
It is also folding AI into drug design, chasing faster and cheaper development. If that mix works, the business model around blockbuster loss could look very different.
It is written up in full, assumptions and all. → Explore the Narrative that puts this company 25% above its price
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com