


China plans to pour about $940b into cleaner energy and grid upgrades in 2026, and that kind of massive capital shift can reward businesses that are already growing fast with owners who keep plenty of skin in the game. Investors who want growth supported by confident insiders may find this especially interesting. This article highlights three such fast expanding, high insider ownership stocks from our screener.
The three stocks highlighted here offer a compelling starting point if you want exposure to fast growing businesses where management ownership is aligned with outside shareholders. However, if you want the standouts, these 380 high growth high conviction stocks are the most outstanding.
CoreWeave (CRWV)
Overview: CoreWeave runs a cloud platform built around large-scale GPU computing for AI training and inference, plus related storage, networking and managed services.
Operations: CoreWeave reports US$7.59b of revenue from Data Processing, with US$7.01b generated in the United States and US$577m from other countries.
Market Cap: US$25.59b
CoreWeave matters for this screener because its AI focused cloud platform directly ties revenue to the same GPU infrastructure boom that analysts and management expect to keep expanding. WIn2026, an investor in the Simply Wall St Community, argues that this growth story comes with very specific financial trade offs investors need to understand.
"The business model appears to be an extremely capital-intensive leasing play. NVDA maintains a dominant position, requiring upfront cash without credit terms."
What really tests CoreWeave’s potential is how that heavy funding model interacts with one unresolved pressure on future cash generation and flexibility.
That funding pressure is only one piece of the puzzle, and the full narrative for CoreWeave shows how CoreWeave could still turn capital intensity into accelerating opportunity.

Sansan (TSE:4443)
Overview: Sansan provides cloud-based contact and document management tools that help Japanese businesses digitize business cards, contracts, and invoices to support recurring SaaS revenue.
Operations: Sansan generates about ¥48.9b in revenue from the Sansan and Bill One segment, with total sales of roughly ¥56.2b almost entirely in Japan.
Market Cap: ¥274.8b
Sansan offers exposure to a SaaS contact platform, with earnings reported as rising strongly and management providing guidance for higher net sales and profits through 2027. That combination of recurring contracts, insider alignment, and an upbeat outlook places significant emphasis on how one unseen pressure may influence future pricing power and margin strength.
That hidden pressure on Sansan’s pricing power makes the 3 key rewards and 1 important warning sign a quick way to identify where growth ambitions may conflict with margin realities.

Micronics Japan (TSE:6871)
Overview: Micronics Japan develops probe cards, wafer probers and other semiconductor test gear, alongside body measuring and display inspection equipment worldwide.
Operations: Micronics Japan generates about ¥84,868 million from its Probe Card Business and ¥1,391 million from TE Business, primarily across Asian semiconductor hubs.
Market Cap: ¥345.9 billion
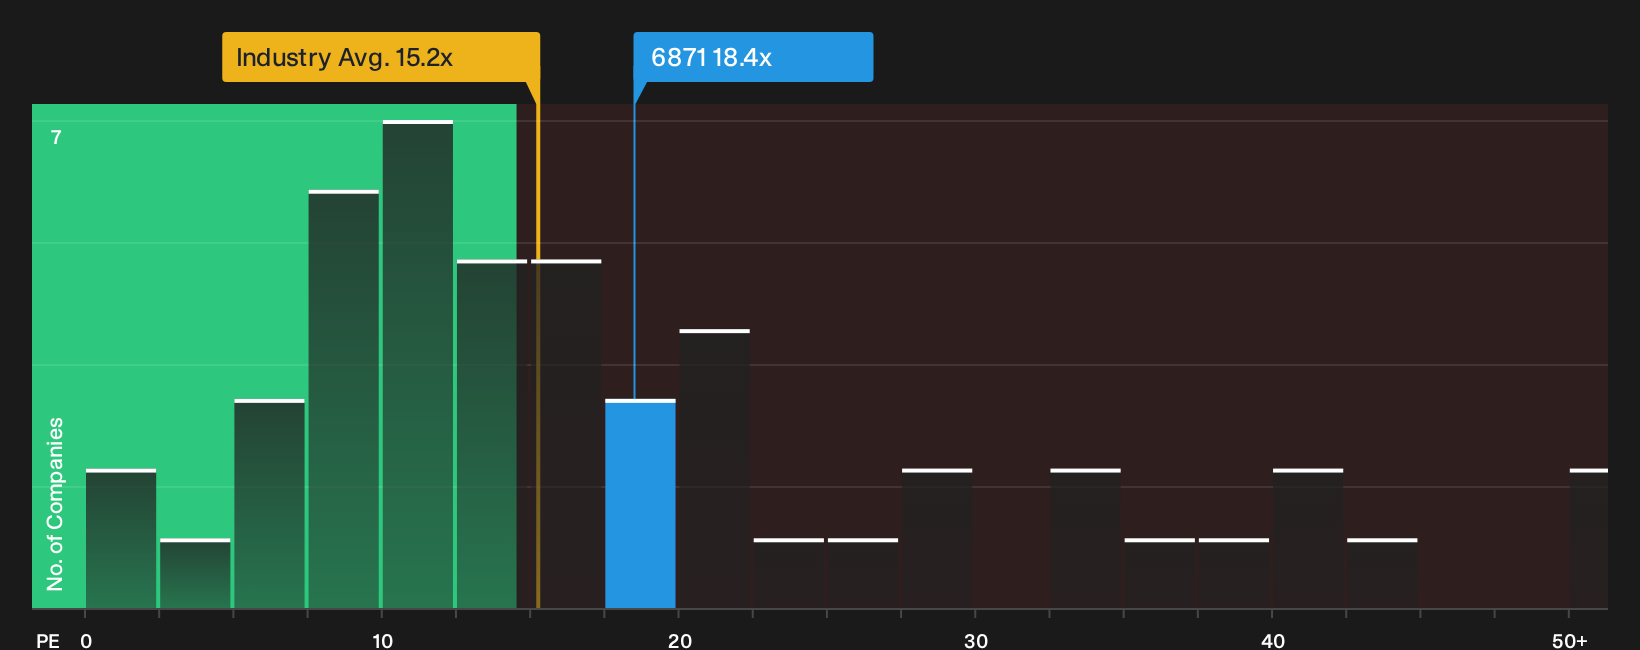
Micronics Japan combines high margin semiconductor test equipment with forecast earnings growth around 24.9% a year and guidance tied to generative AI driven memory demand. That mix fits the fast growth and insider alignment theme. However, a premium P/E and dividend coverage that relies on strong cash generation mean much depends on how one powerful chip capex cycle unfolds.
So much hinges on that chip capex cycle, and the 2 key rewards and 2 important warning signs (1 is major!) shows where Micronics Japan’s premium terms could either accelerate or stall your thesis.
Seeking Fresh Alternatives Before They Fly
New themes gain momentum fast and laggards often get caught chasing late breakouts. Scan fresh ideas that remain under the radar for now and position while it matters, act now.
- Spot income workhorses built for durability and let the 6 dividend fortresses guide you toward yield opportunities before the crowd starts bidding them up.
- Track emerging AI momentum where profits already matter and use the 42 profitable AI stocks that aren't just burning cash to zero in on cash generative potential breakout candidates.
- Hunt for potential future compounders with sturdy balance sheets and move through the list of solid balance sheet and fundamentals (25 results) before shifting conditions change the window for quality at a reasonable entry point.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com