


- Iridium Communications recently reported quarterly revenue growth of 8.3% year over year, with earnings per share rising 180%, alongside a P/E of 27.3 and a dividend yield of 1.37%.
- The combination of strong earnings momentum and an analyst revenue growth forecast of 8.5% is putting fresh attention on how Iridium Communications converts its satellite network and service portfolio into durable cash generation.
- We will now look at how Iridium Communications' sharp earnings acceleration might reshape the investment narrative built around its satellite services.
Contrast Iridium Communications' earnings surge and dividend with other income ideas by scanning our hand-picked 6 dividend fortresses built for yield focused investors.
Iridium Communications Investment Narrative Recap
To own Iridium Communications, you need to be comfortable with a business that leans heavily on recurring satellite service revenue while working to broaden usage in areas like IoT, assured PNT and NTN Direct. The recent 8.3% revenue growth and 180% EPS jump support that story, but the analyst consensus Narrative on Simply Wall St still highlights modest top line expectations.
The most immediate catalyst remains how effectively Iridium Communications turns its existing L band network and newer offerings into consistent service revenue and EBITDA. This is particularly relevant given that guidance previously pointed to flat to 2% service revenue growth by 2026. A key risk sits around mix and timing, from maritime ARPU pressure to uneven PNT revenue recognition, and this update does not remove those concerns.
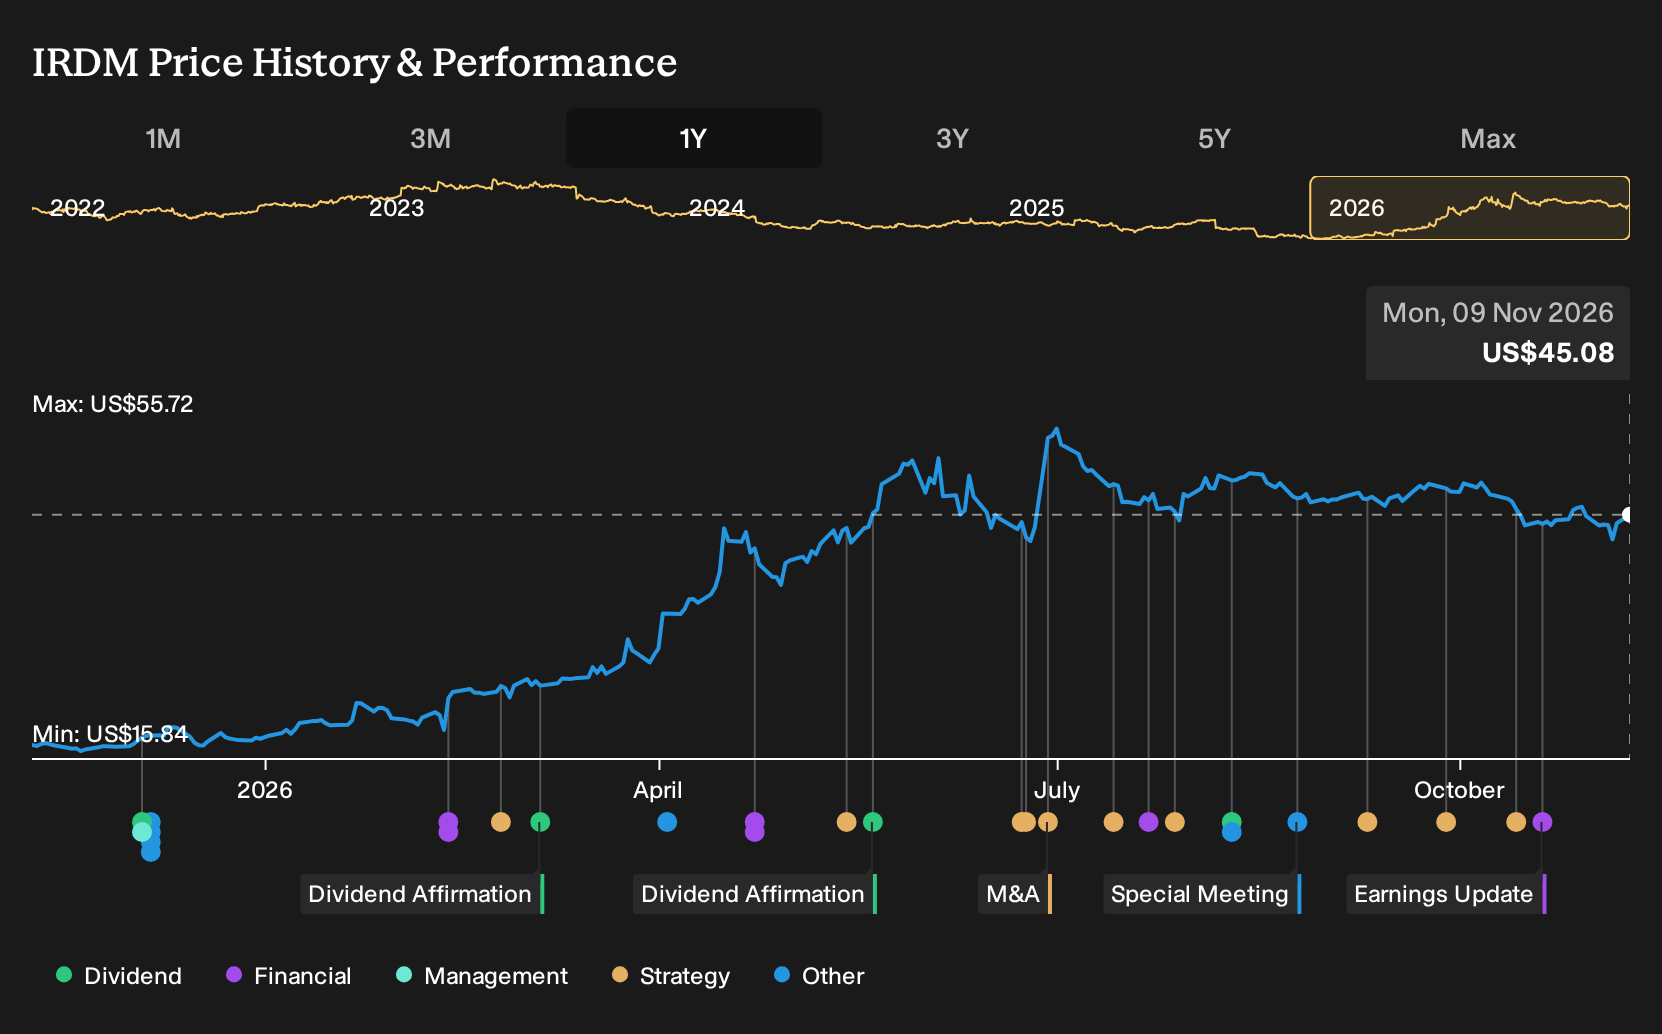
One of the most important moving parts in that backdrop is the proposed Rocket Lab acquisition. This values Iridium Communications at about US$8b, or US$54 per share, in the analyst consensus Narrative on Simply Wall St. That figure leans on already high operating EBITDA margins and meaningful free cash flow generation from the satellite platform.
This proposed deal ties directly into the current catalysts and risks. Integration costs, capital needs and the execution of combined growth projects could influence how much of Iridium Communications' current earnings power actually reaches the bottom line over time. If service growth in PNT, NTN Direct and Aireon integration progresses more slowly, the premium valuation implied by that transaction could look demanding relative to delivered results.
Iridium Communications' current analyst narrative points to forecast revenue of US$1.1b and earnings of US$77.7 million by 2029, based on an assumed 6.3% yearly revenue growth rate. That view compares earnings today of US$163.0 million with the 2029 consensus, which implies an earnings decline of US$85.3 million over the period rather than an increase.
Uncover why Iridium Communications' fair value indicates a 6% potential upside to its current price before other investors close that gap.
Exploring Other Perspectives
One alternate view on Iridium Communications focuses on the Rocket Lab deal risk. The most bearish analysts were working off roughly US$1.1b of 2029 revenue and US$143.5 million of earnings before this quarter. That camp sees governance questions and possible deal changes as a bigger issue. This shows how widely opinions can differ and why it makes sense for you to test several narratives yourself.
Explore 5 other Iridium Communications fair value estimates, including one that suggests as much as 32% downside from the current price!
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Iridium Communications research is our analysis highlighting 1 key reward and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Iridium Communications. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Iridium Communications' overall financial health at a glance.
Looking For More Investment Ideas Beyond Iridium Communications?
If the Iridium Communications story has sharpened your sense of what you want in a stock, you can use that same filter to search more widely. The Simply Wall St Screener lets you quickly line up businesses by income potential, balance sheet strength, or under the radar quality so you can build a watchlist that fits your goals.
- For investors who want income without ignoring quality, you can scan a curated set of 6 dividend fortresses that combine higher yields with underlying fundamentals you can scrutinize in one place.
- If capital preservation and steadier profiles appeal more than excitement, you can focus on companies from a 30 resilient stocks with low risk scores that score better on certain risk factors and balance sheet metrics.
- To widen the opportunity set beyond well known tickers, you can sift through a 19 high quality undiscovered gems that highlights under followed businesses with solid financial underpinnings and room for the story to develop.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com