


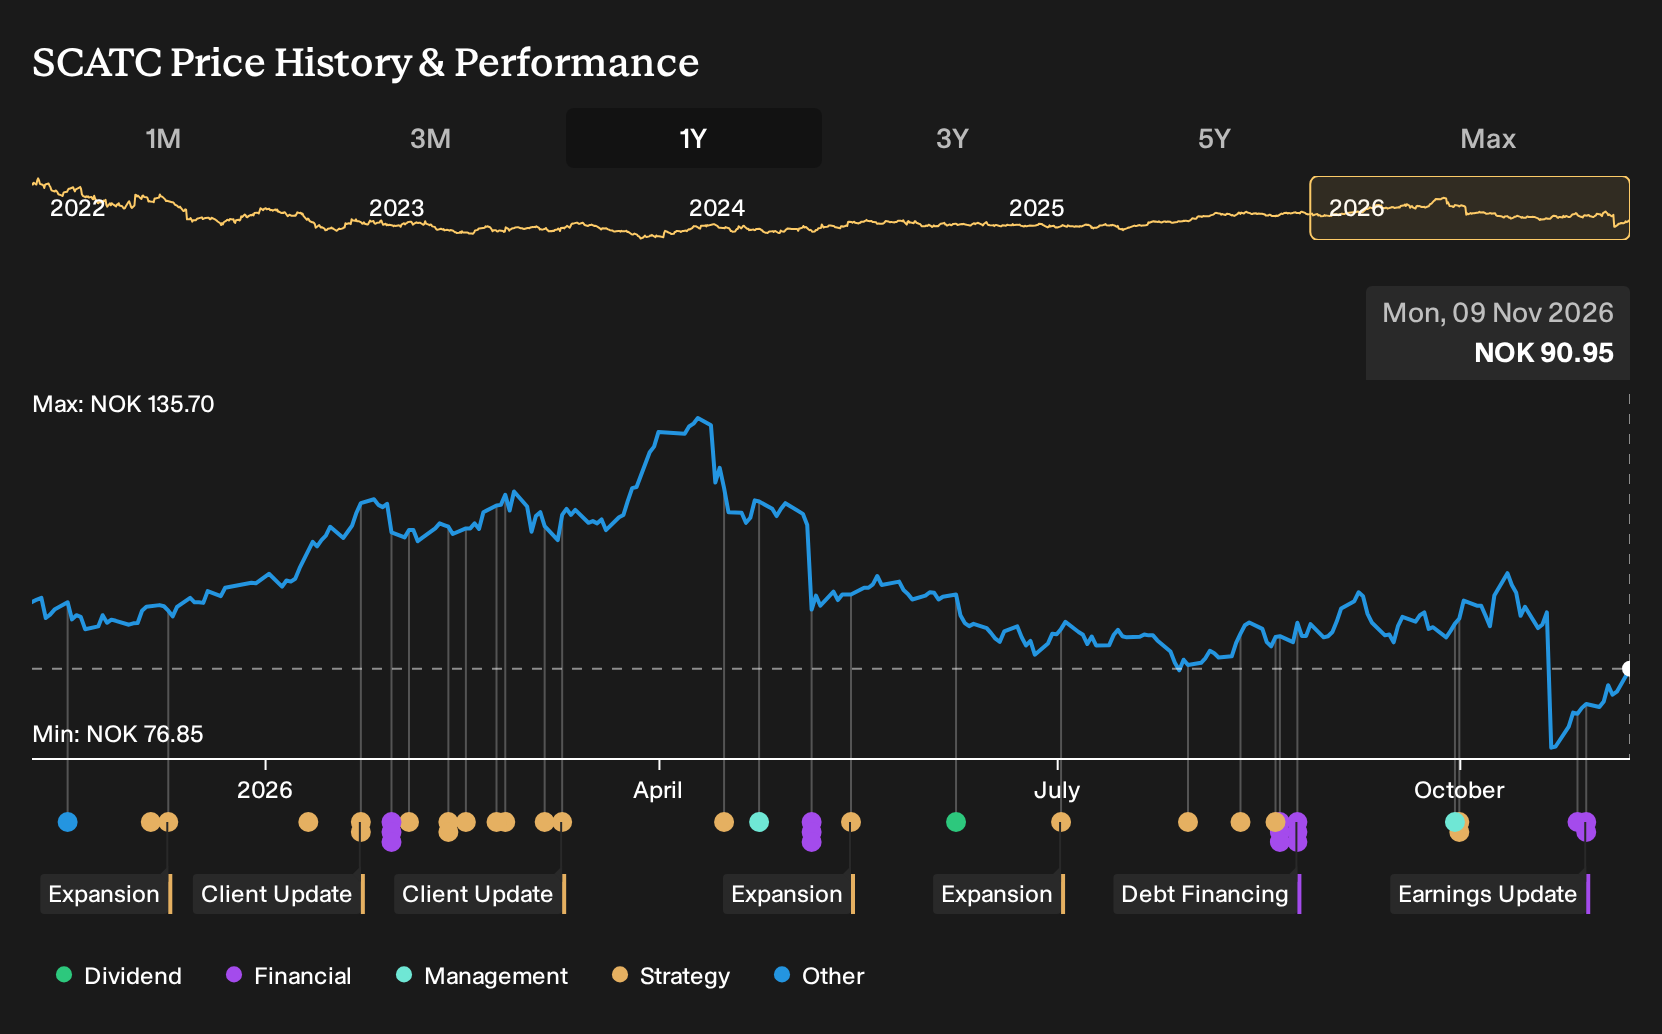
- Scatec reported third quarter 2026 figures with revenue of NOK 1,677 million alongside a net loss of NOK 1,003 million and moved ahead with financing and construction of the Dandara solar and storage project in Egypt.
- The combination of wider losses and a 569 MW solar build in Egypt backed by long term funding and a sovereign guaranteed offtake highlights how Scatec is trying to balance heavy upfront investment with future contracted cash flows.
- The next focus will be on how Scatec's larger quarterly loss shapes its investment narrative, which is built around project execution and deleveraging.
Scan how Scatec's latest loss heavy quarter compares with peers pursuing big-ticket clean energy builds by reviewing the hand picked 42 power grid technology and infrastructure stocks.
Scatec Investment Narrative Recap
To stay invested in Scatec, you need to be comfortable with a renewables developer that is loss making today but heavily skewed toward contracted power assets and a large project pipeline. The analyst consensus Narrative on Simply Wall St leans on execution of that 12.3 GW generation and 6.8 GWh storage portfolio to support revenue and EBITDA as more megawatts move into operation.
The latest quarter complicates that story in the short term. Revenue for the period was NOK 1,677 million, yet the net loss widened to NOK 1,003 million and nine month results also swung from profit to loss. That makes balance sheet pressure and interest coverage the key near term risk, while delivery against Scatec's own 2026 power production guidance becomes the main operational catalyst.
The Dandara agreement in Egypt is the clearest link between the quarter and Scatec's future cash generation. Phase one combines a 569 MW solar plant with 100 MWh of storage and sells electricity to Egypt Aluminium under a 25 year PPA with a sovereign guarantee, which ties directly into the long term contracted cash flow narrative analysts focus on.
On the flip side, Dandara underlines the short term risk in the story. Project capex for the first phase is estimated at US$271 million with about US$217 million in project debt, and Scatec intends to bring in more equity partners and use bridge loans to defer its own cash injection. For you as a shareholder, that keeps execution, financing terms and timing of equity contributions front and center over the next few years.
Scatec's narrative points to NOK 13.0 billion in revenue and NOK 3.0 billion in earnings by 2029, built on analyst assumptions of 49.5% yearly revenue growth and an earnings swing of roughly NOK 3.3 billion from current earnings, which reflect a NOK 282.0 million loss.
Uncover how Scatec's fair value indicates a 43% potential upside to its current price before investors fully recognize that gap in the valuation.
Exploring Other Perspectives
Three fair value estimates from the Simply Wall St Community span roughly NOK 14.57 to NOK 130.38 per share, so Scatec sits under a very wide range of opinions. That spread meets fresh catalysts and risks around Dandara financing, 2026 production guidance and recent loss making results. Explore those contrasting views before drawing firm conclusions.
Explore 2 other Scatec fair value estimates, including one that suggests as much as 84% downside from the current price!
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider developing your own view.
- A great starting point for your Scatec research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Scatec. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Scatec's overall financial health at a glance.
Looking for more investment ideas beyond Scatec?
If the Scatec story has you thinking about position sizing and diversification, it can help to line it up against other opportunities that match different risk and return profiles. The Simply Wall St screener lets you do that in a structured way by filtering for balance sheet strength, valuation and income potential in a few clicks.
- For investors who care most about financial resilience, start with companies highlighted for sturdier finances through the list of solid balance sheet and fundamentals (194 results).
- If value for money is your priority, compare Scatec with candidates trading on more modest expectations by reviewing a curated 209 high quality undervalued stocks.
- Those who want to pair income with staying power can scan a focused 202 resilient stocks with low risk scores to see which stocks align better with a steadier risk profile.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com