


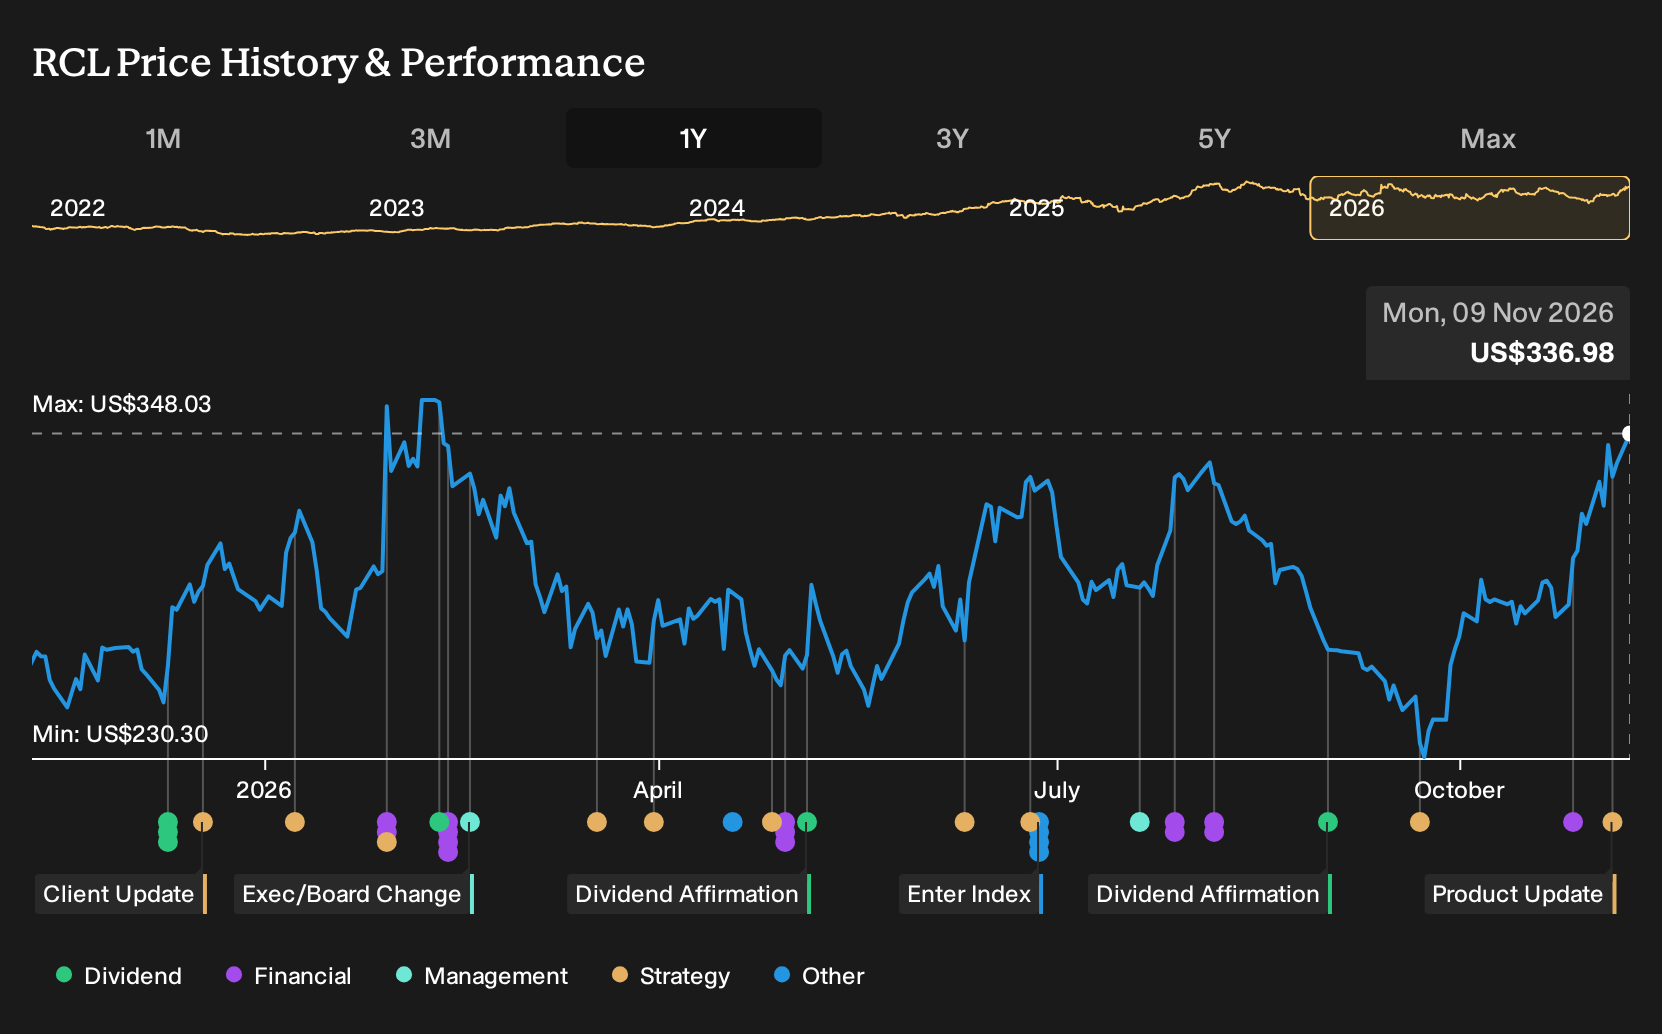
If Royal Caribbean Cruises was on your watchlist rather than in your portfolio, the return may sting. For Royal Caribbean Cruises shareholders, the return over the past year was 29.7%, including dividends. That outcome puts a spotlight on what was already on record in late 2025. Analysts were banking on accelerating earnings momentum as new ships and exclusive destinations rolled out. The real question is whether that confidence in capacity-driven revenue growth was the key clue you would have focused on before any of this played out.
The useful thing about a Narrative is that the reasoning is checkable: the assumptions sit beside the argument, and together they imply an estimated Fair Value you can disagree with.
If the move has made Royal Caribbean Cruises harder to judge, start where the gap is still open and scan 33 high quality undervalued stocks.
The Two Stories Royal Caribbean Investors Had To Weigh
The shares cost US$256 at the start of the period, and Royal Caribbean Cruises sat between two very different but credible narratives about what came next.
On the optimistic side, the October 2025 bull case pointed to a Fair Value of US$356, based on analysts expecting revenue to grow 9.2% a year and profit margins to reach 26.2% within three years as new ships and exclusive destinations supported higher per-passenger spend.
The May 2025 bear case argued for a Fair Value of US$218, noting that tighter climate rules and high capital spending could raise costs, strain a leveraged balance sheet, and limit the scope for profitable capacity expansion.
What The Royal Caribbean Evidence Actually Tested
Royal Caribbean Cruises moved ahead with a US$3b deal for a 50% stake in Sandals and Beaches Resorts, which backed the bullish story about expanding capacity and vacation products. Reported Q3 2026 figures showed revenue of US$5.6b and net income of US$1.7b, with net margin at 30.9%, slightly above 30.6% a year earlier. The period mostly supported the optimistic case but kept costs and capital intensity on the radar.
The lesson is simple. When a growth story leans on capacity and experiences, track two items side by side: reported margin levels, and the size of new commitments such as resort stakes, terminals, or ships.
What Royal Caribbean's Price Already Bakes In
Royal Caribbean Cruises now trades at US$337, well above the US$256 starting point for that one year return. The bearish analyst Narrative on Simply Wall St places its Fair Value below the current price, framing today’s level as demanding rather than neutral.
The Narrative centers on whether flat net yields, cash flow strain, fuel costs, and booking softness could collide with that richer valuation. Anyone paying US$337 is effectively assuming yields, earnings, and balance sheet repair goals hold up. How do those yield and free cash flow risks weigh on that bet?
"As Royal Caribbean Cruises leans more heavily on balance sheet repair, refinancing activity and capital returns, a backdrop of mediocre free cash flow margins and potential yield pressure could restrict the cash available for both debt reduction and shareholder distributions. This would challenge expectations for a smooth transition from deleveraging to sustained capital return without diluting future earnings power."
One Narrative disagrees with today's price. → See where this Narrative says Royal Caribbean Cruises should trade
Where Royal Caribbean’s Story Echoes
Royal Caribbean leans on ships and resorts. Your booking depends on reliable power, everywhere.
Those floating hotels need efficient energy use, similar to factories or data halls. One specialist focuses on chips that manage that power cleanly and precisely.
Its devices help electric vehicles, industrial gear and AI hardware handle heavy electrical loads. The goal is simple and focused. Waste less energy as systems get more complex.
If demand for electrified transport and computing keeps building, smarter power control could matter more widely. That shift might matter more than the cruise headlines suggest.
The case is written up, with the assumptions it depends on. → Discover the robotics company one Narrative values 47% above its price
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com