


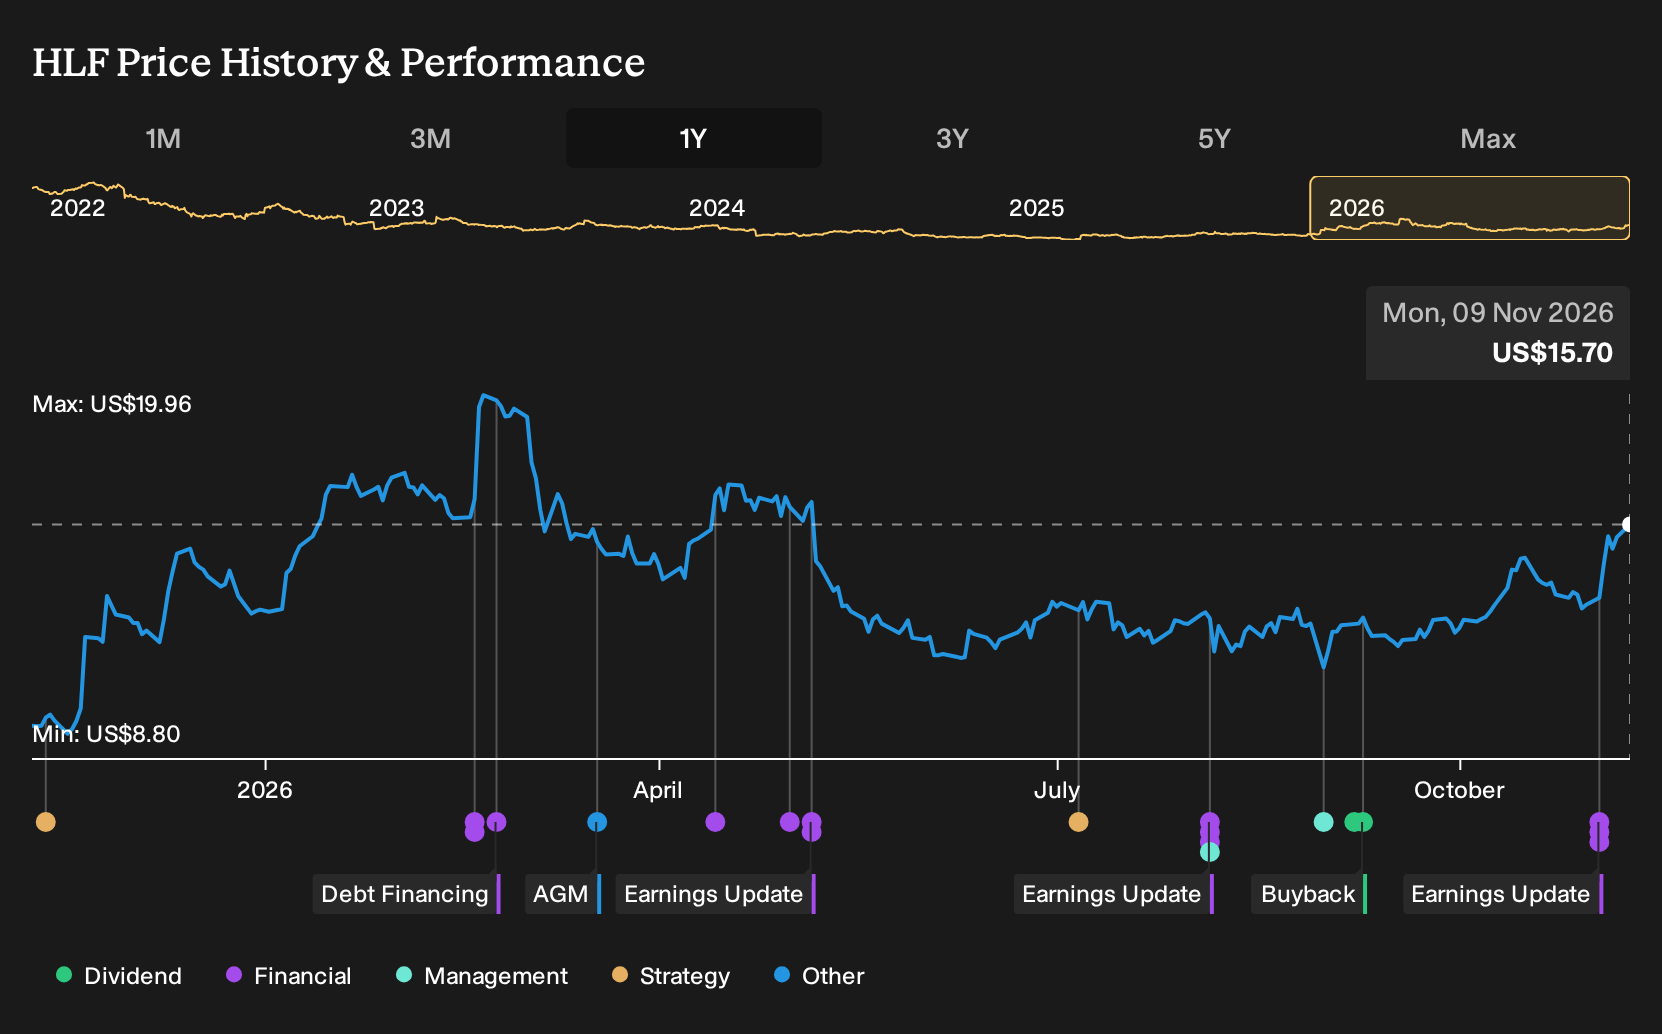
- Herbalife reported third quarter 2026 sales of US$1,350.2 million and net income of US$58.8 million, with both measures above the prior year period. The company issued fourth quarter guidance that frames reported net sales growth between 0.5% and 4.5%.
- Despite net income of US$94.4 million for the first nine months of 2026 being below the prior year period, Herbalife raised full year net sales guidance. This points to management prioritising top line progress while working through profit pressure.
- The focus now is on how Herbalife's stronger third quarter earnings reshape the investment narrative around distributor productivity, digital tools and capital returns.
Herbalife Investment Narrative Recap
Herbalife stock asks you to believe that the personalized nutrition push, digital platforms and distributor productivity work together to keep revenue moving while margins recover from recent pressure. The third quarter showed higher sales and net income than a year ago, though the nine month profit line is still under strain, which keeps execution firmly in focus.
The analyst consensus Narrative on Simply Wall St highlights tools like Pro2col, subscription products and emerging market demand as key to offsetting weaker regions such as China and EMEA. The biggest near term catalyst is evidence that these initiatives lift volumes without further margin slippage. The largest risk is that gross margin and regional softness keep profit growth behind sales progress.
The most relevant update is Herbalife raising full year 2026 net sales guidance to a reported range of +4.9% to +5.9%, from +2.5% to +5.5%. That is presented as a signal that management currently sees more reliable top line momentum than before, even as nine month net income of US$94.4 million trails the prior period.
For catalysts, investors can watch whether this firmer sales outlook flows through to earnings as digital upgrades and higher distributor productivity bed in, or whether gross margin and weak regions absorb most of the benefit. Given negative shareholders’ equity, a high level of debt and recent one off items, any gap between stronger revenue and pressured profitability remains central to the Herbalife story.
Herbalife's narrative projects US$5.6b revenue and US$465.5 million earnings by 2029, which rests on analysts assuming 2.6% yearly revenue growth and earnings rising by about US$301 million from US$164.2 million today.
Uncover how Herbalife's fair value indicates an 8% potential upside to its current price that could narrow quickly if sentiment flips.
Exploring Other Perspectives
For a very different angle, focus on Herbalife’s leadership transition risk. The most bearish analysts worry that the CEO change and new CFO handover could disrupt execution, even though their own models still had revenue reaching about US$5.7b and earnings around US$431.4 million by 2029 before this latest earnings update. You can read those lower forecasts as a sign that some professionals already saw the pre news guidance and balance sheet plans as quite ambitious. With third quarter numbers and the raised sales outlook now on the table, those cautious views may shift or harden. Treat that spread in opinion as an invitation to compare scenarios yourself rather than leaning on any single story.
Explore 4 other Herbalife fair value estimates, including one that suggests it could be worth just $17.00.
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Herbalife research is our analysis highlighting 3 key rewards and 4 important warning signs that could impact your investment decision.
- See our latest analysis for Herbalife. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Herbalife's overall financial health at a glance.
Looking for more investment ideas beyond Herbalife?
Once you have a view on Herbalife, it can help to widen the lens and compare it with other companies that share similar traits on quality, risk or income potential.
- For investors who want income resilience alongside yield, scan a curated set of higher payout opportunities using the 6 dividend fortresses.
- If balance sheet strength matters most to you, filter for companies with robust cash and debt profiles using the list of solid balance sheet and fundamentals (25 results).
- When you want to focus on quality that may be flying under the radar, line up potential ideas with the 19 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com