


- Ryman Hospitality Properties reported third quarter 2026 revenue of US$655.8 million and net income of US$40.21 million, with both basic and diluted earnings per share from continuing operations above the prior year period.
- The key focus is the full year outlook, where Ryman Hospitality Properties lifted guidance for operating income, net income, and diluted earnings per share. This update reinforces management's confidence in the business mix of large group resorts and entertainment assets.
- We will now look at how Ryman Hospitality Properties' raised 2026 net income guidance may reshape the investment narrative that investors have been following.
Scan how Ryman Hospitality Properties stacks up against other lodging and entertainment players by reviewing our hand picked list of 19 high quality undiscovered gems in similar cash generative niches.
Ryman Hospitality Properties Investment Narrative Recap
To own Ryman Hospitality Properties, you need to be comfortable with a capital intensive resort and entertainment platform that leans heavily on large group travel and live experiences. The analyst consensus Narrative on Simply Wall St focuses on that mix, along with high quality earnings and strong advance group bookings, as the core driver. The raised 2026 profit guidance supports that thesis and keeps the main near term catalyst squarely on execution at the Gaylord resorts, JW Marriott properties and Opry Entertainment.
The biggest operational risk right now is still the spend and financing tied to Grande Lakes Orlando and the wider US$400m to US$500m capex plan. Those projects need to justify the higher share count, interest costs and ongoing renovation needs. The latest outlook upgrade helps, but it does not remove the risk that interest payments and elevated investment could weigh on future flexibility if performance moderates.
The full year guidance lift is the most relevant announcement for assessing Ryman Hospitality Properties after this earnings release. Management now expects 2026 consolidated operating income of US$561.2 million to US$572.4 million and net income of US$287.0 million to US$293.5 million. Diluted net income available to common shareholders per share is guided to US$4.06 to US$4.09. Those figures provide a clear, updated profitability yardstick against which to judge the Grande Lakes and capex program.
The same guidance range also speaks directly to the catalysts highlighted in the analyst consensus Narrative on Simply Wall St, which emphasizes advance group bookings, resort scale and Opry Entertainment as key earnings drivers. The higher net income outlook indicates that the current business mix is aligned with that story in the near term. The open question for you as an investor is how much room remains for execution missteps on large projects and interest coverage before that narrative would need to be reassessed.
What The Long Term Assumptions Say About Ryman Hospitality Properties
Ryman Hospitality Properties' longer term story in the analyst models leans heavily on rising revenue, higher profit margins and steady capital investment all working together. Instead of only reacting to the latest guidance lift, it helps to look at what those assumptions imply about the size and profitability of the business a few years out and what kind of earnings power would need to show up for that story to hold.
Analysts building out this view are using a 10.3% annual top line growth rate over the next three years and an increase in profit margins from 9.9% today to 12.7% by year three. The forecast path has earnings today at US$271.9 million and consensus earnings in 2029 at US$466.3 million. That is an earnings increase of about US$194 million from current levels, which is the step up that has to materialize if the broader narrative around the Gaylord resorts, JW Marriott resorts and Opry Entertainment is going to translate into the income statement.
Ryman Hospitality Properties' narrative projects US$3.7b revenue and US$466.3 million earnings by 2029. This requires 10.3% yearly revenue growth and an earnings increase of about US$194 million from US$271.9 million.
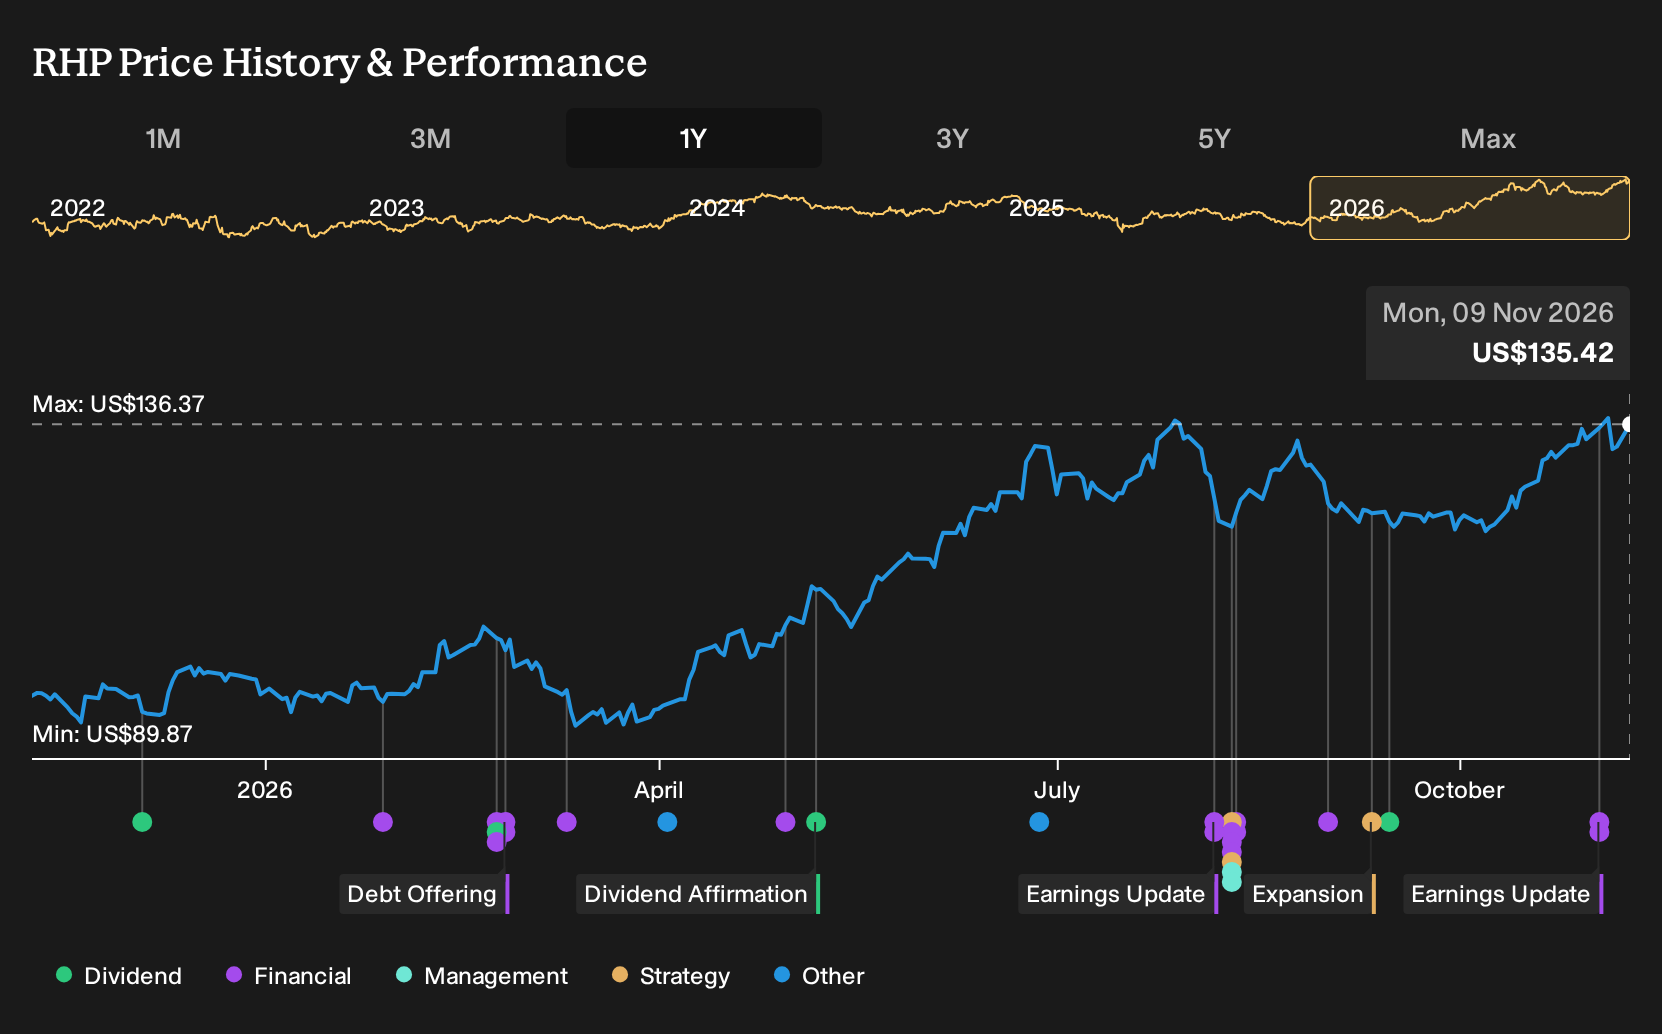
Uncover why Ryman Hospitality Properties' fair value indicates a 3% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
Two fair value estimates from the Simply Wall St Community span roughly US$140 to US$218 per share, so you are seeing a wide gap between the lowest and highest conviction views. Combined with rising capex, higher interest obligations and evolving group demand, it becomes clear that Ryman Hospitality Properties invites you to review multiple viewpoints before forming your own stance.
Explore another Ryman Hospitality Properties fair value estimate, including one that suggests as much as 61% upside from the current price.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider forming your own view.
- A useful starting point for your Ryman Hospitality Properties research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Ryman Hospitality Properties. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easier to evaluate Ryman Hospitality Properties' overall financial health at a glance.
Looking For More Investment Ideas Beyond Ryman Hospitality Properties?
If this update on Ryman Hospitality Properties has sharpened your thinking and you want to broaden your watchlist, the Simply Wall St Screener can help you zero in on other opportunities that suit your approach to risk, income, and balance sheet strength.
- For investors who want potential upside with smaller companies that already have earnings and cash in the mix, scan through 11 elite penny stocks with strong financials that meet tighter quality filters than the typical microcap.
- If capital preservation and steadier business profiles matter most to you, start with a 30 resilient stocks with low risk scores that score well on financial health and risk checks.
- When you care about sensible debt levels and the ability to fund growth internally, work through a list of solid balance sheet and fundamentals (25 results) that combines balance sheet strength with fundamental quality screens.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com