


Antero Midstream (AM) just delivered third quarter 2026 results that reshaped the earnings picture, with higher revenue, sharply higher net income, larger impairments, and updated full year profit guidance that now sits in a higher range.
Despite the stronger third quarter update, Antero Midstream’s share price is up 8.97% year to date to US$19.55. The stock is down 7.30% over 30 days and 11.54% over 90 days, while long-term total shareholder returns of 14.40% over one year and 158.55% over five years indicate momentum that has built over time rather than in recent weeks.
Spot opportunities that echo Antero Midstream’s earnings shift by scanning a hand picked group of 19 high quality undiscovered gems with similar fundamental strength and under the radar momentum.Antero Midstream has re-rated on strong earnings, yet the recent pullback leaves the balance between income appeal and downside risk in focus. Does that combination still favour new buyers once the valuation is on the table?
Most Popular Narrative: 18.5% Undervalued
The analyst consensus Narrative on Simply Wall St puts Antero Midstream’s fair value at $24, above the recent $19.55 close. This frames the current pullback as a valuation gap that hinges on execution around in basin demand, HG Midstream integration, and capital discipline.
Integration of the HG Midstream assets, including about 50 miles of east to west gathering lines and adjacent water infrastructure, is expected to support high single digit EBITDA growth through at least 2027 with limited incremental capital, which can lift earnings and free cash flow.
See why 20 investors see Antero Midstream as 19% undervalued.
Result: Fair Value of $24 (UNDERVALUED)
Still, the whole Antero Midstream story leans heavily on Antero Resources continuing to fill the pipes and on regulators not slowing activity in Appalachia.
Find out about the key risks to this Antero Midstream narrative.
Another View: What The P/E Ratio Says About Antero Midstream
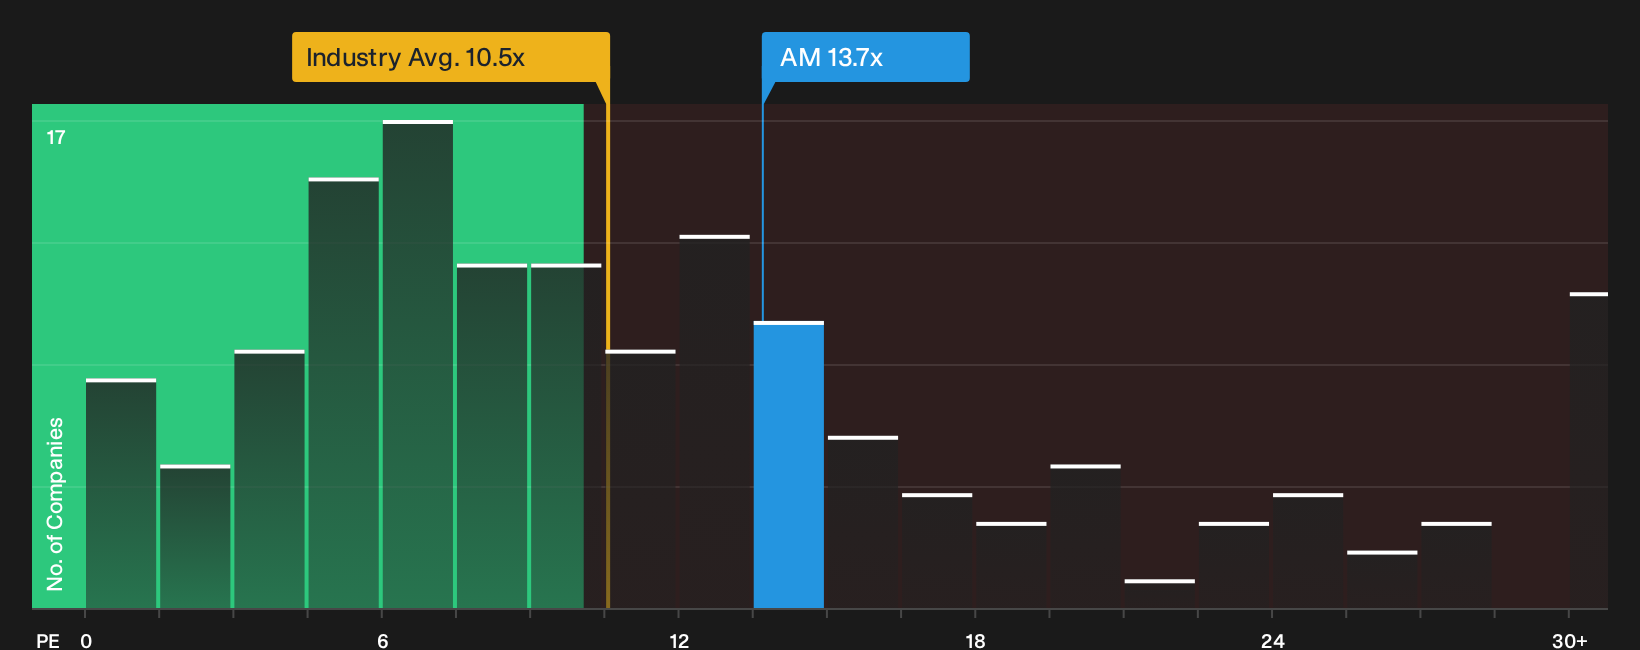
The narrative around Antero Midstream leans on a $24 fair value, yet the current P/E of 13.7x tells a more mixed story. It is higher than the US Oil and Gas industry on 10.5x, slightly below the peer average of 15.6x, and close to a fair ratio of 14.4x. This points to only modest valuation upside and real downside risk if sentiment cools. Which signal do you trust when the income story meets a full looking multiple?
For a closer look at how this earnings multiple stacks up and what the gap to the fair ratio could mean in practice, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment around Antero Midstream is split enough that you should pressure test the numbers yourself and move quickly to your own conclusion. To weigh both sides of the story in one place, start with the 3 key rewards and 4 important warning signs.
Looking for more investment ideas beyond Antero Midstream?
If you only stop at Antero Midstream, you risk missing other potential opportunities that also combine quality fundamentals, income appeal, and measured risk.
- Target steadier compounding by reviewing a curated set of resilient companies through the 30 resilient stocks with low risk scores that aim to keep drawdowns in check.
- Pinpoint potential value opportunities early by scanning a focused pool of quality businesses on the 33 high quality undervalued stocks before they attract wider attention.
- Build income-focused exposure with companies that emphasise cash returns to shareholders using the 6 dividend fortresses as your starting shortlist.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com